Daily insights for city builders, delivered every morning at 6 AM ET. I’m Brandon Donnelly — a Toronto-based real estate developer and founder of Globizen. I’ve been writing here since 2013.

Tag: real estate

  • Studying to become a real estate developer

    Earlier this week I received a message from an undergraduate architecture student interested in moving into real estate development after school. That was his 10 year plan. And he had clearly read my blog post, “Transitioning from architecture to development.”

    In his message, he asked me if there were any books I would recommend he read to improve his real estate and finance knowledge, and, if I could have a “redo”, if I would still do a M.Arch (Master of Architecture) or just go straight to the MBA?

    After responding to his message, I thought: “This would make a good blog post, as well as an opportunity to talk about the current state of real estate education in Canada.” So here goes.

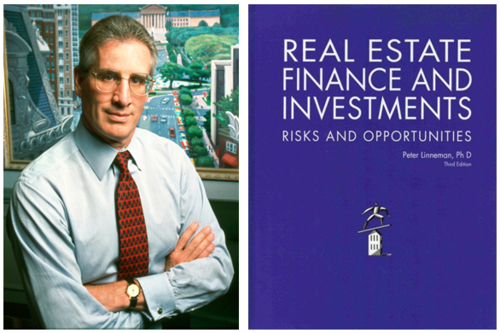
    If you’re looking for a good real estate book to get you started, I recommend checking out “Real Estate Finance and Investments: Risks and Opportunities" by Peter Linneman. It’s a much easier read and way more casual compared to most textbooks. When I was in grad school, people referred to this book as the "blue bible.” The cover on the previous edition was less purple and more blue. Unfortunately, he has also changed his glasses since the photo below.
    image

    To his second question, if I were to do it all over again, I wouldn’t change a thing about my education. I loved architecture school and combining it with business school classes and a real estate concentration was the best thing for me. I never wanted to be just a “numbers guy”, but I also never wanted to be a fanciful artist type who didn’t know how to build and manage a pro forma.

    Now, let’s talk about real estate education in Canada.

    I think we’re way behind. In the US, you can do a Master of Science in Real Estate Development, a Master of Real Estate Development, and all sorts of other real estate degrees. In Canada, you’re probably doing a MBA with a few elective real estate classes. Real estate is the largest asset class in the world. Does that not justify a dedicated degree?

    Part of the reason for this, I think, is because real estate development is still very much an entrepreneur’s business–though it has become more institutionalized in recent years. Because of this, people get into development from a variety of different professions. They just need that entrepreneurial hutzpah. And that’s all fine, but I still think that the profession, the economy and our cities would benefit from University trained developers.

    So if you’re reading this University of Toronto, I think–and I’ve thought this for awhile now–that The John H. Daniels Faculty of Architecture, Landscape and Design and The Rotman School of Management should get together and collectively form a real estate program. Who’s with me?
  • Airbnb for retail spaces raises $7.3 million

    Though it’s sometimes common to downplay “this for that” startups (that is, derivative startups that try and borrow a model and use it in another market), Storefront–which can be described as Airbnb for retail spaces–has just raised a $7.3 million Series A round.

    Storefront is a marketplace for short term retail space (think pop-up shops). People with space simply create a listing and decide how much they would like to charge per day, per week or per month. In doing so, Storefront “helps all sorts of brands, sellers, and merchants to create their first brick and mortar retail experience.”

    What I find interesting about Storefront, and other startups like Airbnb, is that they’re really rewriting the way real estate marketplaces work. Instead of large retail landlords (Storefront) and multinational hotel operators (Airbnb), technology is allowing individuals to now participate in these marketplaces. Supply is being decentralized and anyone with extra space can participate.

    You could argue that these sorts of informal and short term rentals are nothing new, but I don’t think there’s ever been the possibility of scaling up like there is today. I mean, just look at how much attention Airbnb has been getting in New York. These startups are having an impact on the way the larger market functions.

    Change is coming. And I think we’ll see a lot more of it in the real estate space.

  • Are condos at a tipping point?

    I live in a condominium in the St. Lawrence Market neighborhood of Toronto. And recently, I’ve had a number of “empty nesters” ask me if they could come check out my condo and get a feel for what it’s like to live in a downtown neighborhood like the Market.

    And they’re asking because they’re contemplating something that has become quite common for folks whose kids have left the roost. They’re considering, for a number of reasons, selling their suburban home and right-sizing to a downtown condominium.

    Whether it’s because they want to free themselves of cutting grass and shoveling snow, they don’t like stairs anymore, they want to be able to lock the door and head to Florida for the winter, or they want an amenity rich urban lifestyle, the uptake on condos has been significant both in Toronto and other cities around the world.

    Indeed, the condo market has become great at serving “both ends” of the market: first time buyers/young professionals and empty nesters. But what I wonder is if we might be at a tipping point with respect to the middle segment of the market: families.

    The average new construction low-rise home in the Greater Toronto Area is roughly $650,000 right now. But this would be more for houses in the center of the city. There, you’re probably looking at anywhere from $650,000 to $1 million for a “typical” 3 bedroom Toronto house.

    By comparison, a new condominium might average somewhere between $550 and $600 per square foot in the city. So for a 3 bedroom condo at, say, 1,300 square feet, you’d be looking at somewhere between $715,000 and $780,000. Add in parking and you’re somewhere between the mid $700,000’s and just over $800,000.

    In all cases, we’re talking a lot of money. But the point I’m trying to make is that condominiums and houses are becoming cost competitive. There are obviously differences between both housing types, but if your goal is a 3 bedroom place to raise a family, that utility could be met in both cases.

    There may still be psychological/societal barriers to raising kids in a condo, but I wonder if we might be close to a tipping point now that the economics are starting to line up. What do you all think?

  • Where marketing is at today

    Two things happened yesterday. And since there’s a nice tie in, I’d like to talk about both of them.

    First, here at TAS, we launched a new condominium project called Kingston&Co. We had already gone public with some information, but we now have an updated rendering and we’ve gone live with a public Q&A section on our website (kingstonandco.ca). The questions are all geared towards topics that we think are on a lot of people’s minds and anybody can respond. Instead of trying to cover up the elephant in the room, we wanted to do the opposite and get it out and into the open. It’s all about promoting greater transparency.

    Second, I watched this 45-minute interview with author and entrepreneur Gary Vaynerchuk last night before going to bed. It’s a great video and I would encourage you to watch it if you have any interest in entrepreneurship, social media, marketing, capitalism and overall hustle. But if you don’t have the time, here are some of my key takeaways. Gary makes, on average, between $3-5 million a year selling the social media dream (but it could be more depending on things like his angel investments). Everybody is a media company first. He has clients putting 100% of their marketing dollars into social media and they’re seeing a ROI. It took him 1 ½ years to get anybody to care about his video blog Wine Library TV. And don’t just ask. Give as well.

    That last point is a tie in to his latest book called Jab, Jab, Jab, Right Hook. And what he’s effectively saying is that, as a brand, you need to be mostly giving to your customers (that’s the jab). It could be valuable content you produce via social media or whatever. It’s you, delivering value to your customers in some way. Then, once you’ve done that, you can go in for the right hook, which is the ask: Buy my stuff. The idea is that you build up trust with your customers and develop a relationship so that you get the privilege of asking them to give you money.

    The alternative, of course, is what we’re all already familiar with: brands constantly bombarding people with right hooks. It’s the let’s throw a bunch of shit up against the wall and see what sticks approach. And it’s related to the whole permission marketing vs. interruption marketing debate popularized by marketer Seth Godin.

    But Gary’s argument–and I found this really interesting–is that constant right hooks is the approach we had to take before the internet and things like social media. Those right hooks were so expensive to deliver through billboards, print ads, TV commercials and so on, that companies simply couldn’t afford to be delivering any jabs. But all that has changed with social media and technology. Now, the best brands succeed by building trust and establishing relationships with their customers–often one-by-one.

    And this is exactly what we’re trying to do with Kingston&Co. We know that there’s a lot of discussion happening in the marketplace around condos and we didn’t want to ignore it. We wanted to address it. And if you look at our messaging, you’ll notice that in most cases we’ve put “Join the conversation” ahead of the typical “Register now.” That’s because we truly do want to have a conversation.

  • What will selling your home look like in 5 years?

    Earlier today it was announced that Keith Rabois–a venture capitalist with Khosla Ventures and the former COO of Square–is working on a startup that hopes to make selling your home as easy as a few clicks. The codename for the project is Homerun.

    “For most people, homes are their biggest asset and it’s completely illiquid,” Rabois said. “This is a really expensive transaction for many people. What we’re going to provide is instant certainty, liquidity and convenience for normal people to sell their homes.”

    Rabois hasn’t shared many details, other than a pretty basic flow:

    “I’m not going to describe the exact flow, but the general point is you’ll tell us what your address is and confirm your identity, then we’ll allow you to sell your home,” he said. “Obviously there’s a variety of ways you could verify your identity that we didn’t have in 2003, when I originally thought of this idea. Like Facebook Connect.”

    This, of course, isn’t a new idea. Many companies have tried to improve the process of buying and selling homes by going online. But it’s a space that hasn’t seen a lot of innovation. I’m particularly interested because I work in real estate and it’s always struck me as a lumbering archaic industry.

    So when a name like Keith Rabois announces that they’re working on solving a problem in this space, I get excited about what might come about.

  • What makes midrise development difficult?

    A reader recently suggested that I do a post explaining why we aren’t seeing more midrise buildings going up in Toronto. Specifically, why are midrise buildings considered to be “too risky” for developers and what could be done to improve the situation? So today I’d like to focus on that topic.

    But first, let me say that I think Toronto is already in the midst of its midrise development era. The push for intensification first brought about towers, but we’ve come to realize that the tower isn’t necessarily going to serve everybody’s needs.

    Here’s what John Bentley Mays recently wrote in the Globe and Mail regarding midrise developments:

    With Duke, SQ, Nest and similar structures, we may be seeing the start of a promising design trend in Toronto’s multifamily housing market.

    And given that our Chief Planner, Jennifer Keesmaat, has been a vocal supporter of midrise, I think there’s no question that we’ll only see more and more of this type of development. Nonetheless, there are challenges. Here are a few that come to mind.

    1. Fragmented sites

    Because midrise developments typically target established main streets with smaller lot sizes, developers often have to contend with fragmented ownership in order to assemble a site. So instead of talking to one owner (say the owner of a large parking lot downtown), a developer may have to contend with a dozen owners who all need to get on board for the development to happen.

    2. Scale is too small

    Developers have a lot of fixed costs that don’t materially change whether you’re putting up a 50 storey tower or an 8 storey midrise building. Some costs are certainly variable, but there are overall economies to scale to having more units in which to distribute costs over.

    3. Community opposition

    The whole point of midrise intensification is to increase the housing supply in established neighborhoods. But along with this comes greater risk for community opposition. You may have a neighbor who’s been living for 30 years adjacent to where you want to build. And when you come along and try and build a 10 storey midrise building, they can get grouchy.

    4. Strict guidelines 

    To try and counteract community opposition (and promote good urbanism), the city has developed a number of design guidelines for midrise buildings. And while they’re well intentioned, they can be onerous for developers and designers. For example, the requirement to terrace down towards adjacent residential neighborhoods produces a lot of inefficiencies (though it does create spectacular terraces). Oftentimes you’ll end up with more unit types than you would in a large tower.

    All this said, I’m a big believer in the midrise building typology. At TAS, I’m involved in two such projects–DUKE and Kingston&Co. Both are exciting projects and both, I think, are at the forefront of a new development era for Toronto. Vancouver pioneered the podium + point tower typology. Toronto is about to do the same with midrise buildings.

  • The high cost of transacting

    This past Sunday I was over at my father’s place for dinner and we were talking about the high transaction costs associated with buying and selling homes. That is, we weren’t talking about the high price of homes in Toronto, we were only talking about transaction costs and barriers to market liquidity.

    For example, let’s say for the sake of simplicity that you own a home that’s worth $1 million and you’d like to sell it and buy a different home that also happens to be worth $1 million. In this case, you’d be making an entirely lateral move. You’re not down sizing or up sizing, you just want a different home–perhaps because you’d prefer a different neighborhood.

    In order to do this, you’re going to be faced with a number of costs. But the 2 most significant are real estate commissions and Land Transfer Taxes (both provincial and municipal). You only pay Land Transfer Taxes in Toronto when you buy (take title) of a new property, but they’re unavoidable, unless you’re a first time buyer, in which case you’d qualify for a bit of a rebate.

    Real estate commissions are technically optional, but 70-90% of the market in North America still uses a a real estate agent to sell their home (based on the estimates I’ve found). Typically a seller pays around 5% of the sale price. So in this example, you the homeowner would be paying around $50,000 in real estate commissions.

    Land Transfer Taxes would be roughly $32,000, and so you’re looking at a total somewhere around $82,000 in order to make this lateral move. This, of course, does not include legal fees or any other moving costs you might incur. It’s a hell of a lot of money and it’s a significant barrier to transacting.

    But my hunch is that we’ll eventually see real estate commissions come down. No real estate agent wants to hear this, but I think it’s almost inevitable. The internet, as a disruptive force, is bound to make it happen.

  • Target is coming to Toronto’s South Core

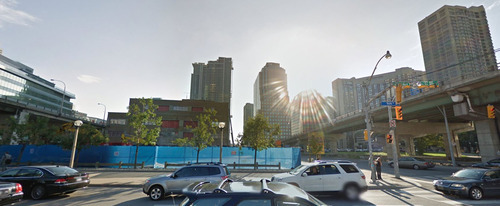
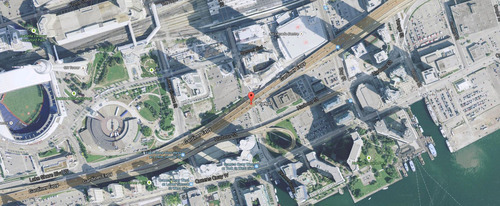
    Yesterday news broke that Target is opening a two-storey, 145,000 square foot store at the base of a new mixed-use development in Toronto’s emerging South Core neighborhood. The site is at the north east corner of York Street and Harbour Street. And the larger development, called Harbour Plaza, will include a 35 storey office tower and 2 residential condominium towers at 65 and 69 storeys.

    Here’s the location map:

    image

    And here’s the site looking east from York Street:

    image

    This is going to be huge for Target. The amount of current and proposed density within a short radius of the site is mind boggling. In addition to Harbour Plaza itself, look at what’s planned for 1 Yonge Street.

    Plus with Union Station next door, I dare you to try and find a better connected mobility hub in the region. Now all of a sudden that retail radius gets even bigger. I can easily imagine suburbanites picking up a few things before they hop on a GO train (our regional rail system) and head home.

    As of right now, they’re also the only game in town, as far as big box stores in the central core are concerned. But I wouldn’t be surprised if we see a competitor emerge alongside the 1 Yonge project. The site is big enough for one and Walmart isn’t going to want to get shut out of the area.

    My only hope is that, from an urban design standpoint, the project is able to enliven and give back to Harbour Street. Right now it’s an arterial road with really no redeeming urban qualities. But with the York Street off-ramp being relocated and the park underneath it being expanded, now is the time to really transform the area.

    Let’s hope Harbour Plaza does that.

  • All sorts of bubbles

    Fred Wilson (New York VC) wrote a post on his blog this morning called The Bubble Question. In it, he talks about how everyone asks him whether or not there’s a tech bubble, which he has been asked for the past 4 years now. It reminded me of the debates that are also happening in the real estate community (particularly in Canada).

    The thesis of his post is this:

    I learned in business school that the multiple of earnings one should pay for a business is roughly the inverse of interest rates.

    In other words, as interest rates drop, people are willing to pay more for the business or asset in question. And it’s because they can’t find the yields anywhere else.

    The same phenomenon, you could argue, is also happening in the real estate space. Typically, income producing real estate assets are assessed using capitalization rates (or cap rates), which is defined by the Net Operating Income (NOI) of the property (revenue – expenses, but excluding financing costs), divided by the price of the property.

    The real estate equivalent of what Fred is talking about is cap rate compression. When cap rates drop it means you’re paying more for the same amount of yield (or NOI). One of the reasons that might happen is because people are anticipating that the asset will appreciate. But it could also be because interest rates are so low that investors will take whatever returns they can get. 

    So you could argue that the market is just responding to the macro economy. And since the feds are probably waiting for global growth to pickup (before raising rates), one could argue that the status quo is just going to continue. Ideally, it’ll continue until robust economic growth is able to take the place of cheap money.

  • What are Generation Y condo dwellers going to do when they have kids?

    I gave a talk about condos this evening at the Ted Rogers School of Management. For regular readers of this blog, the material wouldn’t have been all that new. I talked about supply and demand in housing markets and 2 of the projects that TAS is working on. The best part though was the Q&A, which, I think, was longer than the actual talk.

    One question that I particularly liked (maybe because I’ve blogged about it before) was the question of what all these Generation Y condo dwellers are going to do when they decide they want a family. We know that people are getting married later and that more people are living alone. So there are some demographic changes at work here. But people are still going to have kids and people are still going to need more space.

    At that point, I think 2 other, interrelated, factors come into play: first, a lot of people still feel you need a house in order to raise kids; and, second, there’s a problem of affordability. Multi-family dwellings (built out of reinforced concrete) are inherently more expensive to build than wood-framed single family homes.

    To deal with these factors, a lot of young couples in Toronto (at least from my own empirical research) seem to be looking to inner city neighborhoods like Leslieville, Roncesvalles, Trinity Bellwoods, High Park, the Junction and so on. They still want to be in the city, but they want a house, for their kids. Problem is, everybody is trying to do the same and it’s creating tremendous pressure on our low-rise housing stock.

    So what’s going to happen in the longer term?

    Well if low-rise housing keeps appreciating at the rate it has been, we could reach a point, I think, where all of a sudden condos become the more cost effective solution.

    For example, let’s say a young family is looking for a 3 bedroom home. It’s not inconceivable that the 1,500 square foot, 3 bedroom condo could become the cheaper option. At $650 per square foot (I’m assuming a slightly higher number because I’m assuming this is at some point in the future), you’re looking at roughly a million dollars. No question this is a lot of money, but what if the alternative (a single family home) is $1.5 million?

    I’m sure there will always be a segment of the market that rushes towards the suburbs and/or a house when they decide they want to have kids. But I think we’ll see more and more families decide–either because of cost or because of a lifestyle preference–that having children in a condo isn’t all that bad.

    What do you think? Would you ever raise children in a condo?