Daily insights for city builders, delivered every morning at 6 AM ET. I’m Brandon Donnelly — a Toronto-based real estate developer and founder of Globizen. I’ve been writing here since 2013.

  • Waymo is coming to Toronto, but it won’t fix car dependency

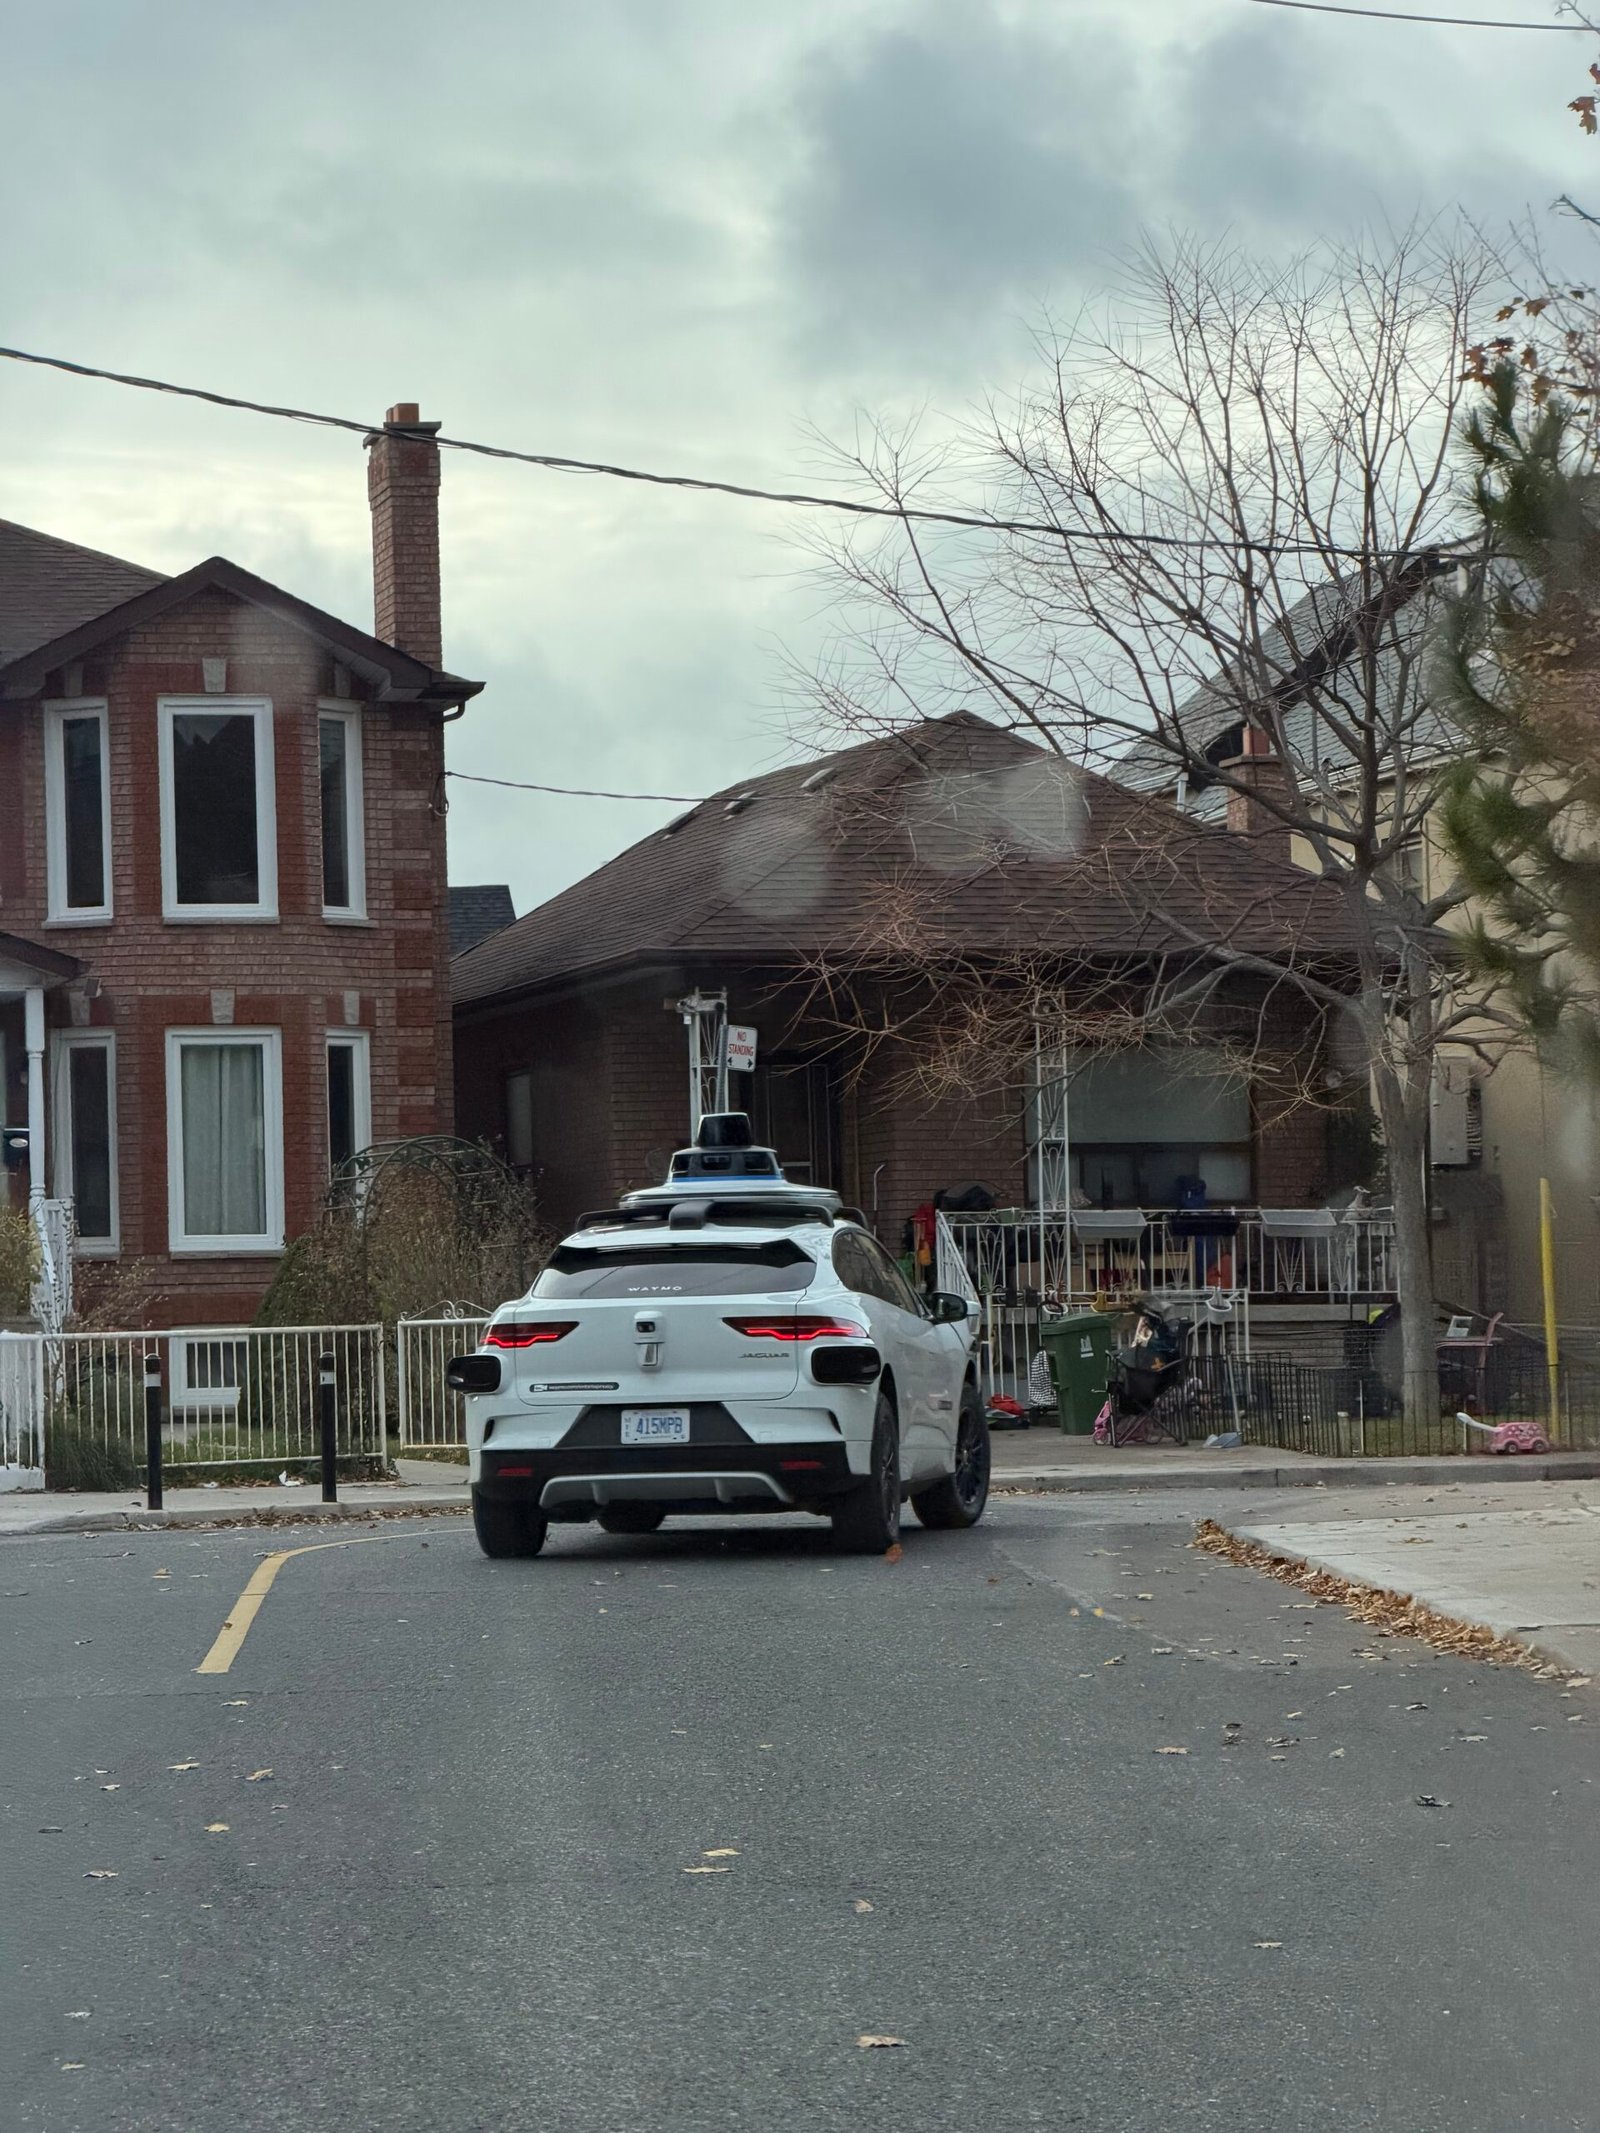
    I saw my first Waymo training vehicle over the weekend in Toronto. There was a human in the driver’s seat, and collectively they seemed to be obeying all of the rules of the road in a cautious and predictable manner.

    If you’re a regular reader of this blog, you’ll know that I’m excited about the rollout of autonomous vehicles in the city for a few reasons: one, it’s the future; two, they’re already dramatically safer than human drivers; and three, I hate driving and would love to never have to drive again. I also think that right now is the absolute perfect time for Toronto to finally implement road pricing.

    But we should also be clear about what autonomous vehicles won’t mean for Toronto. In the early days of Uber and the promise of self-driving cars, there was a core belief (or at least a marketing proposition) that ride-hailing and the like would reduce private car ownership.

    We now know that isn’t the case. Once the venture capital subsidies dried up, Uber became more expensive and less luxurious, eliminating a cost incentive to change. And to date, Waymo pricing is on par with or even higher than Uber, despite there not being a driver.

    What we know definitively is that the most effective way to reduce car ownership and dependency is to combine dense, mixed-use communities with effective public transit and support for other non-car forms of mobility.

    Autonomous vehicles will certainly have an impact on our cities, and in ways we are not yet thinking about, but I have yet to see evidence for a more efficient built form and mobility approach than the one cities have been building since they were first created.
  • What two mid-rise infill projects tell us about New York and Toronto

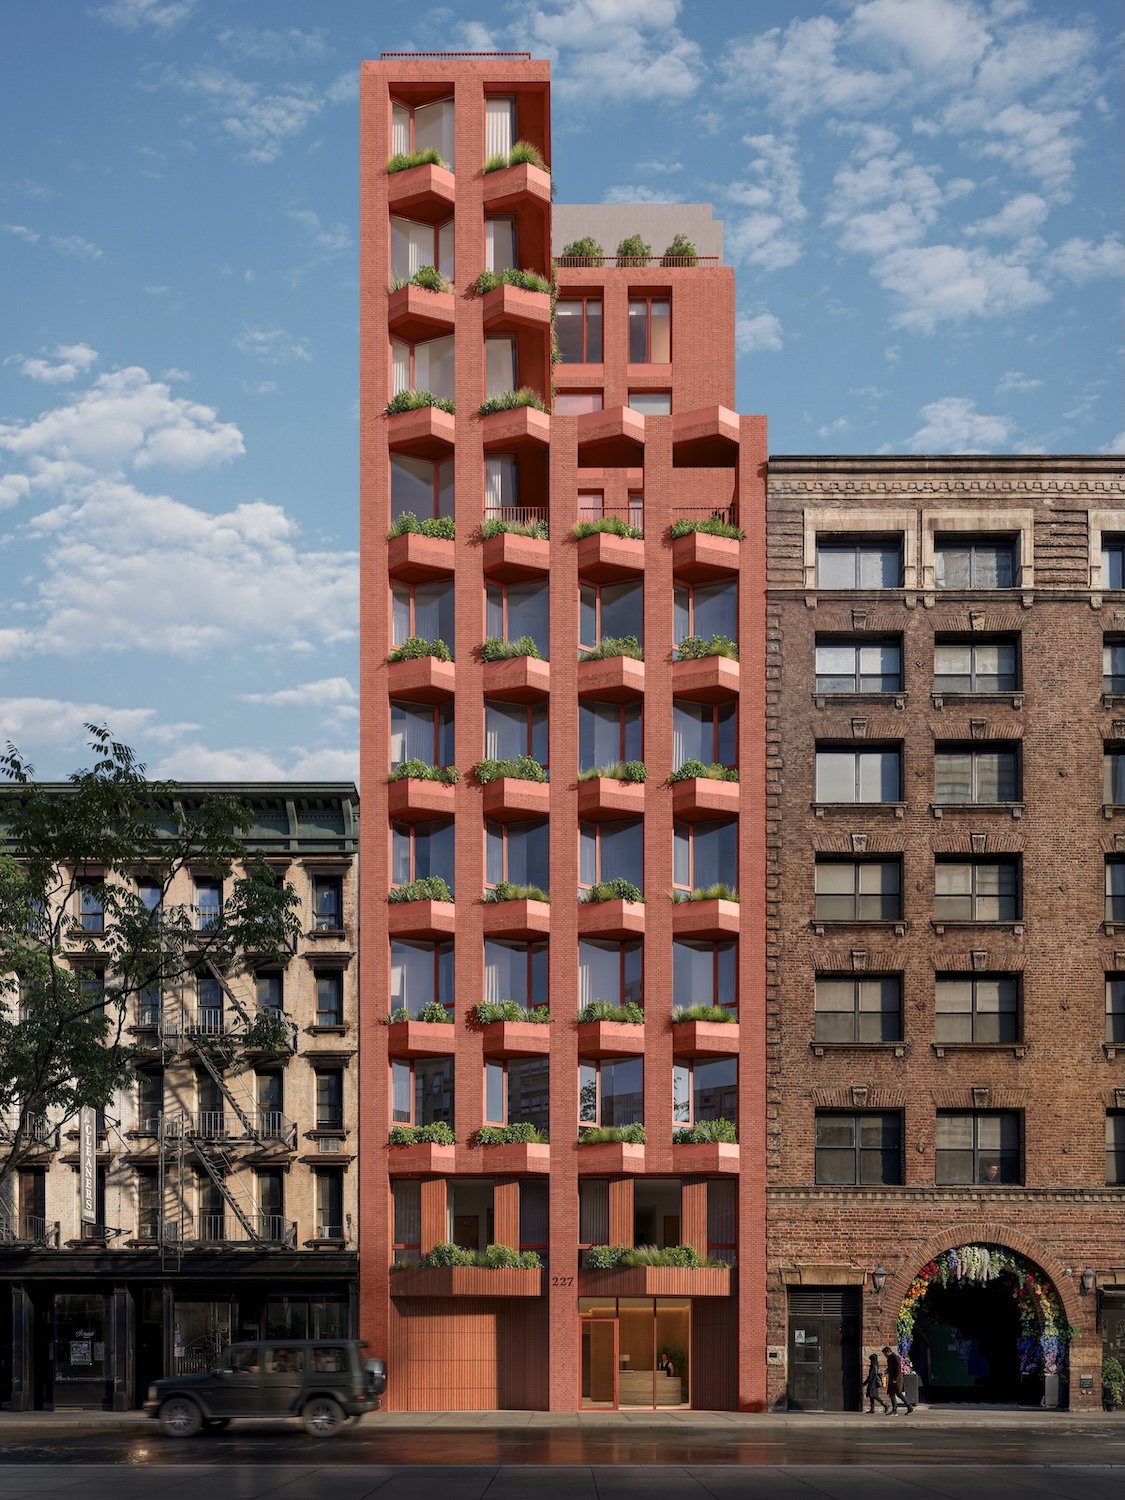
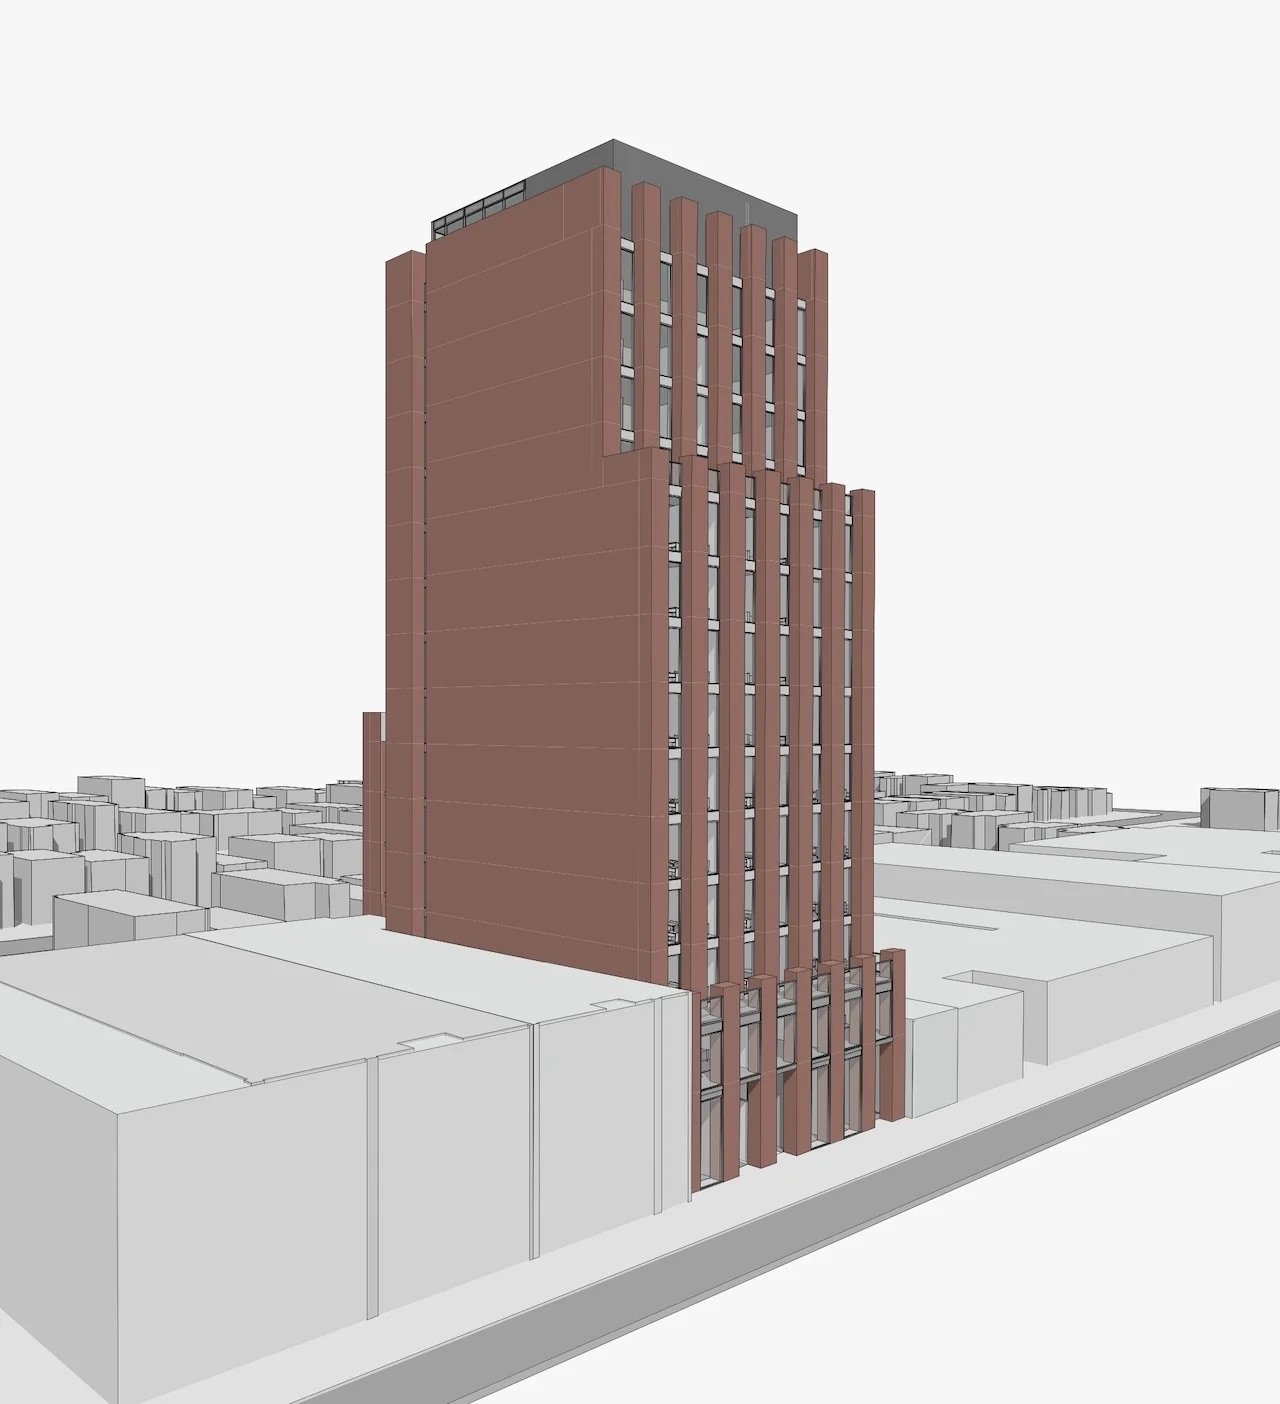
    This under-construction 11-storey residential building in Chelsea (Manhattan) reminded me of the 14-storey building I recently blogged about that is proposed for 2273–2279 Bloor Street West here in Toronto.

    Now, the latter is a bigger building at around 70,000 square feet versus just under 40,000 square feet for the former, but they are both urban infill sites next to transit and they both have site depths that appear to be around 30 metres (I was specifically curious about this).

    One key difference is that 227 West 19th Street is under construction on a street that is already fully built out at a similar scale, whereas the proposal on Bloor Street is a pioneering project. It represents what the area will surely look like in the future.

    The other key difference is the kind of housing they will deliver. In the case of New York, only 8 condominium homes are being built across the 11 storeys; in the case of Toronto, 60 homes are being proposed (which, I believe, are rental).

    Put differently, Manhattan is de-densifying through ultra-luxury boutique projects, and Toronto is trying to graduate from a “city of neighbourhoods” characterized by single-family homes and low-rise main streets into a true polycentric global city.


    New York rendering via DN8 Agency; Toronto rendering via Toronto’s Application Information Centre

  • The 3-hour rule for high-speed rail

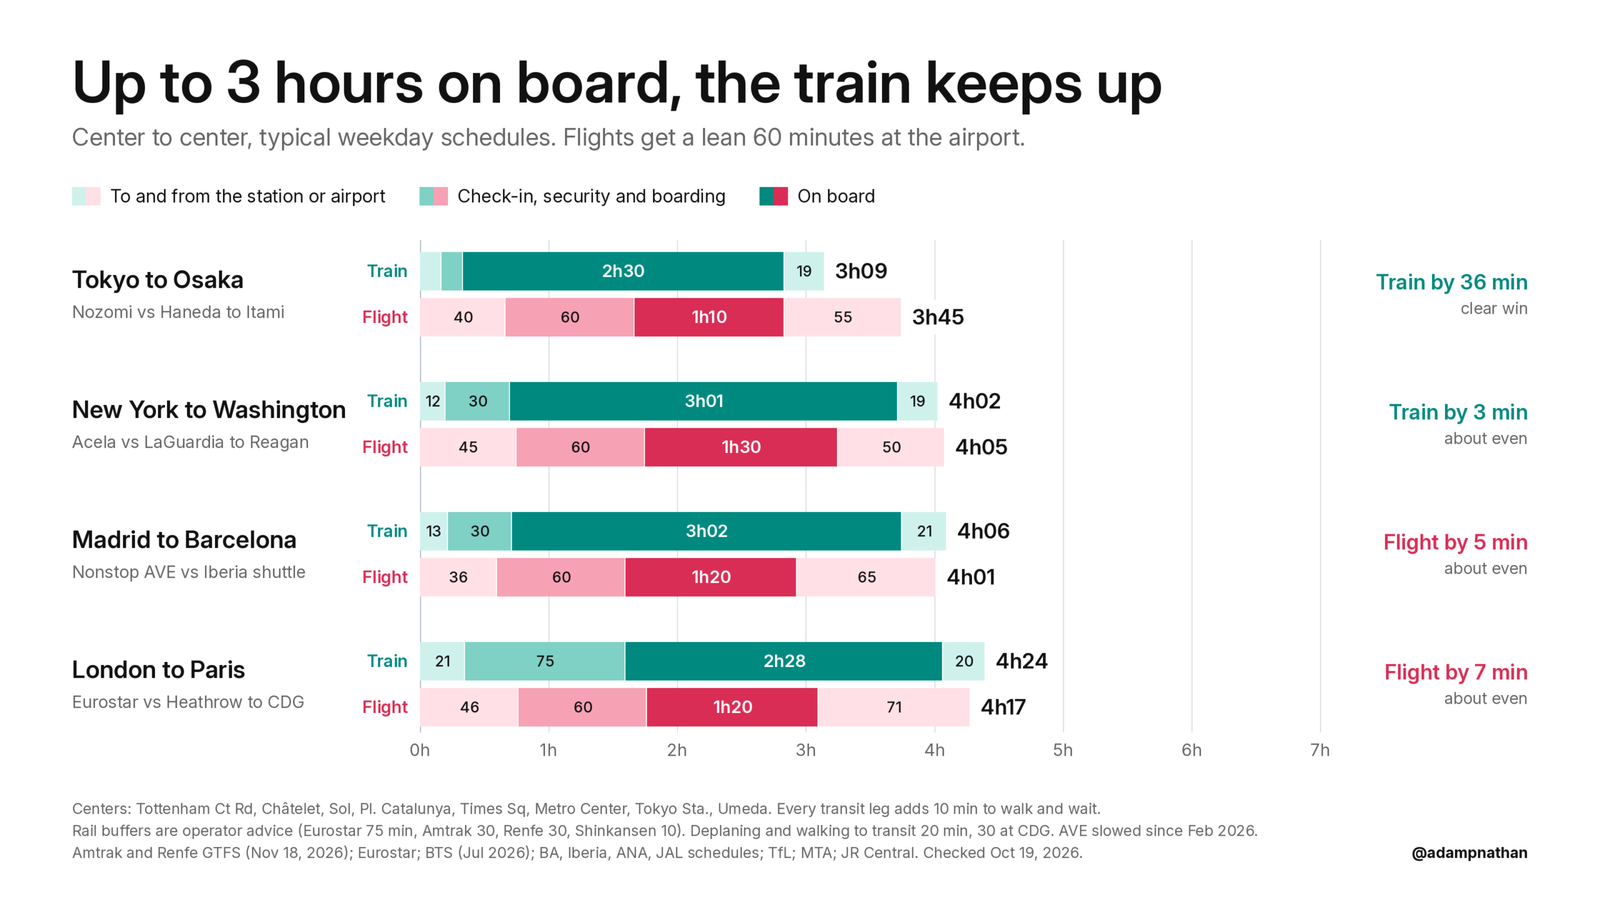
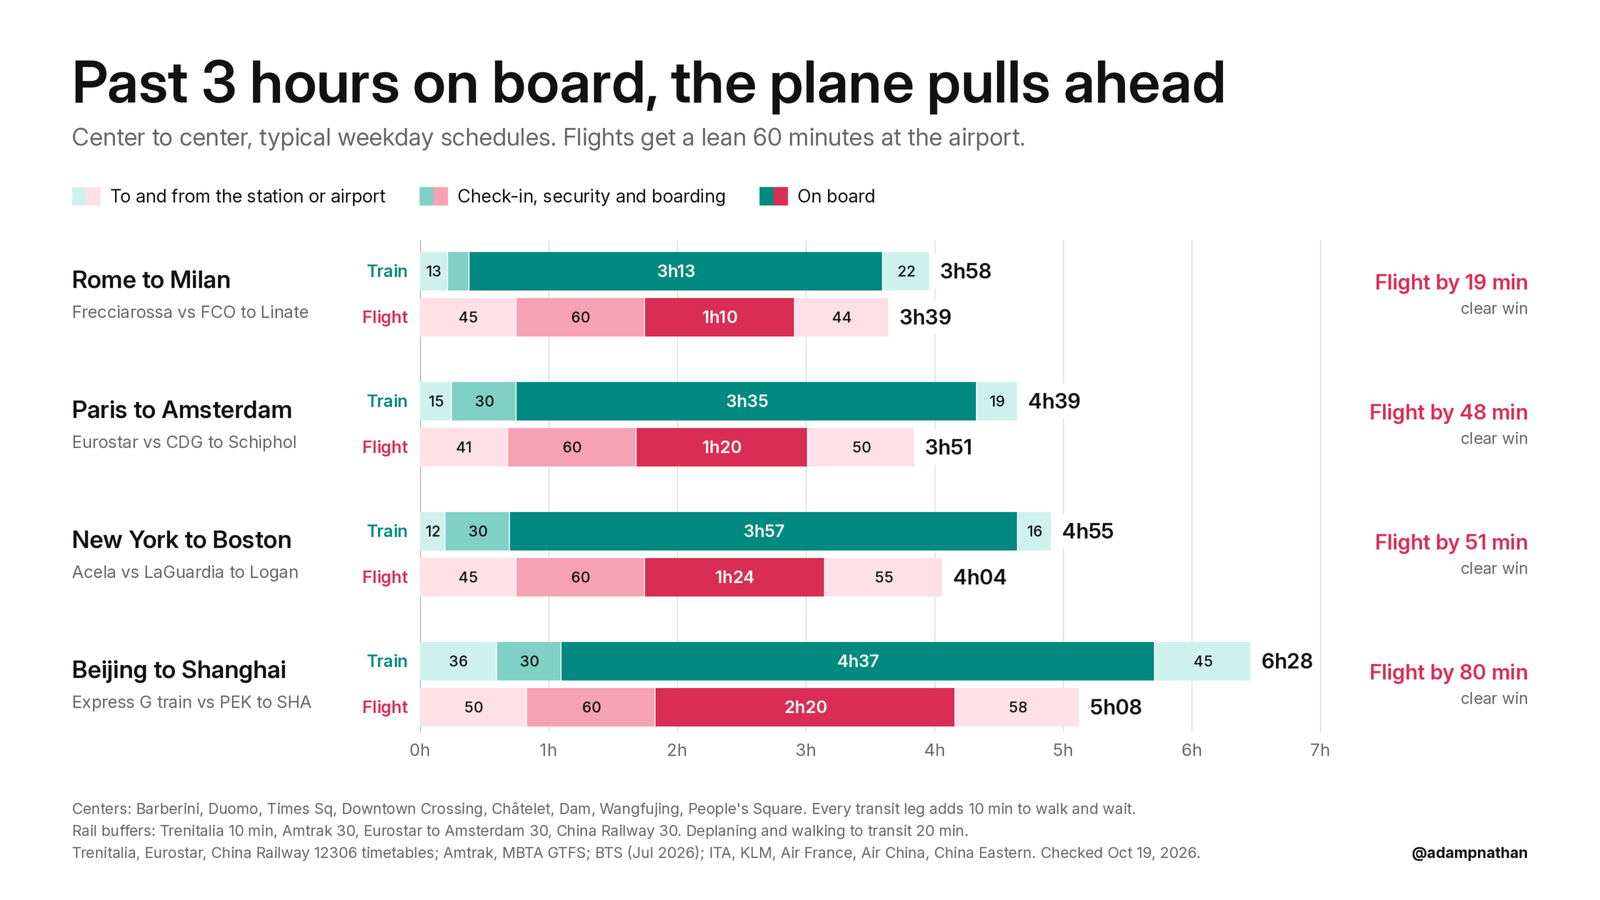
    I recently started following Adam Nathan’s posts about airlines, airports, and travel in general. This week he posted a comparison between taking the train and flying for 8 city pairs. The comparison looks at door-to-door time, factoring in the time it takes to travel to and from each station or airport; how long check-in, security and boarding take; and then how long you’re actually on board.

    What he found was that 3 hours on board a train tends to be the magic number. Once you pass this duration, travel times tend to flip in favor of flying. The one exception seems to be London-Paris, which is only a 2.5-hour train ride, but has a longer check-in time, presumably because you’re crossing a border in and out of the EU’s Schengen Area.

    I’m going to assume that the people planning Canada’s high-speed Alto train are similarly doing rigorous analyses such as these. Good case studies for us are Rome-Milan and Madrid-Barcelona. Both routes have on-board train times of about 3 hours and have a similar distance to Toronto-Montreal.

    If you want to ensure that high-speed rail is a success in Canada, make it faster, cheaper, and generally better than flying. This seems to include keeping the on-board time at or below 3 hours.

  • The math behind Toronto’s sixplex rollout

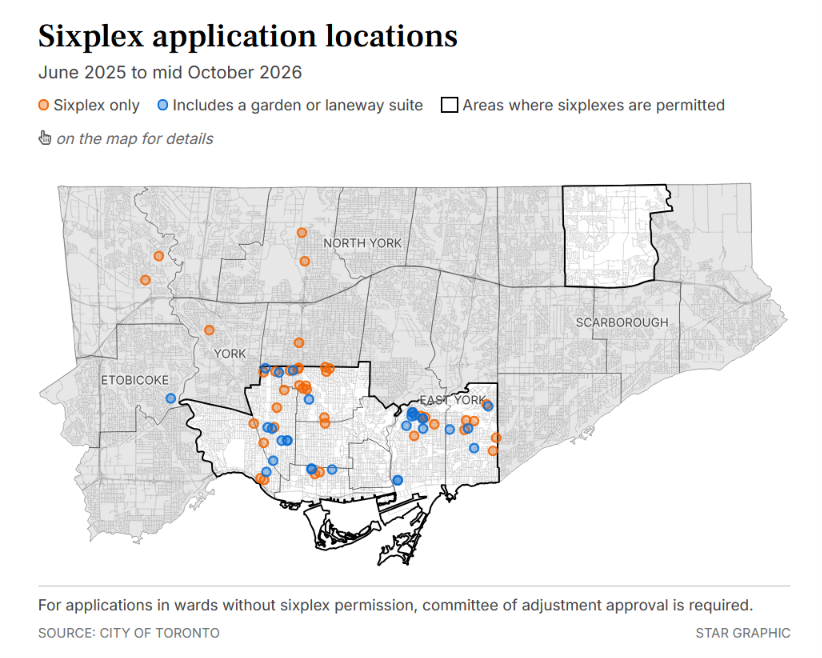
    Toronto started allowing sixplexes as-of-right across 9 wards last summer. Since then (and according to the Toronto Star), the city received 60 permit applications, more than half of which also included a garden or laneway suite (so 7 homes total). Our project at 571 Oakwood Avenue should be on the below map, but I don’t have access to the paywalled article to take a closer look:

    If we assume that 30 of the applications included 7 homes and the remaining 30 only had 6 homes, that’s a total of 390 homes, most of which were permitted as-of-right for the 16-month period between June 2025 and October 2026. Annualized, let’s call this 300 homes in the first year.

    What is obvious is that, for a city of 3 million people, this isn’t nearly enough. But we also know that it takes time for the market to respond to new policy changes and that we will certainly see an increase next year.

    In my view, if we saw a few thousand new homes delivered this way each year, it would be a policy success. So let’s say that we need to 10x the number of homes, which would mean bringing the annual project count from ~45 to 450.

    This feels doable, though it does remain to be seen how well this model will work in the inner suburbs. It’s worth noting that the one ward in Scarborough that currently permits sixplexes has yet to see an application according to this dataset.

    The big barrier is likely parking. Most of these infill projects are being built with none of it, and that means they’re only really feasible from a market perspective in areas that are walkable and have acceptable levels of transit.

    Even still, it’s not inconceivable to think that we could increase the annual application count to a few hundred. And this would be meaningful because it’s the most cost-effective way to deliver new infill housing. Single-family homes are obviously more expensive to build, and so too are higher-density concrete buildings.

    Add in six-storey buildings along the city’s major streets, and suddenly you’ve got missing-middle housing making a real contribution to Toronto’s housing needs.

  • The electrification of the global economy is here, but big bottlenecks remain

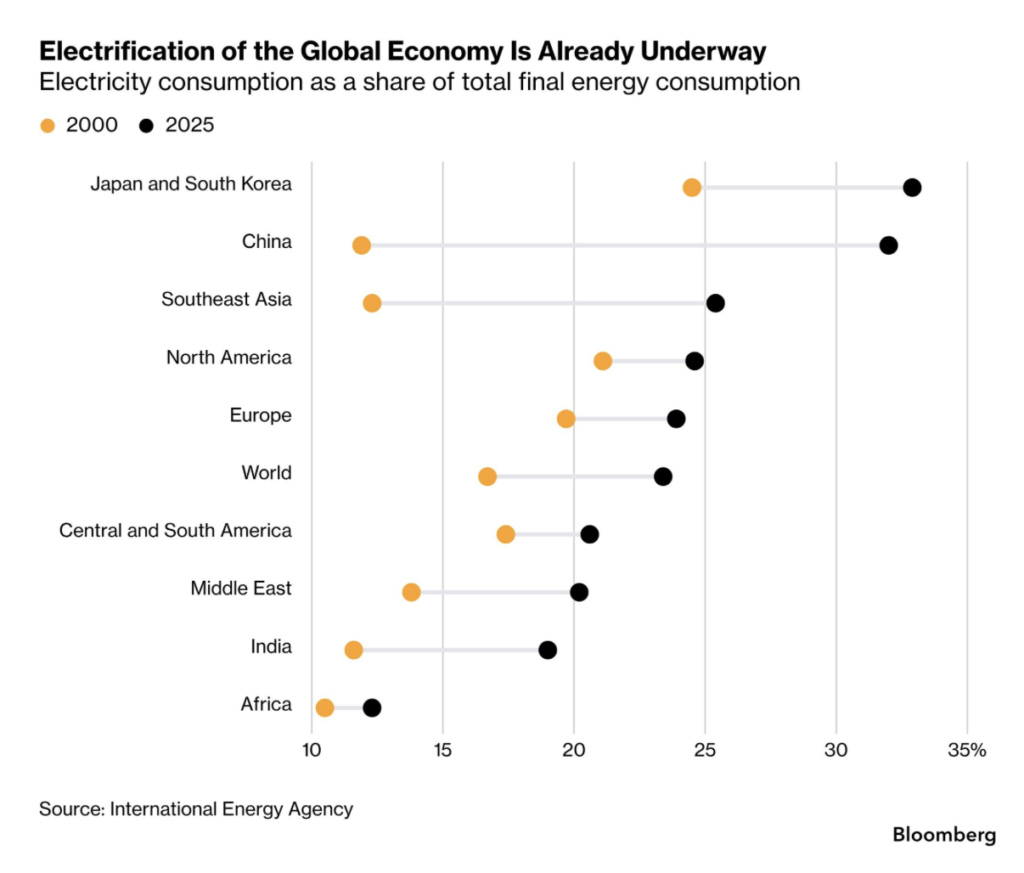
    The 31st UN Climate Change Conference (also known as COP31) is currently underway in Turkey. And one of the pledges being championed is a goal to increase electricity’s share of global energy consumption from about 23% to 35% by 2035 (the tagline is “35 by 35”).

    Of course, the electrification of the global economy is already underway. Here’s a fascinating chart from Bloomberg:

    Seeing what China has accomplished in 25 years is extraordinary. About a third of its total energy consumption is now electricity. Here in Toronto, I can also say that on all of our new infill rental projects, we are aiming to be 100% electric and have solar panels on the roof. We’ve also been exploring photovoltaic facades, and there’s a business case to be made for it.

    But the rubber does eventually meet the road somewhere, and the big challenge we are facing — one that I have blogged about before — is the high cost of new electrical services. It can be prohibitive on both small and large housing projects, where offers to connect can come with a bill that reaches into the high seven figures!

    The electrification of the global economy is the right direction, but it’s going to take a concerted effort across many different stakeholders.

  • A misleading condo narrative

    One of the market narratives at this point in the development cycle is that, as an industry, we’ve built too many “shoe box condos” and that what people really want are more family-sized homes.

    Now here’s some data from BC (via The Globe and Mail):

    As of the end of the third quarter of 2026, the Lower Mainland had 5,770 completed but unsold condos either in high-rise concrete buildings or low-rise wood-frame buildings. That total consists of 177 studio units, 88 junior one-bedroom units, 1,859 one-bedroom units, 2,865 two-bedroom units, 598 three-bedroom units, and 32 four-bedroom units. (The remaining 151 units could not be classified.)

    The region is also home to 1,253 completed unsold townhouses, the vast majority of which have two or more bedrooms.

    What this means is that over 66% of the standing inventory in the Lower Mainland is what one could call “family-sized housing” — in other words, they are homes with 2 or more bedrooms. This suggests that the prevailing narrative isn’t entirely accurate.

    The reality is that small condominiums and apartments exist because they are a natural market response to scarce land and high development cost structures.

    This is why simply mandating larger suites doesn’t solve the problem, nor does offering more “family-friendly” floor plan designs. Both ignore the more fundamental issue: large suites are expensive to build.

    I would also assume that some buyers are now substituting single-family houses for condos. I’m seeing that in Toronto. Whatever the exact situation, the answer isn’t as simple as too many small suites. In fact, based on the above figures, those are the ones that sold first.

    True market preferences will only reveal themselves when we lower the structural cost of building new housing and permit a variety of different building types.

  • Beyond left and right in city building

    I tweeted this morning (actually it was a post I scheduled weeks ago) that I generally don’t understand why so many city-building issues become political.

    The example I gave was corner stores, more specifically small-scale retail within neighbourhoods. Does wanting to be able to easily walk to amenities from my home place me on the left or the right of the political spectrum?

    I thought of this because every now and then someone will respond to one of my posts and sling some political moniker back at me in an attempt to debunk my argument.

    And each and every time it makes me stop and think: Am I really that? I don’t like the idea of being neatly placed in a particular bucket, and that bothers me far more than someone disagreeing with my point.

    When I ask AI to tell me what it thinks of me based on over 13 years of daily city-building posts, it says this:

    Based on your writing on brandondonnelly.com, you do not fit neatly into conventional partisan left/right buckets. Instead, your positions place you firmly in the pro-growth, market-urbanist / “Abundance Agenda” quadrant: culturally and socially progressive, strongly urbanist, yet grounded in market discipline, capital allocation, and regulatory pragmatism.

    This doesn’t sound wrong.

    But the result is that I often sit on different sides. I’m for bike lanes and neighbourhood retail, but I’m against inclusionary zoning and I don’t believe that rent control as a broad tool achieves its desired housing outcomes.

    At the same time, I also think you can look at specific issues from completely different perspectives.

    Bike lanes, for instance, are typically associated with centre-left progressives, but I see them as a capital-efficient, high-throughput form of mobility that increases individual choice and helps wean us off government-subsidized roads.

    Road pricing (or congestion charges) can similarly be viewed as a left-leaning tool that curbs emissions, promotes transit usage, and assuages the bike-lane crowd.

    But it’s actually the most fiscally conservative way to price roads. It’s classic Milton Friedman. Congestion is merely an economic failure: an artificial shortage caused by zero user cost on a scarce good.

    If I’m an advocate for anything on this blog, it is looking at each issue independently, trying to arrive at some understanding of the truth, and then being open to completely changing my mind if I end up being wrong.

  • The immediate returns of a car-free Oxford Street

    It’s only been about two weeks since London pedestrianized Oxford Street. While it’s certainly possible that more people are visiting the street purely because of its novelty, the initial reports are positive.

    In the first six days after it was pedestrianized, the broader West End area saw a 13% increase in transactions on Barclays debit and credit cards.

    What’s more, separate figures published by payments company Adyen show that in-store transactions across 40 different businesses on Oxford Street increased by 19% both week-over-week and year-over-year.

    While the datasets remain limited, all of this is promising and, in my view, expected. Oxford Street is coming off a difficult decade, during which vacancies rose to 13.7% in 2022 and average retail rents declined from £1,100 per square foot in 2016 to £600 during the pandemic.

    London is aiming, as it should, to compete with Fifth Avenue and the Champs-Élysées with this £150 million investment. This is an effective way to do that.


    Photo by Bryan Brittos on Unsplash

  • The end of CMHC’s multi-family monopoly

    The Department of Finance Canada just announced new mortgage loan insurance parameters aimed at expanding “missing middle” housing supply. The rules take effect for applications submitted on or after February 1, 2027, and they provide financing options for projects with 3 to 4 units and 5 to 50 units. Here’s the official announcement.

    What’s new and noteworthy is that the insurance rules are being amended to permit private mortgage insurers to back multi-family loans and to introduce greater flexibility for smaller three- and four-unit projects. In other words, the CMHC monopoly is ending for multi-family rental housing with 50 or fewer homes.

    At a high level, this is good. It will increase competition, because before, CMHC was the sole insurer, and it could often lead to problems of being stuck in the queue. I mean: We currently have a project that is shovel-ready with permits in hand, except we’re waiting on CMHC.

    The way I read these new rules is that they also create a new financing baseline. If you want to build new market-rate rental housing within the 5-to-50-unit bracket, you can expect an LTV of 90%, a maximum amortization of 50 years, a minimum DSCR of 1.1 (for 10-year terms), and a net worth requirement equal to at least 25% of the loan amount.

    If you want better terms than this and the project can support greater affordability, environmental, and/or accessibility features, well, then there’s still CMHC’s MLI Select points-based program.

    Streamlining and simplifying everything around missing middle housing is the key to unlocking more of it. Permitting, financing, design (things like single-stair), servicing (hi, Toronto Hydro), and environmental requirements (I’m thinking specifically of Records of Site Condition) all need to be fast and straightforward.

    Let’s hope this announcement improves the financing category.

  • Parkview Mountain House is now open for winter 2026/2027 bookings

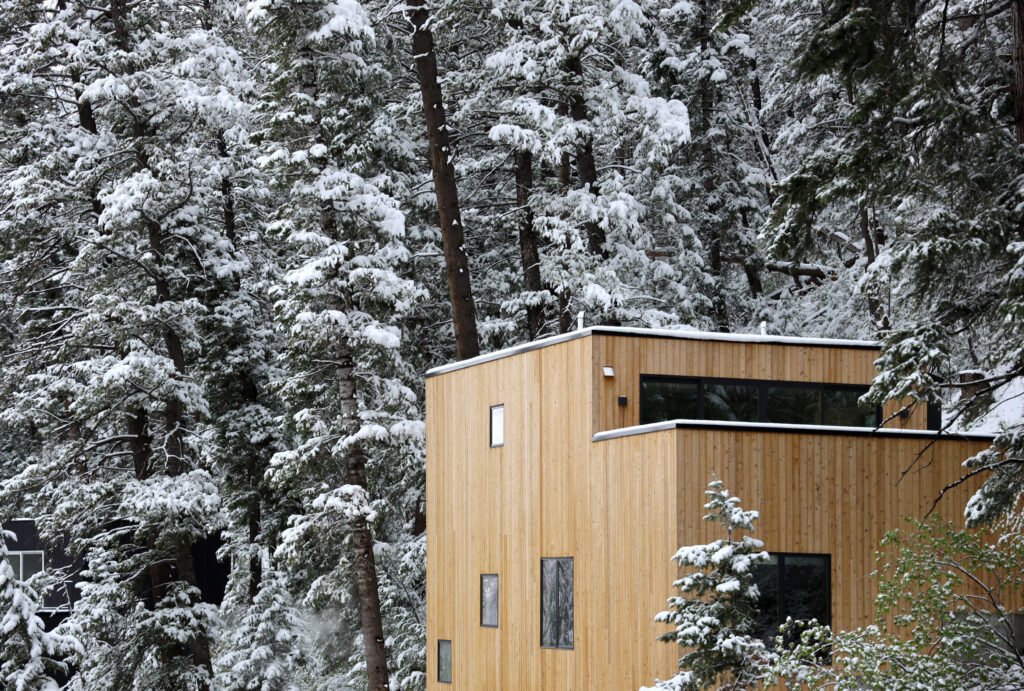
    I’m in Park City right now working à distance, hanging with the family, and puttering around Parkview Mountain House in the evenings preparing for this winter season. I’m now excited to announce that PMH is officially open for winter 2026/2027 bookings! Here’s our website and here’s the direct link to our Airbnb listing.

    Now the important question: Will it be an epic winter with lots of snowpack?

    The honest answer is I don’t know, but the El Niño weather pattern in the Pacific is, as I understand it, a promising precondition. In fact, Ski Utah even launched a “Vote Super El Niño” campaign ahead of this year’s US elections. Maybe that was more just for fun.

    Regardless, there is actually a science behind Utah’s title of “The Greatest Snow on Earth.” I even bought a book on it, got deep into snow, and blogged about it here. Based on this cursory knowledge, I’m optimistic that this year is going to be a good one.

    Whenever I tell people about PMH, I’m often asked: Why Utah? And the obvious answer is the snow. But it’s also one of the most accessible ski towns. There are nearly a dozen resorts within an hour’s drive of SLC airport, and PMH itself is 27 minutes from the terminal.

    On this trip, we checked out Sundance Resort for the first time. Previously the Timp Haven resort, actor Robert Redford bought it in 1968 and renamed it the Sundance Mountain Resort, after his film Butch Cassidy and the Sundance Kid.

    I can’t speak to the mountain itself, but Bianca and I were both super impressed by the resort and the vibe. It has an elevated feel, and it’s clearly very popular throughout the year. We tried to have dinner there, but the restaurant was fully booked. So instead we bought a Sundance sweater for Vivienne. Now I can’t wait to snowboard there. (It’s a 50-minute drive from PMH.)

    If you like skiing and snowboarding or baby Sundance sweaters and want to visit Utah, you can check out Parkview Mountain House here.


    House photo by PMH creative resident Ryan Schwartz