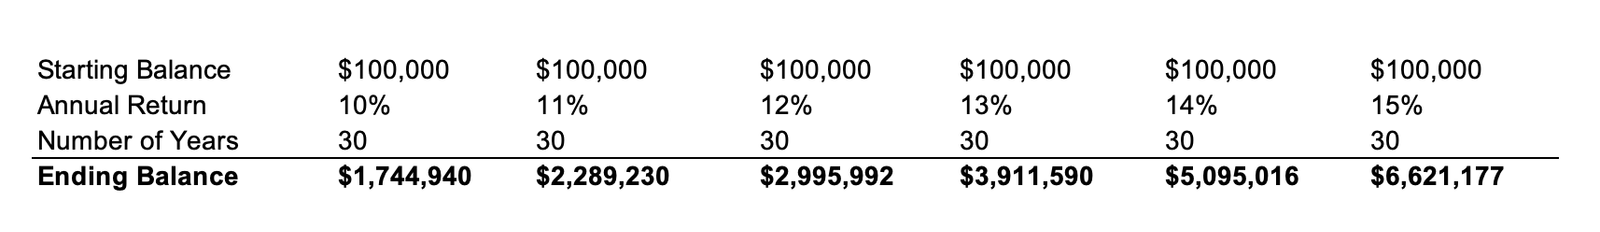Daily insights for city builders, delivered every morning at 6 AM ET. I’m Brandon Donnelly — a Toronto-based real estate developer and founder of Globizen. I’ve been writing here since 2013.

Category: Uncategorized

  • The movable icon of Paris

    April 27, 2026 · View original


    Movable chairs have been a feature of Parisian parks since the 18th century. Chairs are more comfortable than benches, and movable ones allow you to direct yourself toward the sun, cluster in groups, or just situate yourself so that you can prop your legs up and read a book.

    Now, here’s a brief story of how this came to be.

    At the outset of this innovation, park chairs weren’t free. If you wanted a bench upgrade, you had to pay. Private concessionaires would rent them out to visitors (like umbrellas at a beach), maintain them, and presumably ensure that things were kept generally tidy around the grounds.

    Then, around 1923, the iconic green Sénat chair was designed by the Ateliers de la Ville de Paris. If you’ve ever been to Paris, you know this chair (see cover photo). It comes in only three models: chair, armchair, and recliner, all of which are green. RAL 6013 green, to be exact.

    Eventually, the Sénat chair was imposed as the Parisian park chair. By 1955, it was the only possible option that could be rented out by concessionaires in places like the Jardin du Luxembourg. This set the stage for it to become one of the most recognizable symbols of the city.

    But due to the popularity of these chairs and the fact that people would rather not have to pay to sit in a park, it was decided in 1974 that the chairs should be free, and they were bought from the concessionaires.

    In 2002, Frédéric Sofia designed an offshoot of the chair called the “Luxembourg.” The Luxembourg is made of aluminum, as opposed to steel, and is therefore lighter. It’s also available for sale to the general public, whereas the Sénat chair is exclusively for city parks.

    The result of this centuries-long tradition is an iconic symbol for the city and an established culture of employing movable chairs in public spaces. A humble movable chair may not seem like a big deal, but in the world of public spaces, it is.

    Try to incorporate movable chairs into a park or public space today and, invariably, someone will tell you that it can’t or shouldn’t be done. They will say the chairs will be stolen, vandalized, and/or weaponized by hooligans. Perhaps not.

    Today, there are some 4,500 movable chairs in the Jardin du Luxembourg alone. Paris shows us that it can be done.


    Cover photo by Brigi Harkányi on Unsplash
  • How AI could strengthen our cities

    And the surprising link between railroad history and the AI era

    April 26, 2026 · View original


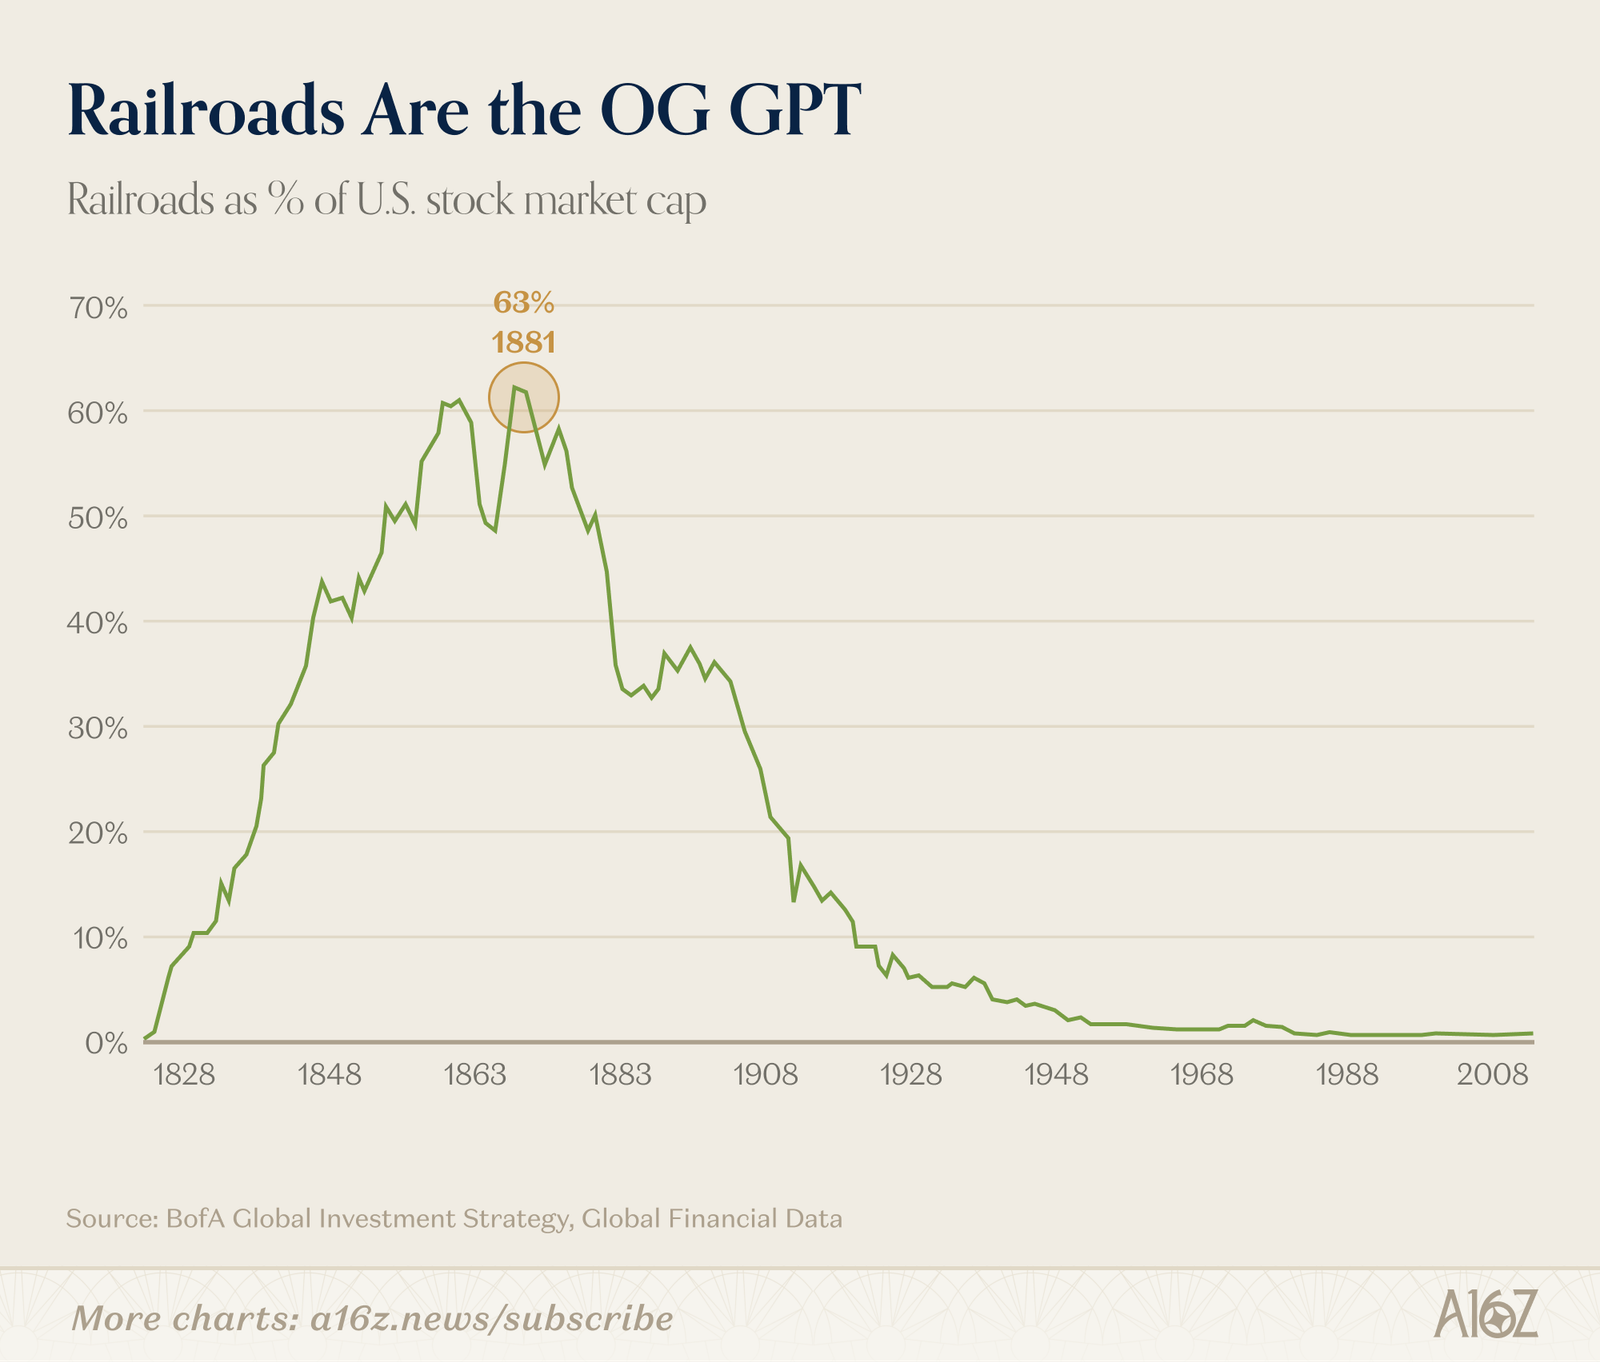
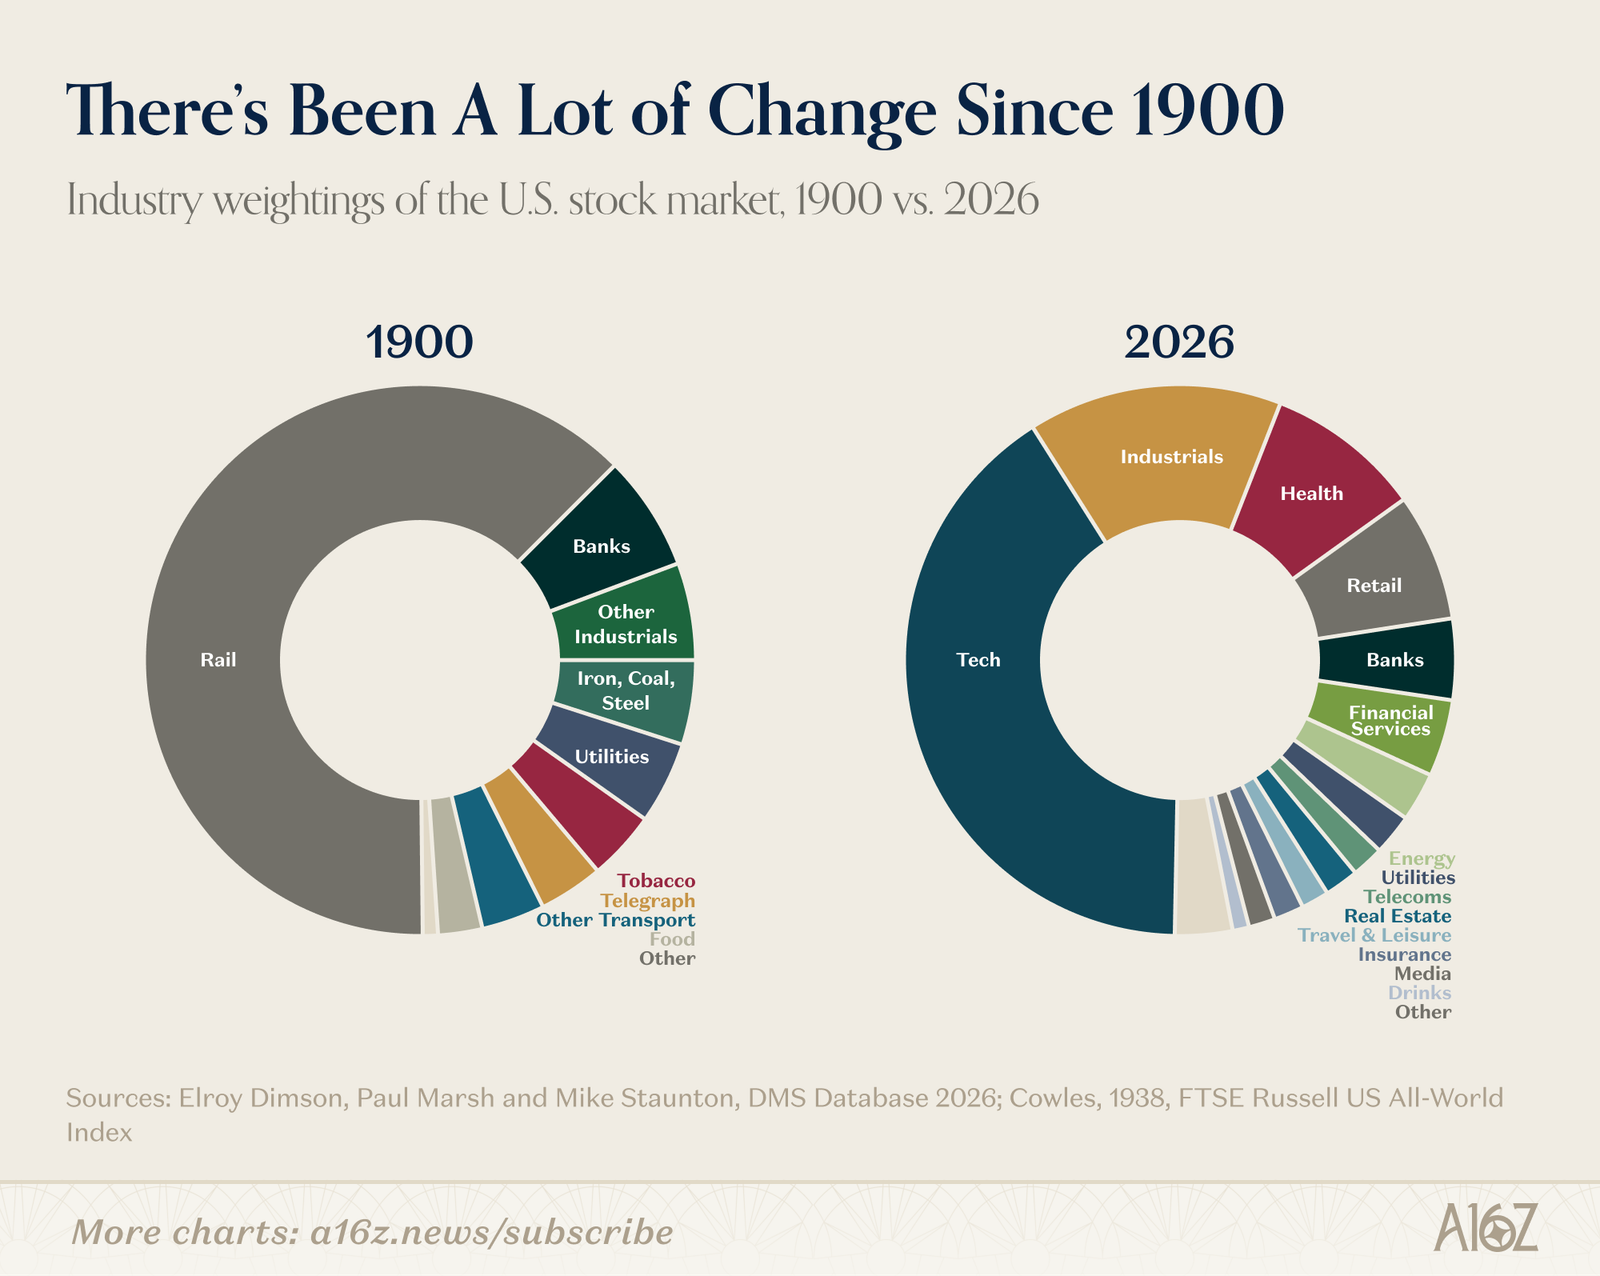
    Here are some interesting charts from a16z showing that, despite its dominance today, tech still represents a smaller percentage of the US stock market than railroads did at the turn of the 20th century. One parallel you could draw from this is that “tech” as we know it today, may not be so dominant a hundred years from now.

    But railroads continue to play a critical function in the modern economy. They are still the most cost-effective way to move heavy goods over long distances. A single freight train can carry the load of several hundred semi-trucks.

    The more interesting parallel might be the one that a16z raises in its post: railroads both led to further economic growth and rewired the way businesses and organizations were structured.

    Railroads were a new kind of business requiring massive scale and coordination, which led to new ways of thinking about “management.” Perhaps not surprisingly, it was around this time (1881) that the world’s first collegiate business school was formed at the University of Pennsylvania.

    The parallel to AI today, as argued by Jack Dorsey and maybe others, is that it’s going to similarly rewire how businesses are organized and what middle management does:

    > “Instead of absorb and route information, maintain alignment, pre-compute decisions, etc.—the kind of coordination that management typically is responsible for—in an AI business, humans move to the edges, to focus their judgment on customer contact and human interactions.”

    At least, this is the hypothesis.

    But if it does prove to be true, let’s consider what we often discuss on this blog, which is: what will it mean for our cities and built environment? Well, what I find interesting about the above quote is that it suggests AI will push humans further toward the things that we are uniquely suited to do: interacting with other humans and building meaningful relationships.

    And if that is, in fact, what happens, then there’s no more efficient place to be than in dense urban cities. Looking someone in the eyes, shaking their hand, and slurping ramen noodles together at a busy bar counter is not something that AI will be able to do for us.


    Cover photo by Mike Beaumont on Unsplash

    Charts from a16z

  • Default to yes

    April 25, 2026 · View original


    Fast, high-quality decisions and approvals are the lifeblood of organizations. And if you’ve ever worked in development or construction, you know that there are a lot of decisions and approvals — some small, some big — but all of which can delay and hurt a project. Ultimately, the objective is to achieve both high-quality and high-velocity decisions. But how?

    Very broadly speaking, you want a bias toward action and progress. How this plays out might depend on the specific situation at hand, but here’s one technique that we try to use whenever possible. I call it (as of 30 seconds ago) the “default-to-yes” principle. It works well for approvals and reviews, and it is very common in construction.

    All you need are two things: (1) a date by which something needs to be reviewed or approved and (2) a default yes. A default yes means that if I don’t hear from you by the deadline established by (1), I’m simply going to assume your answer is yes and move on. Consent is implied unless you object.

    The opposite of this is a “default-to-no” approach, which means things get stuck until someone gets around to reviewing or approving the thing. That’s far less optimal because there’s no outer limit to how long something might take. With the default-to-yes approach, I know progress will happen no later than X days from now.

    This is just one specific technique, and I’m not suggesting it will work for all decisions and approvals, but there’s significant value in high velocity. And to achieve that, you want a deeply ingrained cultural bias toward action.


    Cover photo by Rubén Bagüés on Unsplash

  • The return of hard assets

    April 24, 2026 · View original


    Back in 2011, Marc Andreessen wrote a widely cited blog post where he argued that “software is eating the world.” In some ways, it feels like just yesterday that I first read it. But it has been 15 years, and boy, has the world changed. Now, the worry is that AI is eating software.

    It has become significantly easier to write code, to the point that in the span of only two years, Google has gone from 0% of its new code being written by AI to now over 75% of it! But it’s not just big companies. I know lots of non-technical people who wanted software that could do “X,” and so they just vibe coded a solution. Done.

    In fact, I’ve been experimenting and doing the same for several months now. It has become so easy that I feel an obligation to do it. But as we know, if everyone can do it, then it means there is no longer any value. The value will necessarily need to be created in other ways.

    Earlier this week, we spoke about Uber and how being asset light — previously a hallmark of the gig economy — is potentially now a liability. Well, this is a broader theme. Josh Brown, CEO of Ritholtz Wealth Management, even coined a term for this: HALO. This stands for Heavy Assets, Low Obsolescence.

    The general idea is that you now want physical stuff with a big moat that is immune to being disrupted by someone in their parents’ basement using Claude Code. Hard assets are, arguably, where you want to be today. I guess that means real estate is back, baby!


    Cover photo by Tim Mossholder on Unsplash

  • Designing for the jobs to be done

    April 23, 2026 · View original


    I was on a panel this week, put on by BILD, called “Design That Sells.” The focus of the panel was on how innovative product design can help sell homes in the current market environment. When I was first asked to be on the panel, I thought to myself, “I’m not sure I’m qualified to talk about this right now. Market conditions, rather than design, are the challenge!”

    Of course, focusing on your customers’ needs, solving their problems, and innovating with great design is always going to be the way. I think we’ve consistently tried to do this with our projects, and so that’s what I talked about.

    But what the discussion also got me thinking about — though I didn’t mention this during the panel — is the late Clayton Christensen’s theory called “Jobs to Be Done.” I’ve written about this before on the blog, specifically about his milkshake case study.

    The key idea behind the theory is that customers “hire” products and services in order to complete specific “jobs” for them. The problem is, businesses sometimes don’t actually know the job that people are hiring for! In the case of the milkshake case study, this ended up being the job:

    > “Most of them, it turned out, bought [the milkshake] to do a similar job,” he writes. “They faced a long, boring commute and needed something to keep that extra hand busy and to make the commute more interesting. They weren’t yet hungry, but knew that they’d be hungry by 10 a.m.; they wanted to consume something now that would stave off hunger until noon. And they faced constraints: They were in a hurry, they were wearing work clothes, and they had (at most) one free hand.”

    This is why people were buying milkshakes in the morning, and why their efforts to sell more later in the day were not working. Now, let’s talk about a case study that is closer to home. If you visit the Christensen Institute’s site, you’ll find a case study of his theory from the condominium industry.

    The objective was for a Detroit-area developer to sell more homes targeted toward retirees and divorcees. They priced accordingly, had all the luxury finishes, and spent on elaborate marketing, and yet their inventory wasn’t moving. Was it a design problem? A pricing issue?

    Nope:

    > So, Moesta took a Jobs to Be Done approach: He set out to learn from the people who had bought units what job they were hiring the condominiums to do, and the conversations revealed an unusual clue: the dining room table. Prospective customers repeatedly told the company they didn’t need a formal dining room. And yet, in Moesta’s conversations with actual buyers, the dining room table came up repeatedly. “People kept saying, ‘As soon as I figured out what to do with my dining room table, then I was free to move,’” says Moesta. The table represented family.  > > What was stopping buyers from making the decision to move, he hypothesized, was not a feature that the construction company had failed to offer, but rather, the anxiety that came with giving up something that had profound meaning. “I went in thinking they were in the business of new-home construction,” Moesta recalls. “But I realized they were in the business of moving lives.”

    To solve this problem, the company offered moving services, two years of free storage, and a “sorting room” in the condominium where new owners could dump their stuff and then take their time deciding what to keep and what to discard. And it worked. Brilliant.

    Once you understand the actual barriers and “jobs to be done,” you can solve for them. Sometimes it might be a design problem, but it could be something totally unexpected. Regardless, the solution lies in caring about and understanding your customers. This is true in all market conditions.

  • When asset light becomes an asset liability

    April 22, 2026 · View original


    One of the great features of the so-called gig economy is that many of its businesses operate with an asset-light model. Uber, for instance, relies on drivers showing up with their own cars. This is the opposite of, say, the real estate industry, which, for a lot of business models, is both capital-intensive and asset-heavy.

    But there is one problem with the asset-light model, and it’s that it may not work forever. The Financial Times just reported that Uber has committed to spending $10 billion over the next few years on actual cars and on equity investments in various strategic companies.

    For instance, earlier this month, electric vehicle company Lucid announced that Uber will be investing $500 million in the company and buying at least 35,000 of its cars.

    This is gig-economy blasphemy, but it’s very obviously an existential concern for the company. Uber needs to be in the AV race, or else asset-light could be an asset-liability. The thing that helped Uber become successful in the past now seems to be what they need to overcome in this new mobility race.

    On a loosely related note, I find it somewhat amusing that cities are now starting to push back against robotaxis out of fear that they will displace Uber drivers. If you were following Uber in its early days, you’ll know that cities fought the company vehemently because of the taxi lobby. Now they’re trying to protect it.


    Cover photo by Erik Mclean on Unsplash

  • The market logic of Japanese rail

    April 21, 2026 · View original


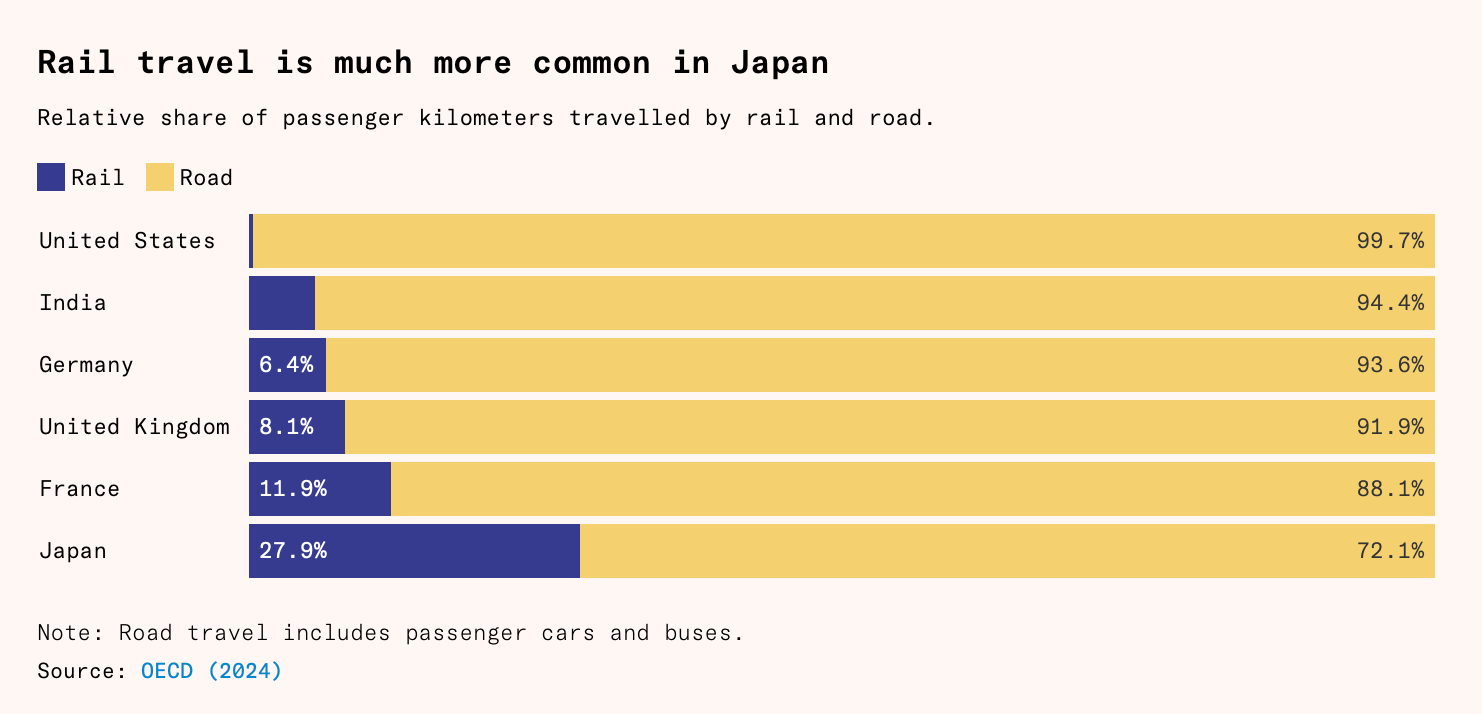
    We have spoken many times before about the fact that Japan is built around rail-oriented urbanism. But if you have the time right now, I’m going to suggest that you read this longish article by Matthew Bornholt & Benedict Springbett called “Why Japan has such good railways,” because nowhere else in the developed world uses rail for passenger kilometres more than Japan, and they explain why.

    One common hypothesis, which is mentioned in the article, is that it’s largely cultural. The Japanese are rule-abiding collectivists who are more willing to take public transit compared to us selfish and individualistic North Americans. But this doesn’t seem right. In fact, one could argue that the Japanese solution is actually more free-market oriented.

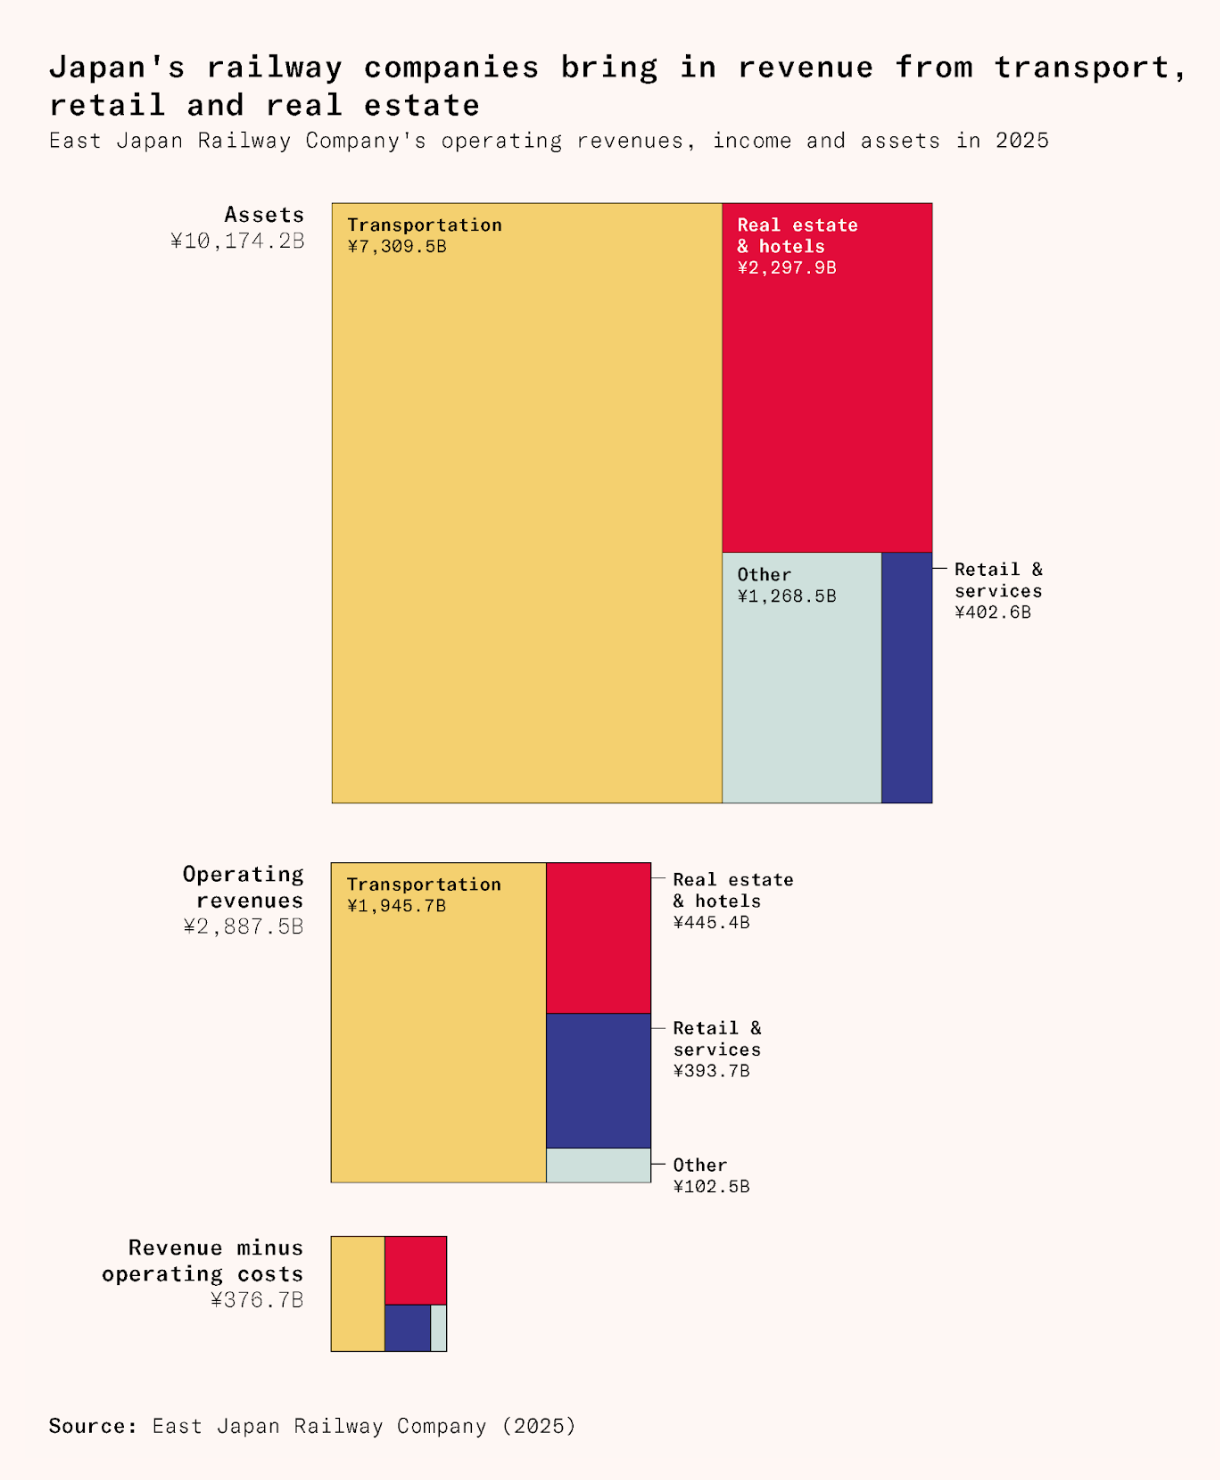
    The Japanese rail model seems to work so well because (1) most of the network is private, (2) liberal land-use policies have allowed Japan’s urban centres to develop enough density to properly support the use of rail, and (3) the rail operators make money in a bunch of other ways beyond rail. They’re typically also in the business of real estate.

    Here’s a quote from the article by the president of the Tokyu Group that I absolutely love:

    > I think that though we are a railway company, we consider ourselves a city-shaping company. In Europe for instance, railway companies simply connect cities through their terminals. That is a pretty normal way of operating in this industry, whereas what we do is completely different: we create cities and then, as a utility facility, we add the stations and the railways to connect them one with another.

    This is a fundamentally different model that allows rail companies to capture some of the value that they inherently create. To use the example of Toronto’s Eglinton Crosstown line, it’s the difference between saying, “I’m going to build a rail line and then, presumably, other stuff will happen,” and, “I’m going to develop this midtown corridor and then I’m going to run rail underneath it to maximize value creation.”

    If Japan can do it, so can we. Ironically, a big part of it means easing land-use controls and allowing transit-oriented development to simply be what it wants to be — dense and proximate to rail.


    Cover photo by Mylène Larnaud on Unsplash

    Charts from Work in Progress

  • Information wants to be free

    April 20, 2026 · View original


    I recently came across a real estate product called LandGlide. It’s an app that provides parcel boundaries and detailed property information for over 99% of the US population. It’s also “available” in Canada, but it doesn’t tell you much about properties here. In the US, you can easily access things like:

    – Owner’s name or legal entity – Mortgage balance and terms – Assessed value and tax amounts – Square footage and year built – Granular details (even down to whether the home has a fireplace)

    The reason for this difference is that in the US, property data is generally considered public record, whereas in Canada, we have stricter privacy laws. But it’s not like we make this information strictly private. We just gate it and make it more cumbersome and costly to obtain through services like GeoWarehouse.

    I know that some of you will argue that it’s better to “sort-of-kind-of” restrict this data from being freely displayed online. But hear me out: this philosophical data difference is an important one that hurts innovation.

    In Canada, property data is monopolized and, therefore, cumbersome and expensive to access. It’s an unnecessary barrier to innovation. In the US, the same kind of data has become commoditized. It’s easy and cheap to access, and so the barriers to building new ideas on top of it are significantly lower.

    For example, Paul Crowe, who is the CEO of a Toronto-based real estate company called House Beat, responded to one of my tweets by saying, “For what I can get in the US for $0.15 / API call from one provider, [it] would cost over $18 per call in Canada, across 2-3 integrations.”

    What this suggests to me is that we’re okay allowing some/all of this data to get out there; we’d just like it to be harder and more expensive to access. Why?

    Information, as the saying goes, wants to be free, which is why I’m so bullish on blockchain technologies. Blockchains are public databases that make information widely accessible and allow anyone to innovate on top of them. As the world continues to move on-chain, we are going to see the enormous benefits that this brings.

    Already, we can see what happens when you don’t have or allow it.


    Cover photo by Jakub Żerdzicki on Unsplash

  • Competing against the market

    April 19, 2026 · View original


    I just saw The Real Estate God argue the following (on Twitter): “What people don’t understand about the S&P is that every single person in the country who has money is also invested in it. When your money goes up 15%, so does everyone else’s. You gained zero relative wealth. You need to outperform the S&P if you want to actually get ahead.” The implication of this is that when you then go out and compete for a “fixed pool of high-quality assets” — such as a home — you have no comparative advantage against everyone else.

    Yes, and no.

    I think this tweet is true in a narrower, segmented sense. One of my personal life philosophies is that it’s important to do things that others can’t or aren’t willing to do. It’s important to be disciplined, make sacrifices, and put in the work; otherwise, you revert to the mean. You have to be different! It’s one of the reasons that I’ve maintained a daily blog for nearly 13 years. I enjoy it and there are benefits to doing so, but it’s also painfully difficult and not something most people care to do (perhaps rightly).

    Small improvements and outperformance can also make a huge difference when looking at a long enough time horizon. Consider this simple table showing a starting balance of $100k and annual returns ranging from 10% to 15% per annum.

    If 10% represents the expected return of “the market,” look at how much of a difference even one percentage point (increase to 11%) can make. Over a 30-year period, it’s more than half a million dollars. And between 14% and 15%, the delta is over $1.5 million! The simple and commonly discussed lesson here is that small incremental improvements compound and can make all the difference when applied with consistency and discipline.

    But to find alpha in this way (outperformance), you arrive at a subset of “being different.” To outperform the market, you generally need to be right about something that most people think is incorrect. Because if everyone believes something to be true, it’s not being any different; it’s just “the market” and there’s no alpha in that.

    So in this sense, if you want a high degree of relative wealth creation, if you want to retire early with a yacht in Monaco, and you don’t want to wait for the decades of compounding to start delivering the bulk of its fruit, then yes, you will likely need to look beyond just the S&P and take on additional risk to get there.

    This is the “yes” part. Now let’s consider the “no.”

    It is estimated that about 40% of Americans have no exposure to the stock market, that the wealthiest 10% own roughly 93% of all outstanding stock shares, and that the wealthiest 1% own about 50% of the market. Canada exhibits a similar story of high concentration, although it’s less extreme, and Canadians tend to be more invested in residential real estate compared to stocks and business equity.

    Regardless, there is a question of allocation. When the market goes up 15%, it doesn’t affect everyone equally, and it actually increases overall inequality given the above concentrations. Though if you’re competing for a €6M apartment in Paris, you are admittedly competing within your narrow socio-economic band against people who probably have exposure to equity markets.

    There’s also a behavior gap. If you buy the S&P 500 and hold it for 30 years, you would be an extreme statistical outlier. Most people don’t do this. They get emotional, they sell when it falls, and they try to time the market. Here, for example, is a study that found that in 2024 the average equity investor earned 16.54%, compared to the S&P 500’s 24.02%.

    > Despite strong performance in the equity markets, investors continued to underperform due to their behavior. Withdrawals from equity funds occurred in every quarter of 2024, with the largest outflows taking place just before a major return surge.

    So even if you are just buying the S&P 500, there are still ways to be different and achieve relative outperformance. You just have to be patient and have the right temperament.

    That said, even if you were extremely disciplined and you behaved for, say, 30 years, it would still be mathematically impossible to achieve something like Elon Musk-level wealth. You could be a multimillionaire with Monaco yacht level wealth, but not a centibillionaire. For that, you’ll need to actively take on more risk and, yes, outperform the market.


    Cover photo by Sean Pollock on Unsplash

  • What are your luxury criteria?

    April 18, 2026 · View original


    I recently watched a few episodes of L’Agence on Netflix. I don’t watch much TV, but it is somewhat shocking that I haven’t gotten more into this show before. It’s about beautiful real estate and all things French, which are unapologetically two of my favourite things.

    Another great feature of the show is that everyone seems to be in their late 30s and shopping for a €6,000,000 apartment with a rooftop terrace and views of the Eiffel Tower. It’s a great way to start questioning all of your life decisions.

    In fairness, the buyers are varied, but I do find it interesting that there are some recurring purchase criteria. Many of them want something “central.” Many of them have kids and have no hesitation about raising them in an apartment. And many of them have a non-negotiable desire to be able to walk out their door to amenities without having to drive.

    All of this really resonates with me, but it obviously isn’t true for everyone or for all geographies. “Luxury,” which is the focus of this show, means different things to different people. What are your criteria?


    Cover photo by Alexander Kagan on Unsplash