Daily insights for city builders, delivered every morning at 6 AM ET. I’m Brandon Donnelly — a Toronto-based real estate developer and founder of Globizen. I’ve been writing here since 2013.

Tag: startups

  • Why I write about tech on my city building blog

    I had a friend ask me this week about how I decide what to write on this blog. His comment was that I tend to write about a variety of different topics. He wondered: Isn’t it better to focus on one particular niche?

    The simple answer is that I write about what interests me. And secondary to that is any concern around what will get the most clicks. In fact, I try not to fall into the trap of worrying about the latter. Sometimes it can be paralyzing to fixate on what will appeal most to the tens of thousands of people who read this blog on a regular basis.

    The reality is that my interests are much broader than, say, just design and real estate; though these two topics are clearly central. 

    I learned a long time ago while studying architecture and art history that what we make as a society is generally a product of the cultural milieu at the time. In other words, the built environment doesn’t happen in a vacuum. It is the physical manifestation of what we believe to be true at a particular moment.

    Today, it’s pretty hard to ignore the importance of tech. Think of some of the most valuable companies in the world right now: Apple, Google, Amazon, Facebook, and so on. Now, technology has always shaped our cities, but what makes this moment different is the decisive shift toward software.

    It’s arguably no longer about who can build the best mousetrap. It’s about who can build the best software layer on top of that mousetrap.

    In 2011, venture capitalist Marc Andreessen (previously the co-founder of Netscape) published a widely shared essay called, “Why Software Is Eating the World.” And over the past 6 years he has been proven to be very right.

    The 3 main points he aimed to make with that essay are as follows:

    1. Every product or service that can become software will become software.
    2. Every company will have to become a software company.
    3. The winning companies will be the best software companies.

    Depending on your industry, this may sound ludicrous to you. Certainly in 2011 it probably seemed that way. 

    But a perfect example of this phenomenon is the iPhone. The phone itself is manufactured in China, albeit where a lot of great hardware innovation is taking place. 

    But at this point, phones have become fairly commoditized. The profits that Apple makes from the iPhone disproportionately come from the software layer and the app ecosystem it has developed.

    You could make a similar argument with Tesla. Autonomous navigation – which most of us can agree will have a profound impact on cities – is largely a software challenge. 

    And so if you believe that autonomous vehicles will be a fundamental part of the future of mobility, then it’s not that hard to believe in point number three: the winning car company will also have to be the best car software company.

    Some industries have been less touched by tech and software – real estate being one of them. But if Andreessen is right and it’s not a question of if, but a question of when, then it behooves all of us to think about the potential impacts.

    I love how Andreessen ends this podcast discussion with Barry Ritholtz of Bloomberg and so I’m going to repeat it here to close out this post. He says: “There are no bad ideas. There are only early ideas.” 

    And that’s why I write about tech on my city building blog.

    Photo by Michal Pechardo on Unsplash
  • Power to the people

    Bloomberg columnist Barry Ritholtz recently interviewed Richard Barton about his startup companies. Barton founded Expedia while he was an executive at Microsoft (Gates and Ballmer era) and then went on to cofound Zillow (real estate site) and Glassdoor (jobs site). 

    I’ve been following the work of Barton for many years now because I admire the common thread among his startups: They’re about bringing transparency to industries where transparency is lacking. I used to try and dissect his thinking when I was working on my own real estate/tech startup.

    I believe there’s still a lot of room for transparency in the real estate space, but that doesn’t negate the work that Barton has done. He’s all about using technology to bring “power to the people.” That’s a good thing.

    Click here to listen to the podcast.

  • Contentment as vice

    “Contentment used to be a virtue. Now it’s a vice.”

    I came across this line on Brad Feld’s blog

    For those of you who aren’t familiar with Brad, he is a successful entrepreneur and early stage VC investor. He cofounded the Foundry Group, Mobius Venture Capital, Intensity Ventures and Techstars, and sold his first company back in 1993. 

    But Brad has also struggled with depression over the years and so you’ll find that a number of his blog posts are also quite contemplative.

    This particular post – where the above line comes from – is about a societal norm that I am sure many of you can relate to. I know I can. Here’s another snippet from the post:

    “We talked for a few minutes about the overall, dominant American culture of achievement. The endless striving. The need to feel busy, important, and successful. The deep cultural norms around ambition.”

    Whether it’s because we’re all deeply insecure or because we just need to fulfill our egos, this has become our modus operandi. It has become all about “the hustle” and about “crushing it 24/7.”

    Just this evening I was at a friend’s birthday party and I couldn’t tell you how many times I said “busy.”

    “Hey Brandon, how are things?”

    “Busy!”

    This is an absolutely terrible response. I know that. And I’ve started introducing other responses into my small talk repertoire. But busy is so ingrained in our culture. Being busy makes us feel important. It means we are in demand. We do things. We create value.

    But is the reverse – not being busy – now a vice?

    Regardless of your position on the appropriate balance between contentment (being ok with what you’ve got) and work (striving for more than what you’ve got), I think the first line of this post is an incredibly poignant commentary on the life that many of us live today.

  • From self-storage to urban logistics

    image

    I have long told myself that if I ever needed to rent self-storage space, it would mean that I own too much stuff and that I need to get rid of some of my shit. But I recognize that there are many reasons why someone might need extra storage and I recognize that the storage market in the United States alone is something to the tune of $30 billion a year.

    Here is an interesting case study about the storage company MakeSpace, which to-date has raised almost $60 million in equity funding. Their model is likely one that you’ve heard of or used before. Instead of you yourself going to the “self-storage” facility, they do the pickup and delivery. So they call themselves a logistics business, like Amazon, except that it works in reverse. Instead of you receiving deliveries, they take your stuff from your home back out to their warehouses.

    Because of the route management software that they’ve been building over the last 4.5 years and because there’s enough density in the areas that they service, their pick-up and drop-off routes are apparently profitable. You no doubt need a certain amount of scale for that to happen, but they seem to have it. By the end of this year, they expect their reoccurring revenues to be in the $10′s of millions. That’s coming from the volumes of green boxes you see at the top of this post.

    What’s particularly relevant for this audience are the built form and real estate implications. Because their customers aren’t physically visiting their facilities, they’ve been able to locate all of their distribution centers on the outskirts of the cities in which they operate. And because of this, their physical real estate costs are said to be less than 50% of traditional self-storage firms and they believe this number will trend to around 20% as volumes continue to grow.

    All of this has me thinking about some of the other implications of the on-demand economy on cities and on real estate.

    Image via Both Sides of the Table

  • Should Uber be shut down?

    image

    Last week Travis Kalanick – the cofounder who built Uber into the most highly valued privately held startup in the world – stepped down as chief executive at the request of his investors. This was the culmination of months of controversy related to the company’s toxic corporate culture.

    So what’s next? 

    Benjamin Edelman, associate professor at Harvard Business School, recently argued that this is it for the company: Uber Can’t be Fixed – It’s Time for Regulators to Shut It Down. I discovered the article through a good friend of mine who has felt similarly since the beginning. Uber’s business model is predicated on illegality and that should not be misconstrued as “innovation”.

    I have a few thoughts on this.

    But let me start by saying that this post is not a comment on the company’s corporate culture or its internal practices related to lobbying governments. I have not really been following what’s going on internally and I’ll leave other, more informed, people to comment on those matters.

    With that said, here are 3 thoughts.

    One, shutting down the company feels like an extreme case of throwing out the baby with the bathwater. Lots of companies go through restructuring, assuming that’s needed, without completely capitulating.

    Two, before Uber came along it was still challenging to pay for a taxi in Toronto with a credit card. More often than not the driver would tell you that the machine was broken or ask that you instead pay with cash. At that point, I would have accepted a clunky payment machine mounted to the rear of the front seats as an innovation.

    To say that Uber’s technological innovations were all banal things that its competitors were already about to introduce is downplaying so much of what the company has done outside of its beneficial cost structure. 

    We got perfect information: Where is my car right now? We got full pricing transparency before even accepting a ride: Should I take an Uber or transit or should I drive? We got the ability to get in and out of a taxi without pulling out our wallets: I’ll quickly jump out at this red light. We got dynamic ride pooling and cost sharing: Let’s split this ride 3 ways to bring the fare down. And we got clean cars that didn’t smell.

    Why weren’t any of the incumbent taxi companies do this?

    Three, I fully agree that Uber (unfairly?) benefited from a meaningful cost advantage by operating in the unregulated side of the market. This was a huge boon for the company because, as the data suggests, the demand for taxis is highly elastic.

    But I also believe that the incumbent taxi companies were perpetuating a marketplace that was anything but free enterprise. It ensured that the status quo was maintained and that those who historically benefited from the system continued to benefit from the system.

    Because of this, I’m not sure that we would have seen the innovation that we saw without a company like Uber deciding to operate within a gray area and not ask for permission. Protectionism may have stomped it out. This may be why Hailo – which operated in the regulated side of the taxi marketplace here in Toronto – ultimately wasn’t able to survive.

    Though I suppose you could argue that Hailo’s failure (at least here in Toronto) strengthens the argument that Uber was only able to thrive because of its illegal cost structure. 

    However, it’s important to remember that Uber got its start by actually charging more than traditional taxis. At the outset it didn’t have enough liquidity in its marketplace to compete based on speed and/or price, and so it decided to offer a premium experience. 

    UberX didn’t introduce steep discounts until later on and even today many people will gladly accept surge pricing at multiples of a regular taxi fare. Clearly customers are deriving some other benefits from the app.

    Edelman ends his piece by referencing Napster as an example of another startup that defied legality and was ultimately forced to shut down. Again, shutting Uber down seems extreme to me, but I do agree with his conclusion. Regardless of what happens, the lawful innovations that Uber introduced are here to stay.

    Photo by Carl Joseph on Unsplash

  • The geography of superstars

    We often talk about superstar cities such as New York, London and, in the case of tech, San Francisco. But what about the superstar people that drive these economies?

    Aaron Renn recently wrote a post called “The Superstar Gap”, where he argues that the interior of the U.S. is suffering from a big handicap because of its lack of superstars. Chicago is one example he gives. Very good, but not the best.

    He also cites a 2010 analysis by Carl Wohlt that shows the “100 Most Creative People in Business” predominately living in the West and Northeast, compared to the Midwest and South.

    This is interesting because – if we assume this gap to be true – it gets me thinking about a number of important questions:

    • Is it that the interior isn’t effectively fostering superstar talent?
    • How much superstar talent is actually latent and untapped?
    • Is it that superstar talent is getting sucked into a select few superstar cities, away from other places? Definitely happening.
    • How many superstar cities (filled with superstar people) can sustainably exist in today’s world?

    Now by definition, superstar talent is going to be a smaller segment of the population – it’s one tail of the bell curve. 

    But I do think we should be careful not to assume that the raw talent doesn’t exist in certain cities. People and place are linked, and superstar cities are arguably just empowering new forms of individual superstardom.

    If we are to use successful startups as one measure of superstardom, it’s important to keep in mind that they are incredibly fragile in their nascent stages. The right people need to come together. The right funding has to fall into place. And the list goes on. 

    Below is an excerpt from a 2006 essay by Paul Graham (Y Combinator) called, Want to start a startup?

    Successful startups are almost never started by one person. Usually they begin with a conversation in which someone mentions that something would be a good idea for a company, and his friend says, “Yeah, that is a good idea, let’s try it.” If you’re missing that second person who says “let’s try it,” the startup never happens.

    That someone might have been a superstar.

  • Internet Trends 2017

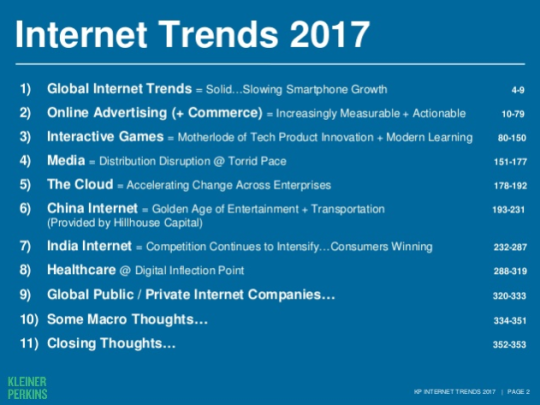
    Mary Meeker – who is a partner in the VC firm Kleiner Perkins – just recently released her annual Internet Trends report. 

    I’ve pasted the table of contents above so you can quickly decide if you’d like to spend your time going through it. The entire report is over 350 slides.

    If you can’t see the embedded slideshow below or if you’d like to access the reports from previous years, click here.

    [slideshare id=KGiWuuYFlhbQBC&w=595&h=485&fb=0&mw=0&mh=0&style=border:1px solid #CCC; border-width:1px; margin-bottom:5px; max-width: 100%;&sc=no]

  • Retail tipping point

    Venture capitalist Benedict Evans recently published a post on his blog called, Ten Year Futures. If you haven’t already noticed, I really enjoy this sort of curiosity and line of thinking. Here is an excerpt where he talks about retail being at a tipping point:

    “First, ecommerce, having grown more or less in a straight line for the past twenty years, is starting to reach the point that broad classes of retailer have real trouble. It’s useful to compare physical retail with newspapers, which face many of the same problems: a fixed cost base with falling revenues, the near-disappearance of a physical distribution advantage, and above all, unbundling and disaggregation. Everything bad that the internet did to media is probably going to happen to retailers. The tipping point might now be approaching, particularly in the US, where the situation is worsened by the fact that there is far more retail square footage per capita than in any other developed market. And when the store closes and you turn to shopping online (or are simply forced to, if enough physical retail goes away), you don’t buy all the same things, any more than you read all the same things when you took your media consumption online. When we went from a corner store to a department store, and then from a department store to big box retail, we didn’t all buy exactly the same things but in different places – we bought different things. If you go from buying soap powder in Wal-Mart based on brand and eye-level placement to telling Alexa ‘I need more soap’, some of your buying will look different.”

    I’ve said this many times before, but the way the above excerpt ends is yet another remind that one has to look deeper beyond the obvious change(s). Yes, ecommerce is growing and impacting physical retail. But what other changes might ensue because of this shift?

  • Big bad (software) developers

    “There is no higher God in Silicon Valley than growth. No sacrifice too big for its craving altar. As long as you keep your curve exponential, all your sins will be forgotten at the exit.” –David Heinemeier Hansson

    Snap Inc. went public last week. Offering price was $17. Closing price on the first day was $24.48. Given that the company is not profitable and may never be profitable (their caveat, not mine), many people have been asking: Is a valuation somewhere around $34 billion justifiable?

    This is a common question when it comes to tech companies. And the answer usually comes down to something along the lines of this:

    The Snapchat story “is all about growth,” Mr. Nathanson said. “It’s not about economics.”

    It’s about the future.

    I love Snapchat and I think the company is run by a very creative founder. But now that Snapchat Stories was stolen by Instagram, they need, in my humble opinion, something new and killer to stick.

    How else will they meet their growth targets?

    On a related note, I recommend you read a piece by David Heinemeier Hansson called: Exponential growth devours and corrupts. That’s where the quote at the top of this post is from.

    Here is an excerpt:

    What sucker wants to earn $10 million/year at a 52.5% tax rate when you can get away with hundreds of millions in one take at just 15%? Nobody, that’s who.

    It’s hard to argue that boards, founders, and their financiers aren’t just doing exactly what the incentives are coaxing them to do.

    Which is why growth is now everything and residual value is nothing. In fact, the latter can be outright harmful to the former. When you’re being priced on the hopes and dreams of potential, reality can be a dangerous and undesired competitor. Best just to appeal to the exponential curve and let the imagination roam free. An epic capital gains score awaits!

  • People stay the same

    Andrew Chen recently delivered a keynote at StartCon in Australia called: What’s Next in Growth? You can find his entire talk, here, on his blog. 

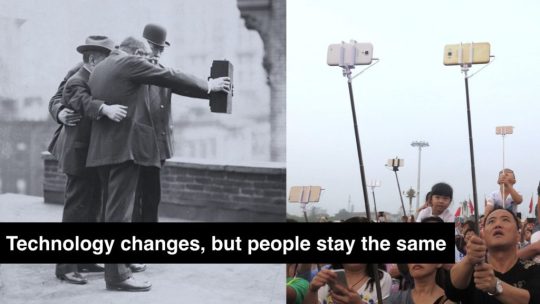
    One of the themes of his talk is that, “technology changes, but people stay the same.” I like that. See above.

    But more specifically, his presentation focuses on 3 techniques for growing businesses and products: customer referrals, viral content, and bootstrapping marketplaces. All of it is interesting, but I’m particularly fascinated by the last one.

    Marketplaces are all around us. Uber is a marketplace that pairs drivers and riders. Bars are a marketplace that try to pair people together. Finding, trading, and transacting (whatever that might mean for the marketplace in question) seems so fundamental to humans. And cities really empower that.

    The challenge with marketplaces is that they’re hard to start. There’s always a chicken-and-egg problem and so one side of the marketplace usually needs to be “hacked” at the beginning.

    Uber is a perfect example of this. At the outset, it didn’t have enough liquidity in its marketplace to compete with incumbent taxis. That is, it took longer to get an Uber than to get a taxi. 

    So instead, the value proposition was not about speed (or cheapness); it was about luxury. Uber was “everyone’s private driver.” That made waiting acceptable. You were getting a different level of service. The first Uber I ever called in Toronto took 20 minutes to get to my place in midtown.

    But obviously as liquidity increased, Uber was able to move downmarket and capture more (most) of the taxi market. Marketplaces are powerful once they get going. Network effects.

    I say all of this because, as many of you know, I have spent a lot of time wondering about the future of real estate marketplaces

    At the same time, I also think that many of these seemingly tech-focused lessons could be applied to cities. Starting an online marketplace is difficult. So is building a new neighborhood from scratch. In the end, it’s always about people.