Daily insights for city builders, delivered every morning at 6 AM ET. I’m Brandon Donnelly — a Toronto-based real estate developer and founder of Globizen. I’ve been writing here since 2013.

Tag: real estate

  • The importance of having your own beliefs

    On Monday I watched the movie Moneyball for the first time. I really enjoy movies, but I unfortunately don’t watch a lot of them, which is why I am only now watching Moneyball. It was released in 2011.

    The movie is based on a 2003 book of the same name that many people believe changed the game of baseball. It emphasizes rigorous statistical analysis (known as sabermetrics) over gut feeling, instinct, and traditional metrics when it comes to assembling winning baseball teams.

    I don’t know a lot about sabermetrics, but I am now excited to read the book. Still, the dichotomy between the New York Yankees and the Oakland Athletics is incredibly interesting to me. And it reminded me of a post I wrote a few months ago ago called: When everyone thinks you’re wrong.

    In the movie, Billy Beane, the GM of the Athletics, realizes that he cannot compete with the Yankees dollar for dollar. The Athletics are a small market team and the Yankees, with their large payroll, will always be able to pay more for players. So he decides that he will need to think about the problem differently to win.

    What’s interesting about this is that it’s exactly the framework I talk about in my post when it comes to buying (real estate) development sites:

    “…you can really only win development sites in one of two ways. Either you’re willing to spend the most money or you see something and have a vision that nobody else sees.”

    Of course, lots of baseball teams today are now employing sabermetrics. But at the time, everyone thought Billy Beane was nuts. It’s hard to try something new and be different. Many of us just want to do what is least likely to fail.

    But there’s so much value in having conviction and being right about something that everyone else thinks is wrong. You won’t always get it right. And that’s okay. But when you do get it right, it’ll be magic.

  • The Starbucks Effect

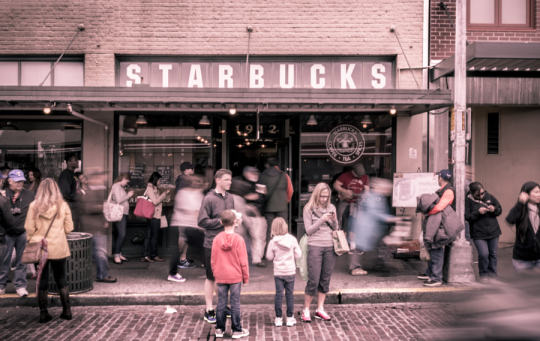
    The Original Starbucks in Motion by Brad Telker on 500px.com

    https://500px.com/embed.js

    This afternoon I was chatting with some friends about Toronto real estate (which is something that happens a lot in this city), and we started talking about “The Starbucks Effect.”

    Basically, we were talking about how this neighborhood just got a Starbucks and how that neighborhood already has one. We were, like a lot of people, using Starbucks as a proxy for neighborhoods that are emerging and neighborhoods that have already arrived.

    There’s been a lot of discussion about the correlation between home prices and the presence of a Starbucks. But the big question is what comes first: the home prices or the Starbucks?

    Earlier this year, the CEO, Spencer Rascoff, and Chief Economist, Stan Humphries, of Zillow.com argued that the mere presence of a Starbucks can cause gentrification. 

    They argued that Starbucks knows the next hot neighborhood before anyone else does and that they are “the fuel, not the follower.” And through their data they demonstrated that homes (in the US) near a Starbucks appreciated significantly faster than homes not near a Starbucks, or even homes near other coffee shops such as Dunkin’ Donuts.

    But I – as well as others – wonder if this isn’t an oversimplification.

    I certainly believe that Starbucks could help fuel home prices in a neighborhood. I think it gives people a comfort level that the neighborhood has arrived and that there are people in the area who are willing and able to spend money on discretionary items.

    But I suspect that for Starbucks it’s a balancing act. They would never want to be late to an emerging neighborhood (and miss that prime corner property), but they also don’t want to be in the business of placing bets on neighborhoods with very few vital signs.

    So I think it’s both. I think Starbucks is analyzing the data and watching home prices like a hawk (the follow) and when it reaches a certain point, they move. And that likely causes a further acceleration of neighborhood change (the fuel).

    What do you think? I would love to learn more about their site selection process.

  • Japan’s disposable housing

    緑 by Austin  Hou on 500px.com

    https://500px.com/embed.js

    As further evidence that real estate is a local business, let’s take a look at the housing market in Japan today. It’s a very unique market.

    According to this Freakonomics podcast, 50% of all single family houses in Japan are demolished by the time they reach 38 years old. That’s their half-life. By contrast, in the US, this number is 100 years.

    The reason for this is rapid depreciation. Real property typically consists of two things: land and the building. Land doesn’t depreciate. But the structure sitting on the land does.

    In Japan, the building or structure is thought to be fully depreciated (and therefore worth nothing) after about 30 years for a single-family home and after about 40 years for an apartment/condominium.

    The result is that there’s virtually no resale housing market. When somebody buys a house, it is usually torn down and completely rebuilt. It’s a uniquely Japanese phenomenon.

    So why does this happen?

    The Freakonomics podcast presents a couple of hypothesis. Some believe that it’s caused by a Japanese fixation with newness. New is seen as pure and clean. 

    Others believe that it has to do with a building code that is constantly changing due to the high frequency of earthquakes in Japan. 20% of the world’s earthquakes with a magnitude of 6.0 or greater happen in Japan. And so there appears to be a belief that newer homes – with the latest seismic technologies – are the safest.

    Whatever the case may be, the fact that there’s virtually no resale housing market in Japan, not surprisingly, produces some interesting outcomes. For one, maintenance and DIY home projects are uncommon. Why invest in your home when it’s not viewed as an asset, but as a disposable good?

    At the same time, people worry very little about marketability when they are building new. And this is a big reason why Japan is so famous for its radically designed homes. When you’re building only for yourself, you just do what you want.

    But most importantly, some (such as Richard Koo, who is interviewed in the podcast) believe that this approach to housing is a huge “obstacle to affluence.” Without a functioning resale market, the Japanese don’t get the opportunity to build wealth/equity in the same way that other countries do.

    Do you buy that?

  • Interview with Brad Keast of Osmington

    image

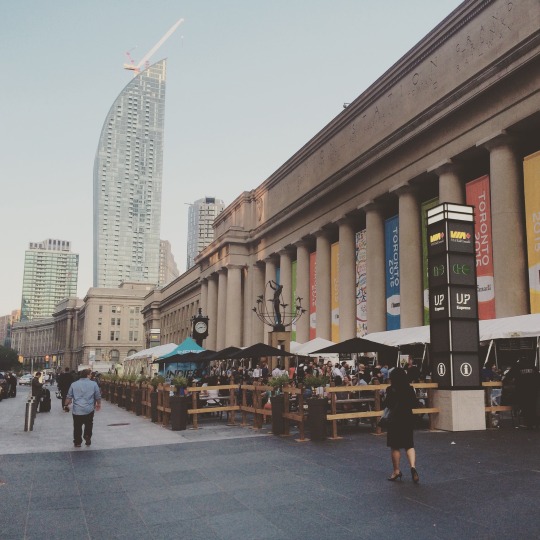
    Given yesterday’s post about Times Square in New York, the timing is perfect to talk about the revitalization of Union Station here in Toronto, its new public spaces, and the programming that’s now happening in and around the station.

    Perhaps the most noticeable is something called Front Street Foods @ Union Summer, which is an outdoor food market set up along Front Street. It’s on this summer from July 6th to September 27th, 2015. 

    However, Front Street Foods is only one part – the food part – of a larger events and programming strategy known as Union Summer. I recently had a quick chat with Brad Keast of Osmington, who is involved in a lot of what’s happening right now at Union Station.

    I found it interesting to learn about how organic the process was. And I thought you all might find it interesting as well.

    ————————————–

    Tell us a little bit about you and your company’s involvement with Union Station. 

    I’ve been with Osmington for over 4 years now and Union Station is a major focus of my waking life. 

    The company won a public RFP with the City of Toronto in 2009 to be the City’s retail partner in the redevelopment. What this means is that while the City owns the building and is doing base building construction, we are overseeing all the retail, advertising, and special events and programming. We are finding all the tenants, doing a bit of overshell work and then turning it over for fit-up.  

    We think the real special part of the project comes in through the special events and programming. We really want to make the station a destination in itself and you’re starting to see that with some of the programming we’ve done this year, be it a contemporary art event like Villa Toronto or something more community-focused like Union Summer – the current animation of the area in front of the station.

    How did the idea for Union Summer come about? 

    This really was a collaborative internal effort. We started by thinking ‘hey, let’s put a bunch of tables and chairs on the new plaza in front of the station and see what happens.’ Then we added in the idea of food. We knew it had to be accessible but didn’t want traditional food trucks, rather something less mobile but still not permanent. 

    That’s when we reached out to Toronto Market Company and they started rounding up the vendors. Then we layered on entertainment – daily music be it live or DJs, as well as a movie night with the Toronto International Film Festival (TIFF). We even have some kids programming on the weekends. Then we worked with the Farmers’ Market being displaced from Nathan Phillips Square due to Pan Am this year to have them here on Wednesdays.

    What was involved in making Union Summer a reality? What was the biggest surprise and/or hurdle that needed to be overcome? 

    There was a tremendous amount of coordination needed. First we weren’t sure when the construction was even going to be finished, all that was certain was it would be before Pan Am started. 

    Then the infrastructure required for the event itself was an exercise in creativity – power, water, and grey water disposal in particular. There was a lot of meetings with City officials for things like building permits, fire code, council approval to apply for a liquor permit, and health and food safety measures. Operationally things like loading in, coordinating with the installation of the Pan Am banners between the columns, interim furniture when our original order didn’t make it onto a ship in Antwerp, and then the first week was so busy that some vendors started losing staff because they were burnt out. 

    Like all things with this project we have to be mindful that this is an operating train station. In fact it’s the busiest building in the country with over 250,000 people per day passing through so we can’t impede those operations. We’ve done our best and have learned some lessons along the way and the reception has been overwhelming. 

    One of the best things about having that many entrepreneurs in close proximity is that some vendors have been pairing up to try experiments. Frozen custard-stuffed churro?

    Toronto is getting much better at designing and programming its public spaces. Given your experience with Union Summer, is there something the city could and should be doing to encourage more of these kinds of urban activations?

    Well, first of all, our contacts at the City, in particular Denise Gendron and Scott Barrett in Real Estate Services have been incredibly supportive of our efforts and we couldn’t have done it without them. If I could make one recommendation it would be to build in the supportive infrastructure for services. Of course that’s only beneficial if there is someone to take charge of the space and program it appropriately. It’s not a part time job.

    What’s next for Union Station?

    Right now the focus is on getting the first retailers open on GO’s new York Concourse. On the programming side we will host art for Nuit Blanche (October 3rd, 2015). That promises to be exciting. And then opening November 30th, 2015 is the Holiday Market. It was a huge success last year so we’re bringing it back for 3 weeks this time.

  • Fun Friday: ATC subscriber map

    When I was very young I went a Montessori school here in
    Toronto. If you’re not familiar with Montessori education, it’s basically a
    very open ended and independent form of learning. Students choose
    what they want to do.

    Because of this, many have argued that a Montessori
    education is actually great training to be an entrepreneur
    . Instead of being
    told what to do, you as a student need to figure it out on your own. See the
    parallel? Both Google founders went to Montessori school.

    When I was there (< grade 4), my absolute favorite thing
    to do was draw maps. I remember them having these large scale maps of the world where you could
    physically remove each country so that you could then trace it and create your
    own maps. I spent a lot of time doing exactly that.

    To this day, I still really love maps. And I remember many
    of my friends in architecture school being the same way. So perhaps it comes
    with the territory.

    In any case, I recently started playing around with a product
    called cartoDB. And one of the things you can easily do with it is connect it
    to Mailchimp (the service that manages the ATC email newsletter) and anonymously
    map the location of each subscriber. I couldn’t resist giving it a try.

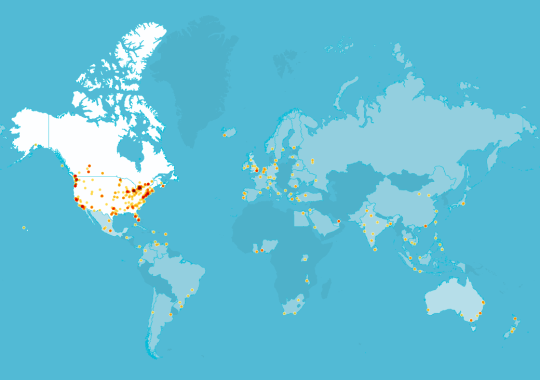
    Below is what that looks like. Not surprisingly, the highest
    concentrations of subscribers to this blog are in Canada and the US.

    image

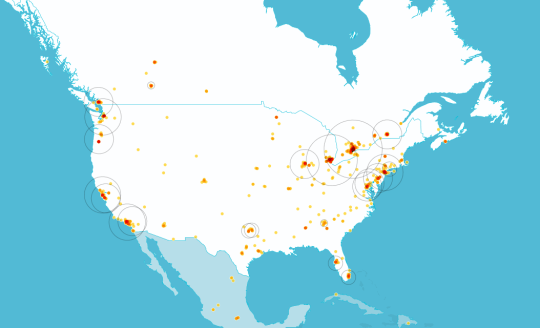
    So here’s a zoomed in version:

    image

    I’ve been trying to branch out from talking about Toronto
    all the time. And that seems to be working somewhat. But I could still do a better
    job of creating more global content. I’ll try harder.

  • America really is building very few condominiums

    On my way back from Philadelphia
    this past weekend I wrote a post called, The
    Philadelphia (real estate) story
    . It was about how opposite the market is
    in Philly compared to Toronto.

    After writing that post and
    because of a discussion in the comment section, I started thinking about condo
    vs. rental apartment development across the US. Because unlike cities such as
    Toronto and Vancouver, it struck me that – outside of maybe New York and Miami
    – most U.S. cities are really not building a lot of for sale condos. And if
    you’re from Toronto or Vancouver, I bet that feels odd to you.

    But what exactly is that number?

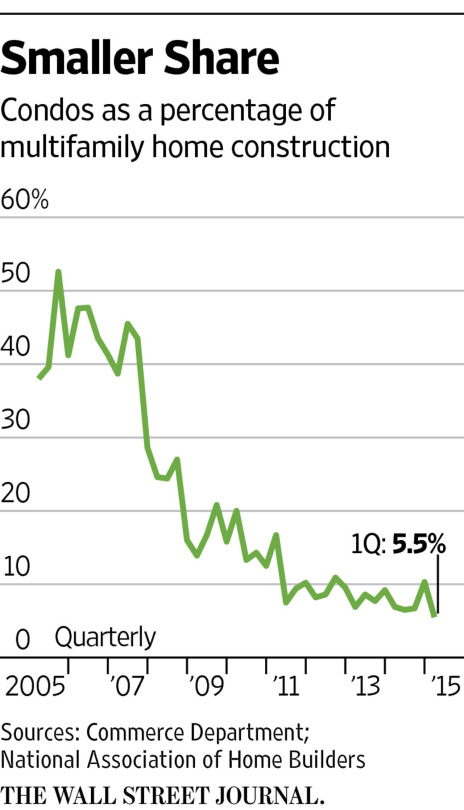
    As of the first quarter of 2015, condos as a percentage of all new
    multifamily (apartment) construction in the US was only 5.5%. That’s a tiny number and is down from
    over 50% before the Great Recession, which means most
    cities in the US really are building mostly rental. Last year the US built 264,000
    multifamily units across 11,000 buildings
    .

    So why is that happening?

    There appears to be a number of
    factors, according to a
    recent article in the Wall Street Journal
    .

    There’s a supply side
    constraint:

    Another obstacle cited by developers: construction loans. Matt
    Allen, chief
    operating officer of the Related Group, a developer based in Miami, said he can
    get a construction loan for roughly 75% of the cost of building an apartment
    complex. But lenders will cover only 50%, on average, of a condo complex’s cost
    because of the greater risk, he said.

    There’s a demand side
    constraint:

    As a result, the Federal Housing Administration, which
    backs mortgages made to low-wealth buyers, tightened its lending standards in a
    series of moves from 2008 to 2012. Under the new rules, in order for the FHA to
    insure mortgages in a given condo complex, at least half of the units must be
    owner-occupied and no more than half can be FHA-insured, among other
    requirements. For condo projects under development, at least 30% of units must
    be under contract for sale before the FHA will start backing mortgages there.
    Mortgage giants Fannie Mae and Freddie Mac tightened
    their standards as well.

    And there are macroeconomic
    factors:

    On the entry-level end, tepid job growth early in the
    recovery and the younger generation’s affinity for flexibility have fueled
    demand for rentals. Apartment rents are up nearly 16% since 2010, according to Reis Inc.

    Notwithstanding
    the above, could this be a post-recession policy pendulum that has swung
    too far in one direction?

  • The global pyramid of wealth

    Every year the London-based property consultancy Knight Frank publishes something called The Wealth Report. And it’s one of those reports that I could go through for hours. 

    It includes a ton of really fascinating stats that speak volumes about where in the world wealth is being created and how it’s moving around. And of course there are a lot of connections between wealth, real estate, and city building.

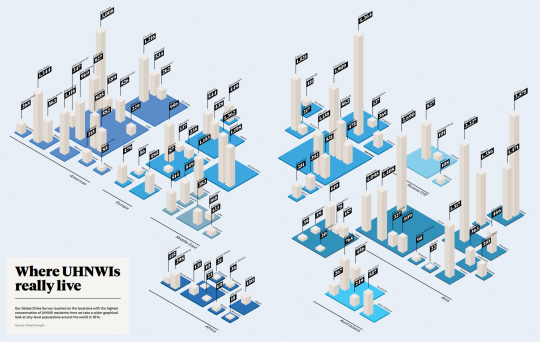
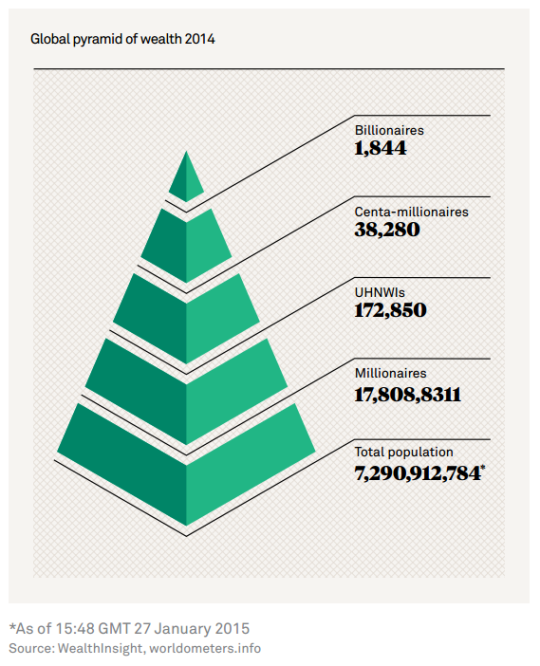
    Below are 3 diagrams that really stood out for me in the 2015 version. 

    The first diagram shows which cities have the most Ultra High Net Worth Individuals (UHNWIs). An UHNWI is defined as an individual with assets exceeding US$30 million, but excluding personal assets and property (such as one’s principal residence). Click here to see the full size image (I know the numbers are small).

    image

    Not surprisingly, London (4,364), Tokyo (3,575), Singapore (3,227), New York (3,008), and Hong Kong (2,690) are at the top of the list. But I was a little surprised – albeit happily surprised – to see Toronto (1,216) come in at #2 in North America, beating out Mexico City (1,116), Los Angeles (969), and Chicago (827). 

    The second diagram shows you how many square meters of luxury property (apartment) you can buy for US$1 million in a bunch of different cities around the world. 

    In Monaco (top end), that’ll buy you 17 square meters (183 square feet) and in Cape Town (bottom end), that’ll buy you 208 square meters (2,196 square feet).

    image

    The third and last diagram is what they call the global pyramid of wealth. It’s a pyramid of everyone in the world and then the number of millionaires, UHNWIs (see above), centa-millionaires, and billionaires. And if you do the math, the top of this pyramid comes nowhere close to 1% of the global population.

    image

    It’s fascinating (and exciting) to see where and how global wealth is concentrating. But it should also make you think about rising income inequality. I know it does for me.

  • The Philadelphia (real estate) story

    Real estate is a local business. And this weekend in Philadelphia really reminded me of that.

    Here’s what I mean.

    The real estate story in Toronto is condos. We’re buildings lots and lots of condos. When my friend from Chicago recently visited Toronto for the first time, he told me that it feels very similar to Chicago, except that we have modern glass condo towers going up everywhere and they don’t. That’s our story right now.

    Low-rise housing in Toronto is becoming increasingly unaffordable (the average price of a detached home is well north of $1M) and so high-rise condos are now what many people can afford. When young people in Toronto talk about buying their first place, that now usually means a condo.

    But that’s not the story in Philadelphia.

    In Philadelphia, you can buy a 1,600 square foot, 2 storey, 2 bedroom rowhouse in a respectable neighborhood for sub US$400,000. And in speaking with my friends in Philly this weekend, that’s what young people are buying.

    This doesn’t mean that Philadelphia isn’t building new high-rise condos and apartments. It is. Obviously nowhere near as many as Toronto. But it is building. Far more than when I lived there before the Great Recession.

    However, the condo market is typically more upmarket. The target market isn’t so much first time buyers and the mass market; it’s more people who want full floor apartments in Rittenhouse Square. (I’m exaggerating only slightly.)

    Philadelphia is also building more rental towers than condo towers. (Rental has only recently become fashionable again in Toronto.)

    I’m guessing that a lot of this has to do with the fact that Philadelphia draws in a lot of transient students and academics each year. In fact, the most noticeably changed area from when I lived in Philly was University City. That’s the area that houses the University of Pennsylvania and Drexel University.

    So there seems to be strong demand for new rental housing in the city. I’m told vacancies are very low. But when it comes time to buy, young people don’t look to condos like they do in Toronto. They are looking mostly to rowhouses.

    This is interesting to me because it’s the exact opposite of Toronto. In Toronto, low-rise is expensive and so lots more people are buying high-rise. In Philadelphia, high-rise is expensive and so people are buying low-rise.

    I guess that’s why they say real estate is a local business. What works in one city may not work in another.

  • 1 bedroom condo for sale

    image

    I’m hijacking Architect This City today to help my mother out and try something new.

    She is looking to sell her 1 bedroom condo in the Radiocity Condominiums, located at 285 Mutual Street in Toronto. It’s called Radiocity, not because the developers thought New York was cool (my pet peeve), but because the site used to be the headquarters of the Canadian Broadcasting Corporation (CBC) way back when.

    The 2-tower complex is located north of Carlton Street, between Church Street and Jarvis Street, and is adjacent to Canada’s National Ballet School (designed by KPMB Architects). It’s close to College Park and Yonge & College.

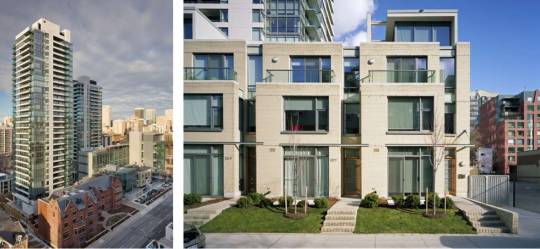
    It was completed/registered in 2005 and won a number of design awards, including one from the Royal Architectural Institute of Canada. Notable about the design is the way it integrates townhouses at the base, a public courtyard (with public art) between both towers, and the Ballet School. (A deal struck with the developer and the CBC allowed the school to buy their portion of the land for $1). 

    The buildings were developed by Context Development and designed by architectsAlliance, which is actually the same developer-architect duo behind the building I currently live and own in. I’m clearly a big fan.

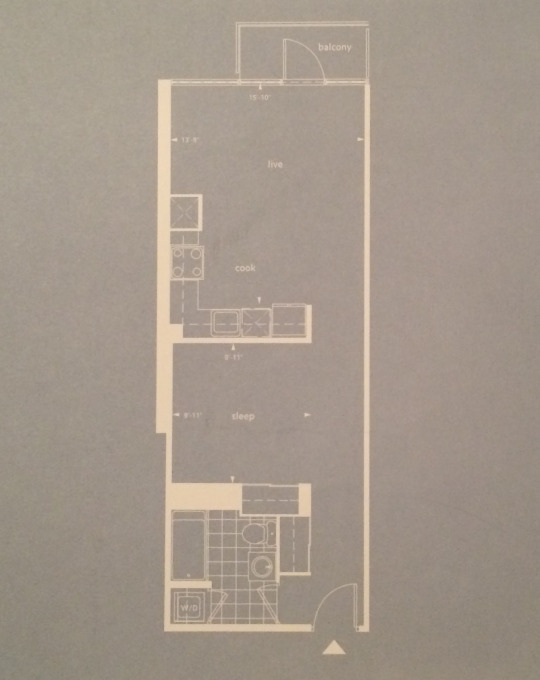
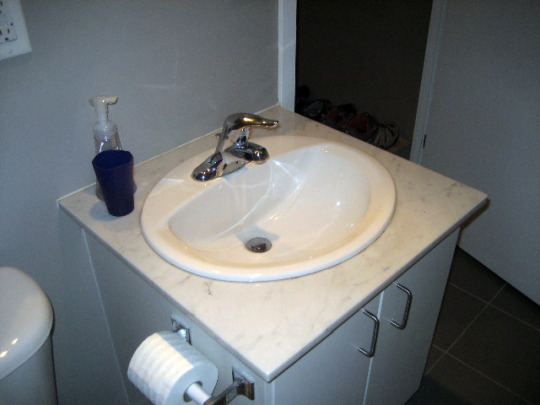
    The suite is about 560 square feet. It has 9’ exposed concrete ceilings. It has one full bathroom (tub), with a stacked washer and dryer. The bedroom is about 10’ x 10’ and is setback from the outside windows and enclosed with 3 x translucent sliding doors from C-Living. (I had them installed myself and they’re much better quality than the sliding doors you’ll find in most new builds.) The kitchen and living area is open concept, and there’s a north facing balcony that overlooks a quiet private courtyard. You basically get a view of trees, greenery, and the city. The suite is located on the 7th floor.

    Here’s the floor plan:

    image

    And here are a few photos. They are all the right proportions and haven’t been stretched to make the space look bigger 🙂

    imageimageimageimageimage

    The building has 24-hour concierge, visitor parking, and 3 floors of amenities. The amenities include a gym, aerobics room, party room, saunas, media room, boardroom, multiple lounges, 2 x guest suites, a party room, and a billiard room. 

    College subway station is a 7 minute walk (600m).

    image

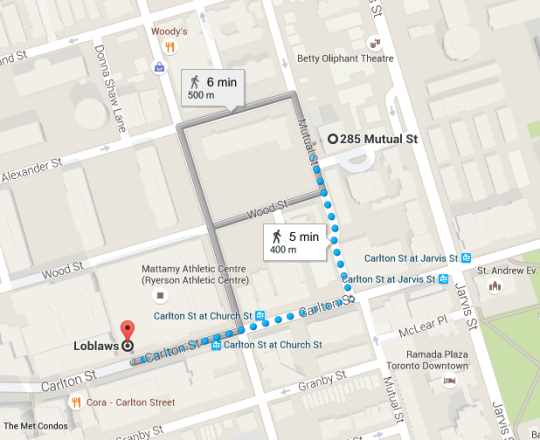
    The Loblaws grocery store at Maple Leaf Gardens (which is awesome and also includes an LCBO) is a 5 minute walk (400m). Though I’m fairly certain you could do it in 4 minutes.

    image

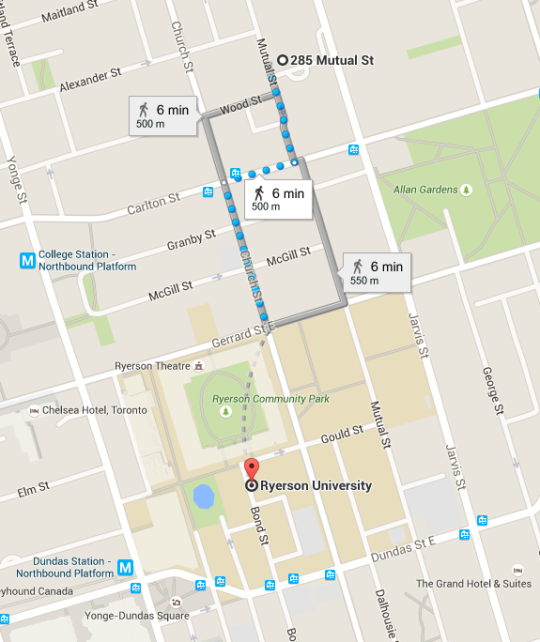
    And you’re a 6 minute walk to Ryerson University (500m).

    image

    The asking price is C$349,900. The maintenance fee is $426.64 per month and the property taxes are $2,039.19 per year.

    It’s a private sale, but she is willing to cooperate with buyer’s agents (2.5% commission). It’s currently furnished, but you can have it either way you want (unfurnished or furnished).

    If you have any questions or would like to book a viewing, please send her or me an email. If you’re an agent just looking for a listing, please don’t. Thanks for reading. Regularly scheduled programming will resume tomorrow.

    Image at the top of this post is from architectsAlliance.

  • New York’s 8-figure apartments

    Whenever you’re starting to feel like real estate prices in your city are getting out of hand, just turn your attention to New York. It’ll make you feel better.

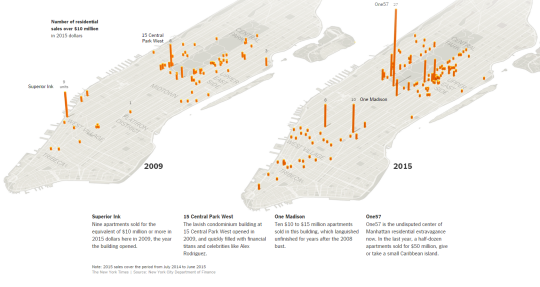
    The New York Times published an interactive overview of the Manhattan real estate market today. It was spurred on by the fact that the average residential sale price in Manhattan just hit $1.7 million (a new record) and that there’s a growing number of 8-figure apartments being bought up.

    Last year half a dozen apartments sold for more than $50 million in the One57 tower at 157 West 57th Street. (The New York Times calls this building the “undisputed center of Manhattan residential extravagance.”)

    Here’s one of their diagrams showing the number of residential sales over $10 million in 2009 and then in 2015:

    image

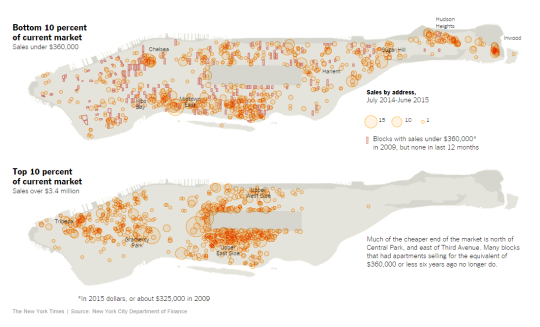
    And here’s another one of their diagrams showing the bottom and top 10% of the current market:

    image

    It’s interesting to see the clustering in certain areas and also the lack of clustering at the high end around the top of Central Park.