Daily insights for city builders, delivered every morning at 6 AM ET. I’m Brandon Donnelly — a Toronto-based real estate developer and founder of Globizen. I’ve been writing here since 2013.

Tag: real estate

  • What sea level rise is doing to the urban landscape of cities

    Resiliency is an important topic in urbanist circles these days.

    New York is working on a 10 mile “Dryline” to protect itself from future storms similar to Hurricane Sandy. And Miami Beach – one of the most vulnerable cities in the U.S. to sea level rise – is frantically building pump stations and raising its seawalls, streets, and sidewalks.

    Here’s what the city’s public works director had to say via a Curbed article published about a week ago:

    Miami Beach is planning to spend upwards of $500 million over the next five years on the pump stations and street-raising projects. “We are quite certain we are going to buy ourselves another 30 years, and we are hoping we are going to buy ourselves another 50 years,” Carpenter said.

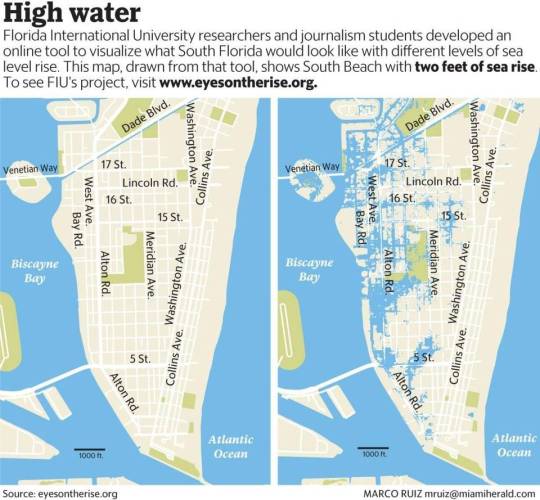
    According to Wired, sea levels off the coast of South Beach have risen by 3.7 inches since 1996. But over the last 5 years the high tide levels have had an average increase of about 1.27 inches per year!

    This matters a great deal because of what South Beach would look like if sea levels increased by 2 feet (via the Miami Herald):

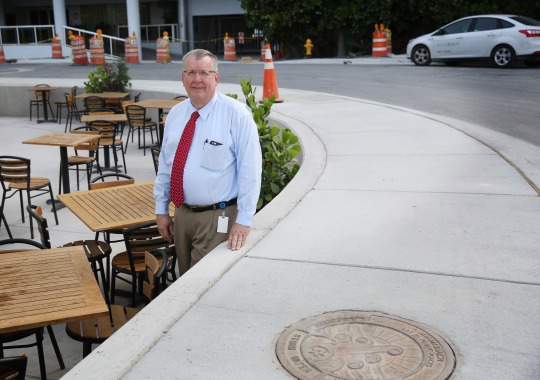
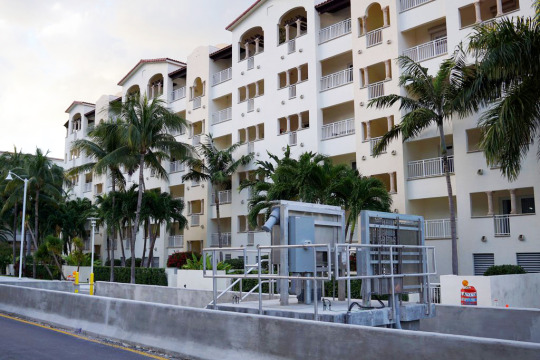
    It’s for this reason that Miami Beach has been working to alter its street elevations and install pumps – as many as 80 of them over the next 5 years – that quickly drain stormwater into Biscayne Bay. (The drains are equipped with backflow preventers so that the water leaves but doesn’t come back into the island.)

    Here’s an example of a raised street and sidewalk (via the Miami Herald):

    And here’s an example of a pump station (via Curbed):

    All of this strikes me as necessary work for Miami Beach. But I also think it’s important to keep in mind that all of this is patch work – regardless of how necessary it is right now. 

    The bigger question is: what are we doing to stop sea level rise? That’s the only way we’re going to get to true, urban, resiliency.

  • Rethinking downtowns to improve urban mobility

    Jarrett Walker of Human Transit recently published an interesting post talking about downtowns. His argument is that we shouldn’t be planning our transit networks around the traditional notion of a single-centered city.

    Here’s a snippet:

    So growing a single downtown isn’t the key to becoming a great transit city. Quite the opposite, it’s best to have a pattern of many centers, all generating high demand, and supporting balanced two-way flows between them that let us move more people on less infrastructure.  This is the great advantage of Paris or Los Angeles or the Dutch Randstad over Chicago or Manhattan.

    Now, there are many cases where a singular economic center still dominates an urban region. See downtown Toronto. And many will argue that the current economic environment is creating more, rather than less, concentrated urban spikiness.

    But at the same time it is quite clear that many of our cities have shifted away from a monocentric model to a polycentric one. 

    I mean, just look at all employment nodes that have developed across the Toronto region. The idea that everyone comes downtown in the morning and then leaves in the evening has become an anachronism for many. Early in my career I spent 4 years commuting from downtown to the suburbs.

    So what is happening is that our cities need to start performing more like point-to-point networks. This isn’t a new thought. But it’s a lot harder to execute on compared to what many cities have been used to. 

    You need a critical density of both residents and employers and the right kind of connectivity to create a true “mobility hub.” In Toronto, you could argue that we really only have one of those and it’s centered around Union Station.

    But I think that will change for many cities. And when we do get it right, we will be doing a lot to improve the crippling traffic congestion that so many of our cities are suffering from.

  • The biggest international buyers of American homes

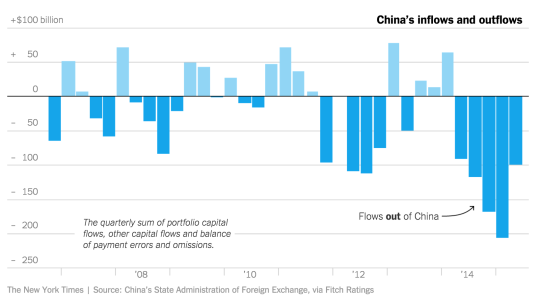
    A reader recently sent me a New York Times article talking about Chinese buyers flooding into the US residential real estate market. This is something that I’ve written about before, but I liked the “graphic” section called The Roots of China’s Real Estate Rush.

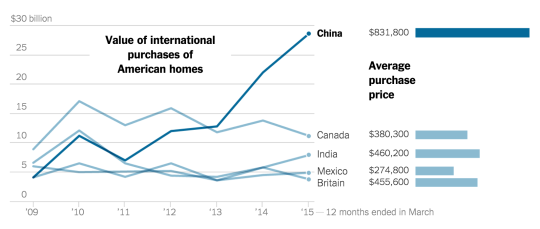
    Here are two of the graphs:

    imageimage

    The second chart shows you just how much more significant Chinese buyers are compared to the next biggest foreign customer of American homes: Canadians. And with the Canadian dollar where it is, it is no surprise that we are trending downwards. That doesn’t seem to be the case with the Chinese.

  • The Monocle Travel Guide Series — Miami

    I’m off this week to South Florida to check out Art Basel (among other things). This week isn’t a great week to be leaving the city since it’s the Toronto Real Estate Forum and lots of people are coming to the city for that. But I’ve wanted to go to Art Basel for over a decade, so it was about time I did that.

    I also decided to pick up the new Monocle Travel Guide to Miami. This is the 8th city that they’ve covered and, as you might know from reading this blog, I’m a big fan of Monocle. (I’m still waiting for the Toronto edition, guys.)

    As part of this guide launch – which was timed to coincide with Art Basel Miami Beach – they also released a short video that is worth watching.

    When most people think of Miami they probably think of sun and flash. And that is certainly part of the DNA of the city. But Miami has also grown into a global city with important and extensive connections to Latin America. It’s also an incredible place for those who love art, architecture, and design. If you watch the Monocle video, I’m sure you’ll feel that. 

    Miami is absolutely one of my favorite cities.

  • 3 real estate + tech startups

    image

    On Thursday night I spoke at Product Hunt Toronto about the overlap between real estate and tech. My slide deck will be made available online and I’ll be sure to tweet it out and link to it in the comment section of this post.

    What was amazing to see was a room filled with 250 people coming together from almost two different worlds. I’m generalizing here, but you had the real estate people in suits and the tech people in t-shirts. But they were all mixing together to figure out how technology is going to disrupt the real estate industry. That is great to see.

    This was not the case 5+ years ago when I started obsessing about the overlap between these two spaces. I remember pitching at a Startup Weekend here in Toronto where I was pegged as the fringe outlier for wanting to work on a real estate idea. Now I can’t keep track of all the startups who are tackling this space.

    But this is a trend that is happening not only in real estate but in almost every other vertical. Here’s a quote from Fred Wilson that I used last night:

    “One of NYC’s great strengths is the diversity of its economy – finance, real estate, media & entertainment, retail, fashion, health care, education, and now tech. And the reason tech is growing so fast in NYC is that it is embedding itself in all of these other industries.”

    It’s an exciting time.

    In any event, for those of you weren’t able to attend, the 3 startups that presented were Evercondo, PiinPoint, and MappedIn.

    Evercondo is a condo communication and management tool for property managers and boards. PiinPoint is a data-driven tool that helps businesses find the best places to locate within a city. And MappedIn creates digital wayfinding solutions for (primarily) retail stores and venues.

    If you know of any other interesting startups tackling the real estate space, please share them in the comment section below. Early stage companies need all the support and exposure they can get.

  • But what about employment?

    The Neptis Foundation here in Toronto just recently published a fantastic report looking at the regional economic structure of the Greater Golden Horseshoe area. It’s called Planning for Prosperity.

    In it they identity the polycentric nature of employment in the Toronto region by way of downtown Toronto and three suburban “megazones.” Here’s one of their maps showing overall employment density and the megazones (light blue circles):

    Here’s a snippet to give you an idea of the scale of these megazones:

    “The Airport megazone, one of the three employment megazones outside Downtown Toronto, is the second largest concentration of employment in Canada, after Downtown Toronto. It represents almost 300,000 jobs, more than the central business districts of Montreal, Vancouver, or Calgary individually.”

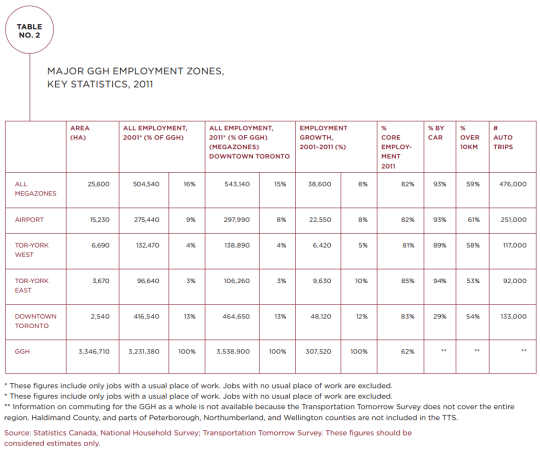
    And here’s a chart showing the hard numbers:

    Downtown Toronto dominates in terms of employment. But it’s also fascinating to see how much more efficiently it provides that employment. It has the smallest physical area of all the employment zones (2,540 hectares or 6,276 acres) and the lowest percentage of car trips (29%).

    But the big takeaway from their report is that we have not been focused enough on employment in our planning. Instead, we seem to be thinking residentially. Here’s a final snippet:


    “This study shows that the Growth Plan and The Big Move, which are currently under review, do not address the challenges and opportunities of a globalizing regional economy or the reality of a transforming economic landscape.

    The Growth Plan’s focus has largely been on managing residential growth rather than non-residential and employment-related development. Indeed, the Growth Plan is based on shockingly little hard evidence on the evolving economy of the region. Plans for city-regions a fraction of the size of the GGH typically involve more economic research, analysis, and evidence.”

    Clearly we need to be looking at both the residential and non-residential sides of the equation as we grow the region. To read the full report, click here.

  • The democratization of real estate

    In 1960, real estate investment trusts were created in the U.S. with the goal of democratizing real estate ownership. Here’s how Yale professor Robert Schiller described it:

    “REITs were created by law in 1960 to democratize the real estate market and make it possible for a broad base of investors to participate in this huge asset class. That was absolutely the right thing to do, because portfolio theory tells us people should diversify across major asset classes, and real estate is one of them.”

    But a lot of things have changed since 1960. We now have the internet. 

    And one of the things that the internet is very good at is creating peer-to-peer networks that connect supply and demand without the same kind of intermediaries. This could be people who have MP3s with people who want MP3s or it could be people who have real estate with people who are looking to invest in real estate.

    So with the advent of crowdfunding in both the U.S. and Canada, I think we are at the dawn of another era of real estate democratization. Already we have seen the first crowdfunded real estate development project and it happened at a much smaller and local scale than is usually the case with REITs.

    Similarly, we are also seeing companies emerge – such as HomeUnion in the U.S. – that allow people to build their own rental portfolios by directly investing, either fully or partially, in real estate. Again, there are differences here compared to how REITs typically operate.

    When I was in grad school at Penn and Sam Zell used to come in and talk to the students, he used always mention how when he started out in real estate (1960s) the industry was disproportionately controlled by a small number of players. That’s been changing ever since and it looks like that trend will only continue.

  • A panelization system for precision homes

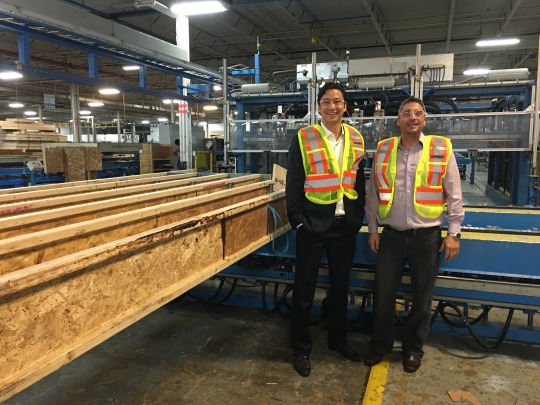
    I recently had the opportunity to visit the 200,000 square foot manufacturing facility of H+ME Technology here in Toronto.

    Here’s a photo of myself and Nick Zicaro:
    image

    H+ME (originally called Brockport Home Systems Ltd.) is a division of developer Great Gulf, but they were never intended to be just an in-house provider and much of their business is now with outside clients.

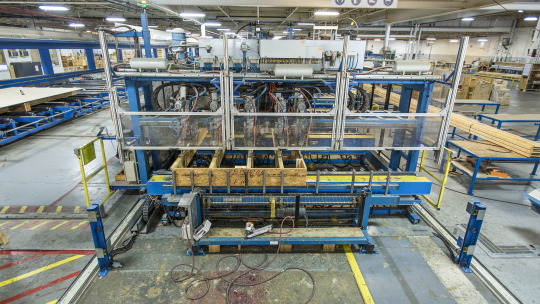
    What H+ME Technology does is manufacture and assemble factory-built wood panels for both low-rise and mid-rise new construction homes. That is, instead of the walls and floors being framed outside on the construction site, they are fabricated ahead of time in a controlled facility (see below) and then delivered to site. This allows for a single-family home to be framed in as little as 2 days on the job site.
    image

    What’s interesting about all of this is that architects have long been obsessed with the idea of shifting construction away from the actual job site. A great book on this topic is Refabricating Architecture by Stephen Kieran and James Timberlake. In it they talk about how inefficient our construction processes are and how we ought to move towards a fully integrated approach that brings together technology, materials, and production methods.

    And in 2006 they put their money where their mouth is and built a fully prefabricated house on Taylors Island in Maryland. Here’s an snippet from their website:

    “Most houses are built from thousands of parts, which are transported separately to the construction site and pieced together by hand—a process of extraordinary duration, cost, and environmental impact. With Loblolly House, by contrast, we wanted to use integrated assemblies of those parts, fabricated off site, to build a house in an entirely different way.”

    The big advantage of this entirely different way is that you’re able to dramatically improve efficiencies, quality, and performance by fabricating the components in a controlled environment, as opposed to on-site by hand.

    Despite all this, the industry has been incredibly slow to change and most houses are indeed not built this way. But H+ME is working to change that, which is why I was keen to check out their facility and learn about their business.

    So here’s how it works:

    H+ME starts by modeling out the entire home in 3D CAD according to the project drawings. This allows them to catch any design coordination errors before they happen on-site. And it’s why their slogan is “Twice built. Assembled once.” They are literally building the entire house in 3D ahead of time.

    Once the house has been modeled, they then send the designs for the walls and floors to their factory and begin production. During this process, all of the rough-ins for electrical, plumbing, and so on, are provided, which makes it super easy for the trades on-site later on.

    Here’s what that looks like in the factory:

    //platform.instagram.com/en_US/embeds.js

    And here’s what the scene looks like on-site when the panels get delivered:

    //platform.instagram.com/en_US/embeds.js

    Ultimately, their vision is to be able to deliver fully closed walls to site. This would mean that all the plumbing, electrical, insulation, and so, would already be in the walls and be ready to get connected/assembled. All of this is a significant step forward.

    Because as Stephen Kieran and James Timberlake argued in their book, this is where the industry is headed. We are headed towards much closer integration across design, technology, materials, and production methods.

    And in the end this is a great thing for both the industry and for consumers. It will translate into less coordination errors. Less construction waste. Less environmental impact. Greater construction efficiency. And much higher quality homes. I can’t wait to see more of this.

    A big thanks to the folks at H+ME Technology for taking the time to speak with me and tour me around their facility. If you’re interested in this space, they will be hosting a Q&A session on Twitter this Wednesday, November 25th at 8pm eastern time. You can join here or using the hashtag #TalkHomeTech. I’ll be tuning in.

  • Honduras is building a decentralized land registry system using the bitcoin blockchain

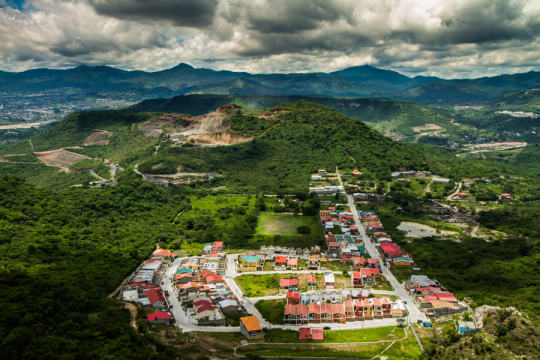
    Tegucigalpa by José López on 500px.com

    https://500px.com/embed.js

    I am very interested in bitcoin because of the underlying technology behind it – namely the blockchain. And that’s because it has the potential to be applied to and to disrupt many different industries and sectors, including real estate.

    That’s why I was fascinated to learn over the weekend that Honduras, with the help of a Texas-based company called Epigraph, is in the midst of building a permanent land title registry system based on the blockchain architecture.

    This is particularly important for Honduras because the country currently suffers from a significant amount of land fraud. And according to Reuters, 60% of land is actually undocumented. So the impact of a secure blockchain-based registry system could be transformational.

    Obviously the impetus for Honduras doing this is to fix the broken system that they currently have in place. But there’s no reason that it couldn’t also be done in the developed world to reduce transaction costs and improve overall transparency in the marketplace.

    Hopefully Honduras will show us how it is done.

    If you’re curious and would like to learn more about the blockchain, here’s a short primer. Once you’ve read that, you can then check out this post I wrote talking about how the blockchain could be applied to real estate.

  • This U.S. housing boom is different

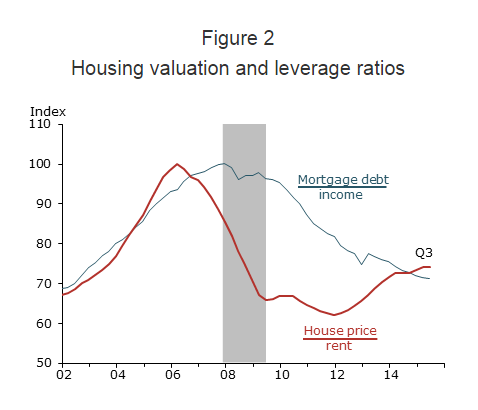
    Just a few days ago, The Federal Reserve Bank of San Francisco published an interesting research study where they argue that this U.S. housing boom is different than that of the early 2000s.

    During the last boom, U.S. home prices peaked in 2006 and then dropped about 30% in the wake of The Great Recession. Since then prices have rebounded – almost to their pre-recession levels. This has some people asking whether this story is headed towards the same ending.

    But the FRBSF is saying no:

    “We find that the increase in U.S. house prices since 2011 differs in significant ways from the mid-2000s housing boom. The prior episode can be described as a credit-fueled bubble in which housing valuation—as measured by the house price-to-rent ratio—and household leverage—as measured by the mortgage debt-to-income ratio—rose together in a self-reinforcing feedback loop. In contrast, the more recent episode exhibits a less-pronounced increase in housing valuation together with an outright decline in household leverage—a pattern that is not suggestive of a credit-fueled bubble.”

    And here’s the chart:

    Source: Flow of funds, Bureau of Economic Analysis (BEA), CoreLogic, and BLS. Data are seasonally adjusted and indexed to 100 at pre-recession peak.