Daily insights for city builders, delivered every morning at 6 AM ET. I’m Brandon Donnelly — a Toronto-based real estate developer and founder of Globizen. I’ve been writing here since 2013.

Tag: real estate

  • The investment case for mid-rise condos

    Shane Dingman’s recent Globe and Mail article about “the investment case for mid-rise condos” is a good summary of why this housing type has become so popular in Toronto.

    Mid-rise buildings tend to attract more end-users because of their boutique scale. That is, they attract people who plan to move into the building once it is built, as opposed to buyers who plan to rent out their unit. We are certainly seeing this with purchasers at Junction House.

    Because of their generally smaller scale and because they are often built in mature neighborhoods with few opportunities for new construction, supply of new mid-rise housing also tends to be limited. That bodes well for future price appreciation.

    Here’s a quote from Shaun Hildebrand (President of Urbanation), taken from the above Globe article. (Sorry, it’s behind a paywall.)

    “Price growth between the two building types [mid-rise and high-rise] began to converge in 2018, and in Q1-2019, buildings under 12 storeys saw average resale prices per square foot grow 10 per cent year-over-year, compared to 6.5 per cent for buildings of 12 or more storeys,” Mr. Hildebrand said. “We may be now entering back into a period of outperformance of mid-rise buildings as the market is shifting.”

  • A new way to grow islands

    MIT’s Self Assembly Lab and Invena (which is an organization based out of the Maldives) are trying to invent a system of underwater devices that naturally harness wave energy to restore and/or create new beaches, sandbars, and islands. The hope is that this line of thinking could be scaled up and eventually used a response to sea level rise, as well as other coastal challenges.

    Here’s a short video explaining the initiative:

    With over 40% of the world’s population supposedly living in a coastal area, this is a problem that will need to be addressed. Already we are seeing these concerns start to rear their head in the real estate markets of some particularly vulnerable cities. The team installed their first field experiment in the Maldives this past February and a second one is expected in Q4-2019.

    For more information on the “Growing Islands” project, click here.

  • The WeWork of vacation rentals

    The word on the street is that Sonder — the marketplace for vacation rentals and competitor to Airbnb — is close to finalizing a $200 million investment round that would value the company at $1 billion.

    I first wrote about Sonder back in 2016 after I met someone from their business development team here in Toronto. I have yet to stay in a Sonder, but I’ve looked at their rentals a few times.

    One of the main differences between Sonder and Airbnb is that the former head leases their rental supply. And they do this by trying to go higher up on the food chain and partner with developers and real estate operators.

    In this regard, they are similar to WeWork. And it allows them to sit somewhere in between Airbnb and a conventional hotel. The supply is distributed, but the service offering is more consistent.

    Of course, this arguably makes their business model slower (they have to negotiate leases) and more costly (they’re committing to fixed costs). So it becomes a question of: How valuable is that consistent service offering?

    Lately when I travel, I’ve been trending more toward hotels, as opposed to Airbnb-like rentals. I like the experiences that many hotels are now focused on creating and I like knowing that if my flight arrives late (in a place like Brazil), I’ll be able to get into my room.

    I guess consistency does matter.

    Photo by Spencer Watson on Unsplash

  • DroneBase adds thermal imaging missions

    I was reading today about how DroneBase has partnered with FLIR Systems to offer infrared and thermal imaging missions. FLIR actually invested in DroneBase. For those of you who aren’t familiar with DroneBase, they operate the largest drone network in the world and have a wide variety of services geared toward the real estate industry.

    This news is noteworthy because infrared thermography cameras allow you to see and measure the thermal energy emitted from objects — such as buildings. For the real estate industry, or even for individual homeowners, it would allow you to quickly visualize things like leakiness (lack of air tightness), water damage, and so on.

    These kinds of scans already exist, but putting thermal sensors on drones has the potential to make this technology much more scalable and cost effective. I am sure we will be seeing more of this. And when we do, I bet we’ll discover that many buildings don’t actually perform all that well from an energy standpoint.

    Photo by Goh Rhy Yan on Unsplash

  • The story of Florence Casler

    Curbed has a section on their website dedicated to “deep dives on cities, architecture, design, real estate, and urban planning.” It is called Longform. And they have some great stories, including this one on “the female powerhouse [Florence Casler] who developed 1920s Downtown LA.”

    Florence was born in 1869 in Welland, Ontario, about 25 kilometers south of Niagara Falls. She married an American — a plumber — and eventually settled in Buffalo, New York. After her husband left to pursue riches in the gold mines, she became a licensed plumber and took over the business.

    Eventually this love of plumbing grew into a love of building, and somehow she found herself, with her daughters, in Los Angeles at the beginning of the 20th century.

    By the 1920s, she had become a dominant force in the real estate business. Some 60 buildings are credited to Florence and she is thought to be largely responsible for ushering in a new era of multifamily apartments in Los Angeles. Unfortunately, many of her buildings have since been demolished.

    As one of the first women in Los Angeles to head a development and/or construction business, I think this is a wonderful story worth telling. For the full Curbed article, click here.

  • New York’s “pied-à-terre tax” explained

    New York is close to implementing new “pied-à-terre tax.” If the bill passes, which the New York Times believes is likely, cities of a million or more people will be able to levy an additional property tax on non-primary residence homes worth $5 million or more. The additional tax would be based on the following sliding scale:

    So let’s say for argument sake that you own a pied-à-terre in New York City worth approximately $238 million. Based on the above, your additional tax would be $370,000 + [4% x ($238 million – ~$25 million)]. That’s almost $8.9 million. Most of the revenue from this tax is expected to come from this upper (and open-ended) valuation bracket.

    New York City estimates that the tax could bring in about $650 million annually. The state in turn believes it could then raise $9 billion in bonds. And the intent is that these additional funds could be used to fund things like transit and housing. I am curious how elastic the demand is for trophy real estate in New York.

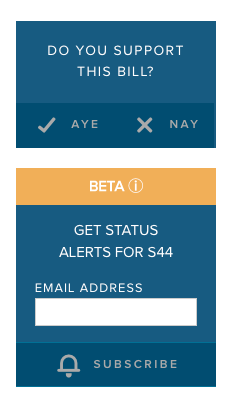
    Another thing I noticed while reading up on this bill is that the New York State Senate has made it pretty easy to voice your opinion on proposed legislation. On the sidebar of every bill making its way through the system is a box that looks like this:

    This is probably the clearest engagement tool I have ever seen on a government website. Do you think something like this could work for new housing?

  • Finding meaning in life and business

    I started my undergraduate degree as a computer science and physics student. But despite my love of technology (and physics, incidentally), I quickly realized that I didn’t want to end up as a software developer. I was interested in so many other things: art, design, business, real estate, entrepreneurship, cities, and so on. And at the time, I was struggling to remain focused on writing code.

    So by the middle of my second year, I decided to drop every single one of my classes and construct my own program until I figured out what I truly wanted to major in. My course schedule ended up spanning everything from the urbanization of ancient cities to the philosophy of aesthetics. It was a pretty great program if you ask me. But others wondered what I was doing.

    I did, however, already have leanings toward architecture. It felt like the perfect combination of art and science. And so while enrolled in my made up program, I started exploring the possibility of transferring schools and switching majors. Around this time I also started meeting with architects to try and learn more about the profession and see if this is something that I really wanted to pursue.

    I’ll never forget this one lunch. The architect I met with — who will, of course, remain nameless — told me very clearly: “You should do anything besides architecture. If you like drawing become an animator. If you like design, do graphic design. Just don’t become an architect.” Naturally, I came out of that lunch and decided to spend the next seven years getting two degrees in architecture.

    And even though I never became a licensed architect, and almost certainly never will, I would do it all over again given the option. I loved the journey and it is this circuitous journey that led me to where I am today, which is in a highly fulfilling career in real estate. I create new things and those things have the opportunity to improve people’s everyday lives. I’m grateful for that. But the path was anything but clear at the time.

    I am telling all of you this story because I was reminded of it when I read this fantastic article by Charles Duhigg called, Wealthy, Successful and Miserable. It is the story of how Charles, a Harvard Business School graduate, discovered that — despite obtaining boatloads of financial success — many of his classmates actually ended up miserable after school.

    Sure, we all need and deserve basic financial security. And when we don’t have it, money can really buy a great deal of happiness. But there’s lots of research out there, some of which I have written about before, that suggests that happiness quickly plateaus once our basic needs are met.

    As soon as we’re no longer worried about money, we actually crave other things from our paychecks. We want it to also be a source of purpose and meaning. To give one concrete example, the article cites a study about a set of enthusiastic and high performing janitors in a large hospital. What was ultimately found was that they saw their jobs not just as cleaning, but as a kind of healing for the patients. They had purpose.

    But what I found most interesting about the article was the discovery that finding happiness in life and business might require, or be aided by, a bit of struggle along the way:

    And many of them had something in common: They tended to be the also-rans of the class, the ones who failed to get the jobs they wanted when they graduated. They had been passed over by McKinsey & Company and Google, Goldman Sachs and Apple, the big venture-capital firms and prestigious investment houses. Instead, they were forced to scramble for work — and thus to grapple, earlier in their careers, with the trade-offs that life inevitably demands. These late bloomers seemed to have learned the lessons about workplace meaning preached by people like Barry Schwartz. It wasn’t that their workplaces were enlightened or (as far as I could tell) that H.B.S. had taught them anything special. Rather, they had learned from their own setbacks. And often they wound up richer, more powerful and more content than everyone else.

    We are, of course, talking about the “also-rans” at Harvard Business School. They’re no slouches struggling to find work. But I don’t think that negates the point being made here. It can be easy to get caught up doing what we think we ought to be doing when in reality we should be finding meaning in something we hopefully love doing.

  • Algorithmic home buying — what’s the end game?

    Bloomberg recently published a good summary of Zillow’s business and their move into algorithm home buying and flipping. (They are trying to avoid the “flipping” moniker because of the negative connotations associated with it.)

    Zillow started buying homes directly from owners last spring. They charge the seller between 6-9%, so more than using a typical agent, but inline with their competitors. There’s clearly a segment of the market willing to pay a premium for the added convenience.

    The thinking used to be that discount brokerages were the way to disrupt the housing market. This is the opposite strategy.

    Interestingly enough, Zillow felt that they needed to make this pivot with their business model. It used to be about selling ads. They were definitive in that they were not a disruptor of real estate agents.

    But now:

    If getting an offer from an iBuyer became a crucial step in the selling process, they worried, Zillow could lose its audience and its advertising base. What’s more, market researchers kept finding that consumers said they’d pay a modest premium to get a cash offer. “People expect to press a button and have magic happen,” says Rascoff, a 43-year-old former Expedia executive who’d earlier started the travel search engine Hotwire, which he sold to Expedia for $700 million. Getting into the business of buying homes directly, Rascoff says, was “the only way to remain in a leadership position.”

    Here is a map of the companies in this particular space and the cities in which they operate:

    Some investors aren’t sold on this strategy and have begun short selling Zillow (according to the Bloomberg article). I keep getting the sense that there’s a greater end game in the cards here. It is about building up A (algorithmic home buying and flipping) in order to unlock B.

    But what’s B — a new end-to-end transactional model for the housing market?

  • How to manipulate attention

    This Toronto Life article about a 32-year-old who has managed to buy 10 homes in the city is very Toronto Life. At a time where many young people are struggling to afford housing, here is a millennial who has bought 10 of them (albeit with some partners). The underlying message: You’re not working hard enough.

    I am fairly certain Toronto Life writes these sorts of articles because they know they’ll enrage people. As Facebook has taught us over the last few years, getting people pissed off is good for engagement. And engagement is what drives advertising-based businesses.

    Here is an excerpt from a recent Time article by Roger McNamee (a former Facebook advisor):

    One of the best ways to manipulate attention is to appeal to outrage and fear, emotions that increase engagement. Facebook’s algorithms give users what they want, so each person’s News Feed becomes a unique reality, a filter bubble that creates the illusion that most people the user knows believe the same things. Showing users only posts they agree with was good for Facebook’s bottom line, but some research showed it also increased polarization and, as we learned, harmed democracy.

    If you take a look at the Twitter conversations surrounding the above Toronto Life article, you’ll see the reactions you would expect: Troll article. Yeah, but how much debt has he taken on? He had help from wealthy friends. Here’s how a 32-year-old is eroding housing affordability in Toronto.

    I appreciate all of this, but I will never understand the need to shit on other people because of their successes, regardless of whether they are self-made or were born with a competitive advantage. Billionaire isn’t a bad word in my books. I am a first generation real estate developer, but I wouldn’t be at all upset if my great-grandparents had decided that buying land in Toronto was a good idea.

    Here is a guy that moved to Canada for University. Lived in a basement with cockroaches after leaving his first job after school. Took some risks. And saved his money instead of doing bottle service at the club on the weekends. I can respect that.

    But again, these sorts of articles are bound to make a lot of people cranky. And Toronto Life knows that.

    Photo by Tiago Rodrigues on Unsplash

  • Cost-plus pricing

    Today, Urbanation released its Q4-2018 market highlights report for the Greater Toronto Area. 

    The general media will pick up these numbers and tell you that there’s been a precipitous decline in the number of new condominium sales. But the reality is that 20,028 units were sold in 2018, which is actually in-line with 10-year averages for this region. 2017 was a particularly frenetic, and unsustainable, year.

    The average pre-construction sold price for a new condominium in the former City of Toronto (the core) was $1,117 psf last year, and $921 psf across the broader region. These numbers represent significant double digit increases from the year prior. But again, what I don’t think many people appreciate is that the cost environment has also changed dramatically over the last few years.

    Construction costs are way up, as are development charges and a myriad of other pro forma line items. The above numbers are simply a result of cost-plus pricing. Here’s where costs are at and here’s where we need to be to make the project feasible. Margins haven’t increased; in fact, they’ve probably been squeezed for many developers.

    I think this is an important topic that deserves more transparency and visibility. So I’m hoping to work with a developer friend of mine and publish something more substantial in the coming months.