Daily insights for city builders, delivered every morning at 6 AM ET. I’m Brandon Donnelly — a Toronto-based real estate developer and founder of Globizen. I’ve been writing here since 2013.

Tag: housing

  • European-style height, but not density

    As I wrote about last month in this pithy post, the relationship between building height and density are often misunderstood. They mean different things and so the implications for our cities can also be vastly different.

    I woke up this morning to a couple of tweets by John Michael McGrath that I think hit the nail on the end with respect to this duality. If you can’t see them below, click here.

    https://twitter.com/jm_mcgrath/status/1105500872979742720

    Paris is known, and largely celebrated, for its “European-scaled” mid-rise buildings. But as John points out, these buildings often line narrow streets (see above). They are typically also built across large blocks with compact internal courtyards and with few setbacks and/or stepbacks. The combined result is that Paris is one of the densest cities in Europe. It has mid-rise at scale.

    The North American context is quite different. The large majority of our land is usually reserved for low density housing. (Here in Toronto this land has been nicknamed the “Yellowbelt.”) We have a policy context that only allows intensification in select places, and that can create pressures to build up. It’s a bit like squeezing a closed tube of toothpaste.

    In 2012, Eurostat ranked Paris as the densest city in Europe with an average population density of approximately 21,516 people per square kilometer. Whereas, according to Wikipedia, the population density of metro Toronto was around 5,905 people per square kilometer in 2016.

    What is it, again, that we love so much about Paris?

  • New York’s “pied-à-terre tax” explained

    New York is close to implementing new “pied-à-terre tax.” If the bill passes, which the New York Times believes is likely, cities of a million or more people will be able to levy an additional property tax on non-primary residence homes worth $5 million or more. The additional tax would be based on the following sliding scale:

    So let’s say for argument sake that you own a pied-à-terre in New York City worth approximately $238 million. Based on the above, your additional tax would be $370,000 + [4% x ($238 million – ~$25 million)]. That’s almost $8.9 million. Most of the revenue from this tax is expected to come from this upper (and open-ended) valuation bracket.

    New York City estimates that the tax could bring in about $650 million annually. The state in turn believes it could then raise $9 billion in bonds. And the intent is that these additional funds could be used to fund things like transit and housing. I am curious how elastic the demand is for trophy real estate in New York.

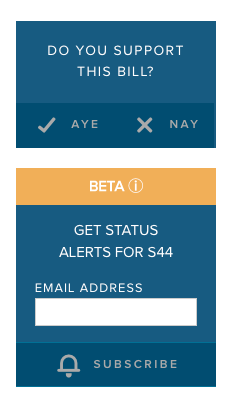
    Another thing I noticed while reading up on this bill is that the New York State Senate has made it pretty easy to voice your opinion on proposed legislation. On the sidebar of every bill making its way through the system is a box that looks like this:

    This is probably the clearest engagement tool I have ever seen on a government website. Do you think something like this could work for new housing?

  • The new American condo

    Every year since 1984, the National Association of Home Builders (in the United States) has commissioned a home with the goal of showcasing new trends and technologies in the industry. At the same time, it also serves as a kind of dream home. This is what one should aspire to achieve. The initiative is called the New American Home (TNAH).

    The first home was built in Houston by Village Builders. The architect was Booth/Hansen & Associates and the home was about 1,500 square feet. It cost $80,000. Last year the home was in Montverde, Florida and was about 10,690 square feet (6,676 square feet of air-conditioned space). Not surprisingly, these homes have grown over the decades.

    According to a recent New York Times opinion piece by Allison Arieff — called, The New ‘Dream Home’ Should be a Condo — the square footage of this New American Home has been steadily rising:

    This is, of course, reflective of what has been happening in the market as a whole. According to Arieff, the average size of a new U.S. home today is about 1,000 square feet larger than it was in 1973. The average space per human has increased from 507 to about 971 square feet. As our wealth has grown we have naturally become more consumptive.

    But as Arieff asks in her article:

    What if the next New American Home was a condo? And what if there was a new American dream, not of auto-dependent suburbia, but walkable urbanism?

    She then contrasts last year’s 10,000 square foot “Tuscan style” New American Home against this 6 unit urban infill condo project in Los Angeles, where the average home is about 1,800 square feet and the building in its entirety is around 11,000 square feet.

    Which one would you prefer?

    Charts: New York Times

  • Price of a new condominium in Toronto increased 12.5% over the last year

    This morning BILD and Altus Group released their January 2019 new home sales figures for the Greater Toronto Area.

    Here are the highlights:

    • 1,362 new homes sold in January 2019 across the GTA. This is up 14% compared to last January.
    • Of these, 942 (~69%) were condominiums (includes low, mid, and high-rise, as well as townhouses). And 420 (~31%) were single-family homes (includes detached, semi-detached, and freehold townhouses).
    • Condominium sales volume is sitting only about 5% below the 10-year average and the benchmark price increased this month to $803,638, which represents a 12.5% year-over-year increase.
    • On the other hand, single-family home sales are down about 53% from the 10-year average and the benchmark price decreased by about 8.1% compared to last year. It is sitting at $1,130,046.

    While there continues to be a bifurcation in the new home market, we are seeing improvements across the board and the data is consistent with Altus’ prediction that 2019 will see an increase in overall sales.

    It is also important to consider how geography might factor into the above numbers. Here are the January sales numbers for the last three years broken down by region within the GTA:

    Just under 80% of the new condominiums sold last month took place in Toronto, whereas only about 1.2% of the single-family homes sold last month took place in the city. You can count them on one hand. There were only 5.

    So rather than just look at this in terms of housing type, I think the other way to interpret the data is that it could suggest strong and continued demand for centrally located and transit-oriented communities.

    And that just so happens to translate into a condominium.

    Photo by Eugene Aikimov on Unsplash

  • Algorithmic home buying — what’s the end game?

    Bloomberg recently published a good summary of Zillow’s business and their move into algorithm home buying and flipping. (They are trying to avoid the “flipping” moniker because of the negative connotations associated with it.)

    Zillow started buying homes directly from owners last spring. They charge the seller between 6-9%, so more than using a typical agent, but inline with their competitors. There’s clearly a segment of the market willing to pay a premium for the added convenience.

    The thinking used to be that discount brokerages were the way to disrupt the housing market. This is the opposite strategy.

    Interestingly enough, Zillow felt that they needed to make this pivot with their business model. It used to be about selling ads. They were definitive in that they were not a disruptor of real estate agents.

    But now:

    If getting an offer from an iBuyer became a crucial step in the selling process, they worried, Zillow could lose its audience and its advertising base. What’s more, market researchers kept finding that consumers said they’d pay a modest premium to get a cash offer. “People expect to press a button and have magic happen,” says Rascoff, a 43-year-old former Expedia executive who’d earlier started the travel search engine Hotwire, which he sold to Expedia for $700 million. Getting into the business of buying homes directly, Rascoff says, was “the only way to remain in a leadership position.”

    Here is a map of the companies in this particular space and the cities in which they operate:

    Some investors aren’t sold on this strategy and have begun short selling Zillow (according to the Bloomberg article). I keep getting the sense that there’s a greater end game in the cards here. It is about building up A (algorithmic home buying and flipping) in order to unlock B.

    But what’s B — a new end-to-end transactional model for the housing market?

  • Rethinking the tower

    The Ryerson City Building Institute recently published a new report called, Rethinking the Tower: Innovations for Housing Attainability in Toronto.

    It looks at four possible approaches to improving housing attainability/affordability in the city:

    Micro Living: Well-designed micro units can offer a cost-effective alternative to conventional apartments, particularly in central locations where higher land costs can be a barrier to affordability.

    Shared Space: Co-living, where residents share amenities and services, can improve affordability and create a sense of community, particularly in walkable, transit-connected neighbourhoods where housing costs are high.

    Home Unbundling: Features, finishes and amenities unbundled from the unit price of condominiums can allow greater choice and reduced costs for homebuyers.

    Equity Options: With more households renting, and the transition from renting to owning growing ever more challenging, new shared-equity models can help families invest in their home, even if they rent.

    In addition, the report also provides a number of project case studies from around the world. If you’d like to download a copy, you can do that here.

  • Toronto to market 11 city-owned sites for new affordable rental housing

    At the end of last month, Toronto City Council adopted the “Housing Now” action plan. The first phase of the plan involves the public marketing of 11 city-owned sites for the purpose of finding non-profit and private sector partners to help redevelop the lands with new mixed-income housing. It is expected that these lands could accommodate about 10,000 homes.

    Here is the list of sites:

    As part of the offering, around 2/3 of the built units will need to be rental (the above chart shows more), and of these rental units, 50% will need to be affordable with rents set to 80% of Toronto’s average market rents. All of this should translate into approximately 3,700 new affordable homes. (Mayor Tory’s plan is to build 40,000 affordable rental homes by 2030.)

    The City wants to ultimately retain ownership of these lands, and so the sites will be offered up through long-term land leases. It looks like they’ll be for 99 years. The City will also be forgiving a number of fees and levies for the 3,700 affordable homes. They are pegging the PV (present value) of these development incentives at just over $280 million:

    Making use of surplus public land to increase the supply of affordable housing certainly makes a lot of sense. But there’s a cost burden associated with these affordable units, which is why discussions around inclusionary zoning often come back to offsetting measures. Who is going to pay for these subsidies?

    The above “financial incentives” — which in this case are simply foregone revenue — speak to this cost burden.

    Tables: City of Toronto

  • Laneway house on the market for $2,845,000

    I was looking at this laneway house for sale in Toronto today. It’s located near Queen and Bathurst. It has 3 bedrooms and 3 bathrooms and is about 2,331 square feet (that looks to include a basement). The lot appears to be just over 13′ wide. And the asking price is $2,845,000.

    Single family homes aren’t typically considered on a per square foot basis, but if you do the math here, it works out to be around $1,220 psf. The property previously sold in 2017 for $805,000, which was prior to it being redeveloped. So it likely traded based on land value.

    When Toronto first started considering modern laneway houses, some people thought that only individuals of questionable moral fiber would want to live in one. But today, there are countless examples of some pretty remarkable laneway houses. 

    And in some cases you might need about $3 million or so.

  • Are you happy with where you live?

    This past weekend I saw a few people reacting on Twitter to this article by Wendell Cox talking about how Canadian families are being denied their preferred housing choice: the detached single family home.

    The fact that the article is by Wendell Cox should tell you everything you need to know. But essentially the argument is that misguided planning policies are driving up the cost of housing and that we should, instead, be encouraging unfettered sprawl.

    There’s lots to discuss here, but the first thought that actually came to mind was: “How would this article sound if we replaced all of the references to housing with references to cars?” In case you too are wondering that, this is how the first paragraph would read:

    A new poll by Sotheby’s International Realty suggests substantial disappointment among Canada’s young urban families, unable to afford to purchase the types of [cars] that they prefer. The poll determined that young urban households in Canada strongly prefer [Aston Martins], but they are often “motivated by (financial) necessity to purchases [sic] [cars], especially [BMWs], they do not prefer.“

    The article is clearly one-sided. I don’t disagree that there are people who – all things being equal – would prefer to raise a family in a ground-related single family home. Backyards serve a purpose, as do large basements equipped with beer fridges.

    But all things are not equal. And there also people who value walkability, a reasonable commute, and the kind of urban amenities that come along with being in a dense city. I am one of those people.

    Photo by Adrien Olichon on Unsplash

  • Toronto condo market outlook

    BNN Bloomberg just published this article on the Toronto condo market. It is based on a roundtable discussion that was held at their Toronto office last week with Jim Ritchie of Tridel, Jared Menkes of Menkes Developments, Shamez Virani of CentreCourt, and Jane Renwick of Diamond Kilmer Developments.

    The overarching theme is that, after a couple of frenetic record setting years, the market should settle down in 2019, which is likely a good thing. Hopefully that will also temper construction cost inflation. We have been seeing double digit increases over the last few years (hence some of the cancelled projects).

    But as Jared points out, the fundamentals here are still strong and there are a number of supply constraints creating upward pressure on pricing:

    Jared Menkes, executive vice president of high-rise residential at Menkes Developments was unwavering for the future. “There’s a lot of red tape that’s slowing down bringing more product to market,” Menkes said. “I promise you, pricing is going up.”

    For the rest of the article, click here.