Daily insights for city builders, delivered every morning at 6 AM ET. I’m Brandon Donnelly — a Toronto-based real estate developer and founder of Globizen. I’ve been writing here since 2013.

Tag: development

  • What would you like to know about real estate development? (Also, inclusionary zoning)

    https://twitter.com/donnelly_b/status/1279410335770951680?s=20

    I asked this question on Twitter this morning because I am planning to write more development-related posts. It’s a topic that seems to be of interest to a lot of people. One question that I received was about the kind of profit margins that Toronto developers have been making over the past few decades. More specifically: How much have they increased? My response was that they haven’t increased. In fact, if anything, they’ve been compressing as a result of rising/additional costs. (I’ve touched on this before in posts like this one about cost-plus pricing.) I think a lot of developers are actually wondering how much elasticity is left in the market to continue absorbing these cost increases.

    Follow-up question to my response: Why then does this report by Steve Pomeroy claim that developers could still make a 15% margin even if they earmarked 30-40% of their units as affordable? Well, this was news to me so I went through the report and committed to responding on this blog. To be more precise, the report finds that there’s room in as-of-right developments to dedicate 10% affordable in medium-cost areas and 25% affordable in high-cost areas. For rezoned sites, the numbers are 30% affordable in high-cost areas and 15% affordable in medium-cost areas. These are a potentially dangerous set of takeaways for a few reasons.

    Very little mid-rise and high-rise development happens as-of-right in the City of Toronto. I don’t know what the exact percentage is, but I suspect it’s low. It would be very difficult to buy land if you were valuing it on this basis. And when you are valuing it — that is, running a development pro forma — it’s not enough to pull averages from a cost guide and run high-level numbers. You can start there, but ultimately you’re going to have to get more granular. Are you factoring the hundreds of thousands of dollars (more for bigger projects) that the City will charge you to occupy any public right-of-ways? What about your public contribution monies? This has historically been hard to estimate because the math that is used is akin to a secret recipe.

    In this particular report, they assume a 100-unit building with 88,750 square feet of gross floor area. Since GFA typically factors some allowable deductions, the gross construction area for the project is going to be greater. Let’s assume it’s 5% more — so about 93,190 square feet. This is how your construction manager will think about and do take-offs for the project. In the report, they peg total construction costs at $23,208,480. That works out to just shy of $250 per square foot (costs divided by above grade GCA). You cannot build a reinforced concrete residential building with below-grade parking for this number in Toronto. In today’s market, and at this small of a scale, you might be looking at $350 to 400 psf.

    On the low end of this range, that would mean your costs have just gone up by $9.4 million — which just so happens to be the expected developer/builder profit in this model. Except now you’re underwater and you won’t be able to finance and build your project. It’s probably time to look at your revenues and see if you can increase your projected rents at all. This is what I was getting at with cost-plus pricing. I would also add that I/we typically shy away from projects of this scale. There isn’t a lot of margin for error. One or two surprises and you might be cooked. So with or without inclusionary zoning, these can be challenging projects that many developers won’t even look at.

    My point with all of this is twofold: development pro formas are delicate and margins aren’t as generous and locked-in as most people seem to think. More often than not we end up passing on sites because we simply can’t make the numbers work. The land is just too expensive. Development happens on the margin. So talking about developers “absorbing” the costs of inclusionary zoning is perhaps the wrong way to frame this discussion. A more appropriate set of questions might be: Who is going to pay for the cost of inclusionary zoning? Are landowners going to suddenly drop their prices? Is the City going to reduce their development charges/impact fees? Or will developers wait until market prices and rents increase so that they can cover these new costs? This latter scenario is how it has worked so far.

    If you have other questions about development that you would like me to take a stab at answering, please leave a comment below or tweet at me.

  • The America we need

    The New York Times is running an opinion series right now called, The America We Need. It is all about how the US might emerge from this crisis “with a fair, resilient society.” This piece by Carol Galante covers many of the topics that we discuss on this blog. Carol is a former city planner and nonprofit housing developer. She is now the faculty director of the Terner Center for Housing Innovation at UC, Berkeley. Here are a couple of excerpts from her article that I think will resonate with many of you:

    There are two things we know: The U.S. economy will recover. And the recovery will start in and be strongest in the same cities that were thriving before the pandemic. Economies in places like Seattle, San Francisco, New York and Boston are driven by the innovation, technology and biotech sectors, which are proving to be remarkably resilient to the impacts of Covid-19.

    We have an obligation to ignore the short-term reactionary impulse to blame density for the spread of the coronavirus and instead use this opportunity to rethink the policies that impede the construction of new housing, at more price levels, in the places where housing is most needed.

    In my subsequent career as a nonprofit housing developer working in prosperous coastal California communities, I spent far too many nights in City Council meetings working to get apartment buildings for lower-income older people and families approved. Underlying the “density” battle was almost always a battle over who has access to the opportunities of a place and who doesn’t, cloaked in arguments about neighborhood character and traffic impacts.

  • A question of land value

    Let’s say that we have a piece of development land worth $100. That is the market value of the land based on its highest and best use at this particular point in time. Now let’s assume that the land was just encumbered with a new burden: inclusionary zoning. All of a sudden there is now a requirement to make available X% of any residential units built at 50% of average market rents for the area.

    Technically, the land is now worth less than $100. And there is a school of thought out there that, in instances like this one, the price of all land should automatically reset downward to offset and account for the inclusionary zoning burden. But as I have argued before on the blog, land prices tend to be fairly sticky, unless the owner is distressed and really needs to sell.

    So what can often happen is that the land owner will stubbornly cling to the original $100 number. The thinking being, “I was once told that my land is worth $100 and so that’s the minimum price I’m willing to accept.” In this scenario, you may need a broad increase in rents in order for a transaction to occur. This way the market rate units might be able to fully subsidize these new affordable units, preserving any margins and justifying the original $100 number.

    Of course, the impact of inclusionary zoning is a hotly debated topic and there are a number of variables to consider. And so I will leave it at that for today. The real purpose of this post is to consider another permutation. Let’s once again say that we have a piece of development land worth $100. But instead of being owned by 13 siblings — and 3 cousins that live abroad and can’t be reached other than by fax — it’s owned by the government.

    In this case, the government wants to sell the land and is considering two options. It can either (1) sell it for $100 and maximize immediate taxpayer revenue or (2) it can sell it for $80 with the condition that the buyer agree to deliver X% of affordable units (and a bunch of other goodies and positive externalities). I would also add that this fictitious town is experiencing what some might call a housing crisis.

    If you were a private sector actor, you would probably choose option 1. You would take the additional $20 and retire to Florida (I’m off by a few zeros). But this is the government we’re talking about and presumably the government is thinking about the broader public good. Which option do you think is better at maximizing that?

  • Demystifying the development pro forma

    Yesterday I made a comment on Twitter about most people not understanding to what extent government bureaucracy inhibits the delivery of new housing in this city. It received a number of responses, including remarks about how development charges have also recently doubled and how this statement applies to pretty much every city out there. But there was also a comment about developers not being transparent and not properly explaining the impact to the public. In other words: please demystify the development pro forma. I thought that was a fair remark, and so this post is going to be a response to that comment.

    Before I begin, it’s important to keep in mind that most developers have investors. These investors put up most of the money required for a project and in turn they take most of the profits. However, there is typically a “promote” in place, which is just an incentive structure that pays the developer more of the profits (disproportionate to the cash they invested in the project) if they perform and hit certain return benchmarks. All of this is to say that developers aren’t usually the ones holding all of the cash (which is what a lot of the public seems to think) and they are accountable to their investors to do what they said they would do.

    Now let’s run through the costs that make up a “typical” development pro forma. For this example, I am going to assume that we’re talking about a 100,000 square foot mid-rise building; the kind that you might build and find along any one of Toronto’s Avenues. If we were doing this in real life, we would get more precise with the areas and consider gross construction area, gross floor area (city definition), and the net saleable/rentable areas. But to keep the math simple, we will ignore these differences. That’s the approach I’m going to take overall in the post. What you need to know, though, is that you have to pay to build the entire building, but you only get to collect revenue on a portion of it. That’s why the “efficiency” of a building matters.

    Land

    The value of development land is a function of what you can build and the revenue you can ultimately collect. So location matters a great deal. Based on the latest high-density land report from Bullpen and Batory, the average price of an unzoned mid-rise site in the City of Toronto is about $231 psf. So let’s assume a land cost for our project of $23.1 million. Assuming we can get land financing at 60% of the value of the land (loan-to-value), that would mean we’re putting up $9.24 million of cash (plus a loan guarantee!) and borrowing $13.86 million to start our project. At 5.25% per annum (interest-only loan), our annual interest charges would be about $727,650. From now on forward, we’re going to pay ~$60k in additional interest charges for every month that our project is delayed. Buckle up.

    You should now begin to see why time is so valuable and why government bureaucracy can be so frustrating. As a developer, you’re heavily incentivized to move things forward, whereas it can often feel like everyone around you is trying to deliberately erect roadblocks in order to slow you down and make your project more expensive to build. Oftentimes, it is because it is less risky for them to punt things down the road and not make a decision. That is not the case for us and our project.

    Hard Costs

    Onto construction (or hard) costs. As many of you know, these have risen dramatically over the last 4 to 5 years. On some of our projects, we have added over $100 psf in hard costs alone. Part of this has to do with a busy construction market and part of this has to do with new building requirements: watertight undergrounds, new Green Standards, and so on. For our project, which is on the small side, let’s assume $360 psf for a total of $36 million. This would include our direct construction costs and our construction manager’s overhead (general conditions). We should also prepare for some of the trades to decline to bid on our project because it is too small and not worth their time.

    Soft Costs

    Soft costs include everything from consultant costs and interest charges to government levies and management fees. Like everything in your pro forma, these absolutely need to be broken out line by line. Don’t be lazy here. But for the purposes of this simplistic example, we’re going to use 75% of hard costs, which works out to be $27 million (or $270 psf). When I first started out in the development business, the rule of thumb was closer to 25% of hard costs. But times have changed. Government fees, alone, can make up about 1/4 of the price of a new condo in Toronto.

    Adding up all of these costs, we’re at $861 psf or $86.1 million in costs. It’s now time to consider the revenue side. $1,000 psf seems like a nice round number, so let’s start there and assume we’re going to sell our condos for that. Typically in Toronto, the price you pay is inclusive of HST, so that liability will need to be deducted from our revenue line. It’s not a straight 13% because of the new home rebate, but the rebate also hasn’t been properly indexed since it was introduced and so the liability could still be upwards of 10%. (This is worthy of a separate blog post.) The result is $900 psf in revenue and a margin on costs that is less than 5%. No sensible developer would want to do this project. One misstep (or development charge increase) and you’re dead.

    So let’s increase our condo prices to $1,100 psf. Maybe that will work. In doing that, we get to a margin on costs that is nearly 15%. Okay, now we’re in the range. But let’s say we just got delayed by 6 months (boom, interest charges) and our hard costs turned out to be off by $15. They’re actually working out to be $375 psf because of some new tariff and because the formworkers in the city are all tied up on bigger projects and couldn’t give a shit about our cute little infill project. Now we’re offside again in terms of our margin on costs. No problem, let’s try and push condo prices a bit more. Is $1,150 achievable? Perhaps. But ideally, given the above, we would want to be at $1,200 psf just to be safe.

    This is an overly simplistic example of the math that goes into a development pro forma. But hopefully it begins to show you (1) just how many moving parts there are in a development project and (2) the kind of pricing that is required in today’s cost environment. Developers are reacting to the costs that they are being thrown and it is creating upward pressure on home prices. (See related post: Cost-plus pricing.) So far there has been enough elasticity in the market to absorb these price increases, but that may not always be the case. If you have questions about this post or disagree with any of my assumptions, feel free to leave a searing comment below.

    Photo by Marcos Paulo Prado on Unsplash

  • A catalyst for Westside development — but not yet

    A new 280 acre park is currently under construction in an old quarry on the westside of Atlanta. It’s called Westside Park. When it opens this spring (that’s at least the target), it will be by far the largest park in the city. But already there are concerns that this investment in new public space could be triggering “rapid gentrification” in the surrounding area.

    So earlier this month, the mayor’s office issued an executive order that put in place a 6-month moratorium on all new construction permits in the communities surrounding the park. The order read like this: “…refuse to accept new applications for rezonings, building permits for new construction, land disturbance permits, special use permits, special administrative permits, subdivisions, replattings, and lot consolidations for non-public projects.”

    The objective is to avoid displacement. And since new development means change, this is a way to stop change. (Don’t you just hate when things go and change?) The problem, of course, is that a moratorium on new housing doesn’t stop change and it does nothing to address the desire to live next to this new amenity. It only stymies the supply of new housing to meet this demand. (It’s also incongruent with the park investment being marketed as a “catalyst for new development.”)

    In fact, Joe Cortright (of City Observatory) and Jenny Schuetz (of the Brookings Institution) have both argued — either directly or indirectly — that the above move could actually increase displacement in the surrounding area; because the moratorium on new housing could simply redirect demand toward the existing housing stock. The order does seem to suggest that you can still renovate an existing property.

    I wonder if any studies have been done on the externalities associated with temporary housing supply moratoriums. If so, I would be interested in reading them.

  • Q4-2019 high-density land report for the Greater Toronto Area

    Bullpen Consulting and Batory Management published their Q4-2019 land insights report for the Greater Toronto Area today. According to the report, there were 36 high-density apartment land transactions in Q4-2019. The average sale price was about $111 per buildable square foot and Bullpen estimates that these future projects — assuming they go condo — will sell for just under $1,000 psf on average.

    But that’s blended across the entire GTA.

    Looking at the core of Toronto (former City of Toronto boundaries), the average price per buildable square foot was about $187, which represents a year-over-year increase of 28%. There’s also a premium for mid-rise sites. Bullpen pegs the average price of a mid-rise site in the City — unzoned but with an active development application — at about $231 pbsf. These numbers will obviously translate into much higher condo/apartment prices.

    If you’d like to download a copy of the report, click here.

  • Every building is a prototype

    Witold Rybczynski’s recent blog post about architecture’s “curious business model” gets at one of the core challenges of new construction: “Every project is, in effect, a custom job; there are no real economies of scale.” There are also no reoccurring cash flows for the architect, Witold explains, unlike a writer who might earn ongoing royalties or a business owner whose wealth will grow as the business grows.

    There are two items to discuss here: (1) The “curious business model” used in the practice of architecture and (2) the inefficiencies of construction.

    The first one is not unique to architecture. You could say the same thing about the planning and real estate lawyers who also work on new buildings. But I take Witold’s point in that even a painter’s work could appreciate in value after it’s done, whereas there’s typically no mechanism for any of this to accrue (to the architect) in the world of architecture.

    When I was young, I was told that there are two ways to make money. You can either trade your time for money or you can own assets that make you money. An example of the latter might be a farm where the tenant farmer pays you rent every month. You’re not trading your time by actually doing the farming, you just own the asset.

    This may seem obvious, but it’s fundamental. And it’s one of the reasons why, when I was in architecture school, I admired the practices of people like Jonathan Segal out of San Diego. Jonathan is one of the pioneers of the “architect as developer” approach. He simply became his own client and started building his own projects.

    Moving on to topic number two.

    Everyone in the business of building new buildings is looking for repeatable methodologies. Many have thought: How do we make the construction of buildings more like the assembly of cars? How do we create a standardized kit of parts? And that has lead to longstanding efforts around prefabrication. Today, as you know, we are also looking at how 3D printing might make this easier/cheaper.

    In some ways, that is happening. There are examples of prefabrication and panelization, and there are developers who are using this approach. (See H+ME Technology.) But for the most part, we still build on site and it’s still a messy process with lots of waste and inefficiencies. If there was a cheaper and more effective way to do it, the industry would certainly move in that direction. Eventually that will happen.

    In the meantime, we will continue building our prototypes.

    Photo by Ivan Bandura on Unsplash

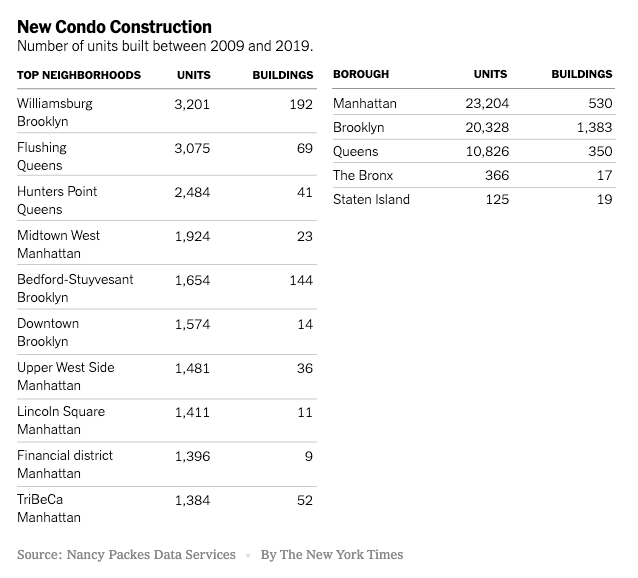
  • Number of condo units built in New York City between 2009 and 2019

    A decade of ultra luxury condos. The New York Times published this story over the weekend talking about how the luxury condo boom of the 2010s transformed New York City, and in particular Brooklyn.

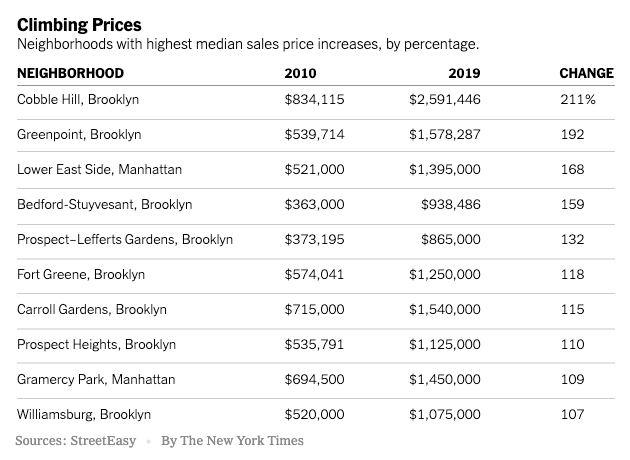
    Below are two tables from the article: (1) The number of units built between 2009 and 2019 across the five boroughs and the city’s top neighborhoods, and (2) the neighborhoods with the highest median sale price increase.

    The overarching theme is that New York built too many “super-high-end condos” geared toward global capital flows. According to one developer interviewed for the article (Gary Barnett of Extell Development), it was unprecedented.

    Apparently, the problem segment remains the $5 million to $10 million market. There’s simply too much inventory, and that has developers both delaying launches and going with much smaller (and hence more affordable) unit mixes.

    One stat that stood out for me was the new condo premium over resales. In 2011, the average sale price of a new condo in the city was about $1.15 million, which represented about a 9% premium over resale pricing.

    While it is typical to see a premium over resales (the same is true in Toronto), the average price of a new condo in 2019 rose to $3.77 million, representing a 118% premium over resales.

    For the rest of the article, click here.

  • Two-up, two-down

    Feargus O’Sullivan is doing a series in CityLab right now on the “home designs” that define four European cities: London, Berlin, Amsterdam, and Paris. The first one is on London’s classic “two-up, two-down” design, which refers to a two storey home with a living room and kitchen on the ground floor and two bedrooms on the second. It’s a simple design, but one that has supposedly endured.

    O’Sullivan argues that for many, or perhaps most in Britain, this is what a “home” feels like. It’s grade-related and there are two floors. Indeed, only 14% of British people live in an apartment, compared to 57% in Germany (a majority). This percentage is much higher in London, with about 43% of people living in an apartment. But about 25% of the population still lives in some sort of attached house.

    Home equals house. And for us North Americans, this is of course relatable. But the Germany example is a reminder that this is not necessarily universal. Attitudes toward housing are cultural. And cultures can and do change. I am seeing that happen right now in Toronto. Some of us are becoming less like the British and more like the Germans.