Daily insights for city builders, delivered every morning at 6 AM ET. I’m Brandon Donnelly — a Toronto-based real estate developer and founder of Globizen. I’ve been writing here since 2013.

  • An even longer view on home prices — this time in Amsterdam

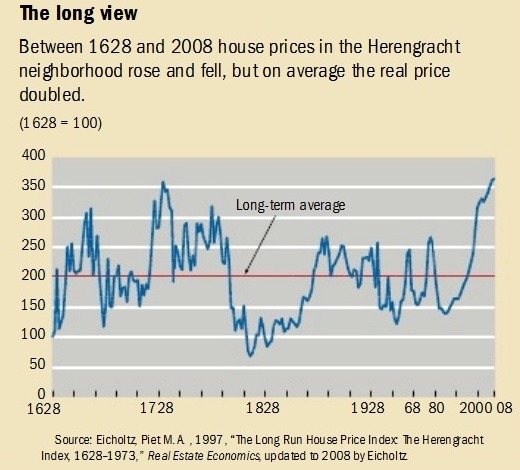
    In the comments of my recent post about Manhattan real estate prices during the Great Depression, a regular reader of this blog shared this terrific blog post (and corresponding research paper by Piet Eichholtz) about house prices along the Herengracht canal in Amsterdam from 1628 to 1973. Later it was updated to include up to 2008. It’s a long run house price index.

    Probably the first thing you’ll notice is that the index is highly volatile. Amsterdam enters its Golden Age, creates the world’s first stock exchange, and becomes the wealthiest city in the western world – house prices go way up. The tulip mania bubble pops – house prices go way down. It’s not until after World War II that prices sort of start to stabilize and increase, maybe, more consistently.

    In nominal dollars, the house price index increases 10x over the study period. But in real dollars most of that disappears. The biennial increase (that’s how the study was done) over the same period of time is just 0.5%. That translates into a doubling of house prices, which may seem quite good, except that remember it’s over a 380 year time period.
    image

    The Herengracht canal is a particularly good study because it was and has remained (or so I’m told) a desirable part of Amsterdam. This is an attempt to control for the variable that maybe some of the volatility could be explained by the area simply falling out of favor. (As a quick sidebar, the Herengracht was one of the first canals laid and dug out around the original city center of medieval Amsterdam during its Golden Age.)

    Generally, this finding is in line with one that economist Robert J. Shiller famously published a number of years ago where he argued that, when you correct for inflation, home prices actually look remarkably stable over long-run forecasts. In one study, he looked at 100 years of US home prices ending in 1990. Real home prices increased about 0.2% a year. What an outstanding hedge against inflation.
  • How technology might transform health care

    Below is an interesting podcast with venture capitalist Bill Gurley talking about how technology might transform and improve health care.

    Based on their discussion, the US spends about 17-18% of GDP on health care. In most Western European countries and in Canada, it’s about half of that.

    In Singapore, it’s only 4% of GDP and there doesn’t appear to be any demonstrable differences in terms of health outcomes.

    If you can’t see the podcast embedded below, click here.

    https://art19.com/shows/the-ezra-klein-show/episodes/5bef0efc-97ce-412b-89dc-cb5d9d476f6f/embed?theme=dark-blue

  • Manhattan real estate prices during the Great Depression

    image

    I was searching around trying to find data on long-term real estate prices and I came across a paper by Tom Nicholas and Anna Scherbina called, Real Estate Prices During the Roaring Twenties and the Great Depression.

    Here are some stats about Manhattan real estate (from the paper) that you all might find interesting:

    – In 1930, Manhattan housed 1.5% of the US population, but had approximately 4% of all US real estate wealth.

    – To construct their price indices the authors randomly collected 30 real estate transactions per month in Manhattan between 1920 and 1939. The mean price per square foot in 1929 was $6.91 (year of Black Tuesday). And the mean price per square foot in 1939 – 10 years later – was $2.29.

    – Buildings containing a store at grade tended to sell at higher prices. The authors speculate that this could be because a zoning change in 1916 made it difficult to open stores in “residential” areas.

    – Buildings with three, four and five storeys tended to sell at a discount. Six storeys or higher and the buildings generally had an elevator, which resulted in higher pricing.

    – Manhattan real estate prices reached their highest level in Q3-1929 before falling 67% by 1932. Prices remained more or less flat during the Great Depression.

    – If you bought a “typical property” in 1920, it would have retained only 56% of its value (in nominal dollars) by 1939. In fact, it took until 1960 for assessed property values in Manhattan to exceed their pre-Depression pricing.

    – An investment in the stock market index during this same time period, 1920-1939, would have outperformed real estate by a factor of 5.2x.

    Much of this probably seems hard to believe given the market today. Imagine waiting 40 years for the value of your property to come back.

    Photo by jesse orrico on Unsplash

  • Jeff Bezos’ regret minimization framework

    Who better to talk about on Black Friday than Amazon’s Jeff Bezos. Supposedly he’s now worth $100 billion.

    I just finished watching this short 60 Minutes clip about Amazon from 1999. If you can’t see it below, click here.

    [youtube https://www.youtube.com/watch?v=fjjUOemW-_Q?rel=0&w=560&h=315]

    Amazon was founded in 1994, so this was 5 years in. Already the company had gone public and had a market cap of somewhere around $30 billion.

    Now, keep in mind that this was right in the middle of the dot com bubble, but already Bezos was a billionaire on paper.

    What is clear from the above clip is just how obsessed Bezos was and is on the long game (”I don’t go in for carpe diem”) and on his customers. Here he is worth quite a bit, but driving around in a Honda Accord. 

    Bob Simons, the interviewer, pokes fun at him a few times for his reluctance to spend money. But Bezos says that it’s all about spending money on things that matter to customers and not spending money on the things that don’t.

    That’s customer obsession.

    P.S. The title of this post will make sense once you watch the video.

  • Beware of scam ICOs

    There’s certainly lots of buzz these days around the Blockchain and cryptocurrencies. 

    Some of it is negative. 

    Here is a recent New York Times article talking about how celebrity-endorsed “initial coin offerings” have created a new gold rush. Most of these ICOs are scams.

    But some of it is quite promising. 

    Here is a brief summary of how the Blockchain is being leveraged for the real estate industry. Many jurisdictions are already using it, or experimenting with it, for their land registries.

    I’ve been writing about Bitcoin sporadically since about 2013. But I really should spend more time getting deeper into this world. Many believe it will underpin the next wave of innovation in the tech space.

  • The worst on-time performance of any major transit system in the world

    I was recently with some New Yorkers and we got on to the topic of their subway system. I made a comment about how extensive their network is and how their express trains work so well for traveling further distances. 

    They responded by basically saying: “Yeah, it’s great, when it works.” They then went on to tell me that most of the time they just use Uber to get around the city because the subway has become so unreliable.

    Admittedly, I don’t use the NYC subway system enough to comment on its declining performance. But this recent New York Times article describes it as an utterly failing system.

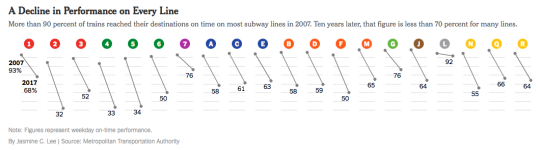
    Here is a diagram from the article that shows performance on every line (2007 to 2017), measured as a percentage of trains that reach their destinations on time (i.e. less than 5 minutes late):

    image

    In 2007, more than 90% of trains reached their destinations on time. Today, the weekday average is around 65% and some of the lines are in the 30s. This is the worst it has been since the 1970s when NYC was almost bankrupt.

    Apparently this also awards NYC’s subway the title of the worst on-time performance out of the world’s top 20 biggest systems.

    I suppose one of the lessons here is that subway lines on a map will always be far sexier than the nuts and bolts of maintenance, performance, and ridership. But we can’t forget the nuts and bolts. Maybe those are the most important parts.

  • Saks x Dim Mak

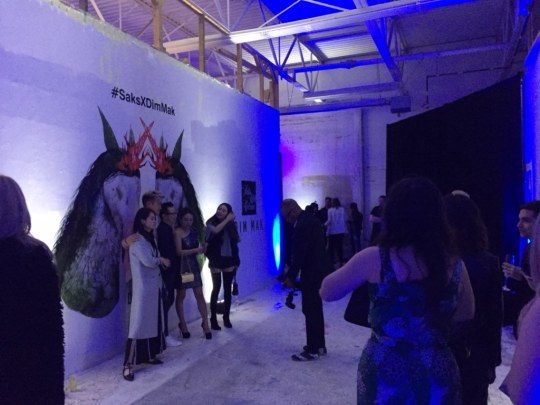
    Steve Aoki was in Toronto today for a collaboration with Saks Fifth Avenue – namely the launch of his fall/winter Dim Mak Collection. 

    The after party was at Junction House (the pre-development version). Here is a photo:

    I actually wasn’t there (because I’m fighting off some sort of cold), but a friend sent me this photo. 

    It’s such a great space for events and production. It used to be an artist studio, but they moved out because they outgrew the space.

    If you have a need for a large warehouse space, you can actually rent it by visiting here.

  • People you may know

    If you’ve ever wondered how Facebook figures out all of the people you may know, here is some reading material. 

    The short answer is that Facebook doesn’t just know the things you’ve told it about yourself, it also knows what other people have told it about you. 

    One of the ways in which this is done is through its so called “shadow profiles". These are profiles that get created when other people share information about you with Facebook. 

    For example, you may not want to share your work email address with Facebook, but if it’s sitting in someone’s phone and that person decides to share his/her address book with Facebook, then it could show up in your shadow profile.

    And if there’s a common data point, such a phone number, then Facebook can fairly easily link that work email address back to you and start suggesting people from your work that you may know.

    The scary part, of course, is that Facebook is getting your information without you explicitly sharing it with them. It could be coming from that person you gave your business card to at the bar.

    It goes to show you just how fierce the competition is for our attention. It may be an assault on our privacy, but more Facebook connections means a higher likelihood that we’ll stay engaged on the platform.

    Over the past year I have been growing increasingly intolerant of this demand for my time. Slowly but surely I have been turning off all nonessential notifications on my phone. 

    Very few now remain, which is why if you’ve been trying to reach me on Facebook, WhatsApp, LinkedIn or some other platform, and I’m not responding, it’s because there’s a good chance I’m not seeing the notifications.

    And let me tell, it feels liberating.

  • End of the automotive era

    Bob Lutz is a former vice chairman and head of product development at General Motors. Recently, he had this to say about the future of the auto industry. 

    Here are a couple of powerful snippets:

    It saddens me to say it, but we are approaching the end of the automotive era.

    The auto industry is on an accelerating change curve. For hundreds of years, the horse was the prime mover of humans and for the past 120 years it has been the automobile.

    Now we are approaching the end of the line for the automobile because travel will be in standardized modules.

    Everyone will have five years to get their car off the road or sell it for scrap or trade it on a module.

    Bob is 85 years old. This is somebody who spent his entire life in the auto industry telling us that the old model is now done. 

    It reinforces something that I wrote about here, where the “end of the automotive era” was pegged at around 2021. 

    And it is part of the mental model that I have started relying on today for decision making.

    Photo by Alessio Lin on Unsplash

  • Learning from King Street

    Toronto is now a week into the King Street Transit Pilot.

    It’s still early days and transit guru Steve Munro hasn’t yet published any before and after route performance. He will. But already the sentiment seems to be clear: This shit is working. There are many recounts of people’s commute times being more than cut in half. 

    As somebody who walks this stretch of King every day, this isn’t surprising to me. There has been a dramatic reduction in the number of cars on the street.

    What is perhaps surprising is that none of the surrounding streets seem to be any busier. I would like to see the data, but it feels as if most of the cars have simply disappeared. Are more people now taking transit? Has this been your impression?

    Of course, the pilot isn’t perfect. What is not working are the signs that tell drivers they can’t drive through most of the intersections (only turn right). The circular green lights confuse them or they simply don’t care. 

    There have been suggestions for better signals, such as this one:

    image

    And if the pilot in its current incarnation does stick, I am sure there will be many additional improvements like this one made. But even at this early stage, Toronto is calling the pilot a “transit miracle.”

    When City Council approved the pilot in the summer it had a preliminary cost estimate of $1.5 million. (Figure excludes the lost parking revenue associated with removing approximately 180 on-street parking spaces).

    This is a relatively minuscule amount considering it has had an immediate impact, basically overnight, on the commute times of the 65,000 or so people who use this line every day.

    And it feels even more minuscule when you consider that our Scarborough Subway extension is expected to cost $3.35+ billion to build and only service around 64,000 people a day when you look far into the future – 2031 to be exact.

    The lesson here on King Street should be that light rail and surface transit routes can move lots of people very efficiently and cost effectively when you empower them to do precisely that.