Daily insights for city builders, delivered every morning at 6 AM ET. I’m Brandon Donnelly — a Toronto-based real estate developer and founder of Globizen. I’ve been writing here since 2013.
And I immediately thought of this TED Talk by Roman Mars. For those of you who don’t know, Roman is the creator of 99% Invisible and a great lover of well-designed flags. His general rules of thumb are to keep things super simple and to use meaningful symbolism. And I’m fairly certain that he knows what he’s talking about because, in his talk, he refers to the Canadian flag as the gold standard for flags.
In the case of Utah’s new flag, the symbols are this. The blue at the top is meant to represent Utah’s wide-open skies and lakes. The white in the middle represents its snowy mountains (of course). The red stripe is meant to represent Southern Utah’s red canyon landscape. The hexagon is meant to reference a honeycomb. And finally, the beehive is there because, well, Utah is the beehive state.
Utah has long enjoyed this reference to beehives. Supposedly, it was early pioneers who started throwing around this reference because they believed it symbolized working together, perseverance, and overall industry. And that’s why the state’s official motto is, “Industry.” So I’d say that they used/kept the right meaningful symbolism.
Though when I first saw the new flag, I immediately wondered whether the hexagon and honeycomb could have been made just a little simpler. Was the yellow fimbriation, for example, really needed within the blue hexagon? But the more I look at it, the more I like it and the more I think that Roman Mars would be happy with how this turned out. What are your thoughts?
One of the things that you’ll notice on real estate listings in France is an Energy Performance Diagnostics (EPD) rating. In French, it gets reversed, and so it’s a DPE (diagnostic de performance énergétique). What it tells you is how much energy the dwelling (or building) consumes and how much greenhouse gas it emits. And it is a requirement on all real estate listings and for all dwellings, except those that are occupied for less than 4 months per year. The output of this diagnostic is a rating from A (best) to G (worst).
According to FT, this is how primary residences in France rank today:
Less than 5% of homes are rated A and B (the most energy efficient). And many more are rated G and F. Beyond just being energy inefficient, this is potentially a problem because there are penalties and restrictions for the lowest rated homes, one of which is that you are not allowed to rent out the property. Right now and as of January 1 of this year, the upper consumption limit is 450 kWh per square meter per year. Go above this and the home becomes ineligible.
January 1, 2023: Rental ban on properties with G+ energy label
January 1, 2025: Rental ban on all properties with G energy label
January 1, 2028: Rental ban on all properties with F energy label
January 1, 2034: Rental ban on all properties with E energy label
Now here’s what this is thought to mean for overall rental supply:
By 2028, 5.2mn homes rated F and G, or 17 per cent of total housing stock, will become ineligible for rental. By 2034, all E properties will also be excluded, amounting to about 40 per cent of homes.
This raises an interesting question: Is it more important to have energy-efficient homes or to have greater overall supply? Now obviously the goal and ideal scenario is both; lots of affordable homes that are also energy efficient. And presumably, one of the objectives of this rental ban is to stick/carrot owners into investing in energy measures. But it’s not exactly obvious as to how many owners will be able to renovate their homes in time, and how many homes will become ineligible for rent. This will be an interesting policy to watch as it plays out.
I have written about Bright Moments before. They are a digital art company exploring the intersection of NFTs and real-world experiences. It started as a popup gallery in Venice Beach California, where artists could show new work and where collectors could buy IRL. They then created their own pixel art collection called CryptoVenetians. It included 1,000 different people-centered NFTs by artist QianQian. Since then, they have gone on to host events and create new CryptoCitizen collections in New York, Berlin, London, Mexico City, Tokyo, and Buenos Aires. And this week they were in Paris.
Their end goal is to create a complete collection of 10,000 NFTs, most of which are tied to a specific city. (The only one that isn’t is their CryptoGalacticans collection.) What’s obviously great about this approach is that it’s a way to promote digital art and onboard new users into the crypto space. They are literally going around the world, throwing parties, and saying “look how cool and fun this whole crypto thing is.” At the same time, it also links the digital and the physical, which I believe is fundamental. We’re social beings and web3 will never change that.
The other interesting thing about Bright Moments is that they are structured as a decentralized autonomous organization (or DOA). That’s like a company, except that governance is distributed to its tokenholders and it’s all managed on a blockchain. But it still operates as a company and it can raise money like one too. In 2021, Union Square Ventures invested 500 ETH into the DOA through a blockchain transaction that would naturally be public if you cared to look it up. Based on today’s spot price of about CA$4k per ETH, that was a CA$2 million investment.
In the case of Bright Moments, its tokenholders are the people who own a CryptoCitizen. These are the people who get to vote on how the organization is run. They can also earn money if they do things like host a community dinner or organize a local meetup, with the idea being that, as an organization, you want to encourage this sort of bottom-up participation and innovation. I find it fascinating to watch this new governance and entity structure emerge, and it will only continue to evolve.
I’ve been following Bright Moments more or less since they dropped the CryptoVenetians. I thought about jumping in then, but I figured I would wait to see if there would be a CryptoTorontonian. That would obviously be my number one choice. But once they announced their final list of cities, and Toronto wasn’t on it, I grumpily decided I would instead wait for a CryptoParisian. And since this week was Paris, it was time.
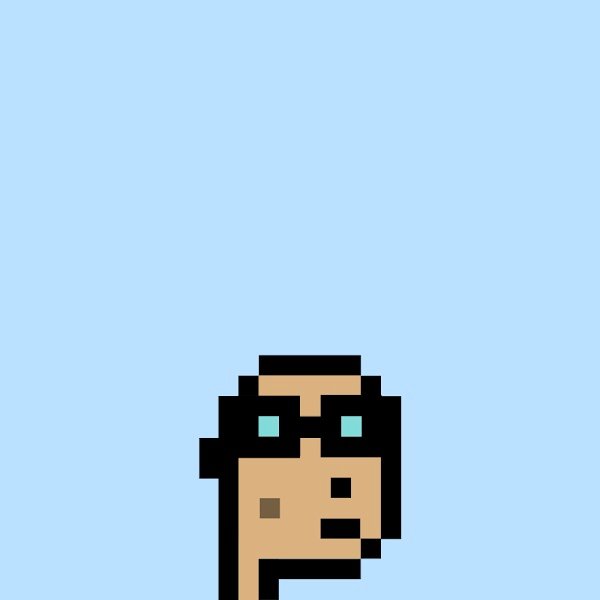
I now hold CryptoParisian #112:
I like that it has the Pont Neuf and that the human is wearing sunglasses.
This means that I now have a small ownership stake in the Bright Moments DOA. So presumably I’ll soon have a say in important and serious matters! It also means that when they launch their final CryptoCitizen collection in Venice, Italy this spring (nice work going full circle here), there is a chance I might get airdropped a CryptoVenetian. It’s a random process, so whatever. I also know that it’s easy to look at this pixelated Parisian and think, “WTF, Brandon.” But something new is building here. And I’m sure that all of the folks who were in Paris this week can testify to that.
Some four years ago, people were talking about the possibility of New York City being dead. But of course that was nonsense. Last week, New York City published the initial findings of its housing and vacancy survey and the key takeaway is that the city’s vacancy rate dropped to 1.41% last year (2023). This is a drop from 4.54% just two years ago and the lowest measurement since 1968. It’s also even worse at more affordable rent levels:
The problem, as described by the city, is a supply-demand imbalance. Over the last two years, the city’s net housing stock grew by about 60,000 homes (~2%). This is, apparently, pretty good compared to recent years/decades; but it wasn’t nearly enough given that the city added 275,000 new households. This is the opposite of dead, and it’s not going to be addressed by just doing things like restricting short-term rentals.
We have a structural delivery problem and New York City is not alone in facing it.
Sometime before the Paris 2024 Olympics this summer, the International Olympic Committee (IOC) is expected to announce who will host the 2030 and 2034 Winter Games. Right now, the two frontrunners are thought to be the French Alps and Salt Lake City/Park City — I think respectively.
Obviously these are two fantastic winter locations. But one of the things that the local committees need to do before they can secure the games is show the IOC that they have enough hotel rooms on hand. More specifically, they need 24,000 rooms reserved for 33 nights. This covers 17 nights during the games, 14 nights before, and 2 nights after.
Most of these rooms, about 10,000 or so, will go to journalists.
I didn’t fully appreciate — or I just didn’t think about it — that this was something that needed to be done 6-10 years out. Because right now there is a human running around try to lock up these rooms in advance of the decision this summer.
According to the Salt Lake Tribune, they’re already at 85% of the requisite 24,000 rooms. Though some of these rooms have yet to be built and some of them reach into neighboring Wyoming, which apparently isn’t an atypical distance when it comes to meeting this accommodation requirement.
For obvious reasons, I’m rooting for Utah here. I really want them to get the Winter Games.
Rental housing in France is both heavily regulated and supported through dedicated public funds. Here’s a high-level overview of what that means (via this 2021 Brookings case study by Arthur Acolin):
Homeownership rates in France went from 35% in 1954 to 56% in 2001
As of 2018, 58% of French households own, 40% rent, and the remaining 2% supposedly get free housing from either their employer or a family member
Not surprisingly, younger households are most likely to rent (the figure is > 60% for people aged 18-29)
Household size seems to play a major factor in how likely people are to live in public housing
France has some 4.5 million public housing units and 17% of all households live in them (which represents about 43% of all renter households)
Within the unsubsidized rental market, 93.5% of households live in homes owned by individual investors (this is as of 2013) and only about 3.5% live in homes owned by institutional investors
This is pretty typical of Europe, where multi-family isn’t an established real estate asset class like it is in North America; so for those of you who like to hate on individual condo investors, check out France
In the decade between 2010 and 2020, 28 metro regions in France adopted some form of rent control and, in a few markets, like Paris and Lille, there are also maximum rents that can be charged for specific housing types
If you’re interested in rental housing, Brookings also has articles covering the US, Germany, Spain, Japan, and the UK. They can be found here.
Last week we spoke about how many businesses don’t want to own their own real estate, but that some do. We then spoke about Prada’s recent acquisition of 720 and 724 Fifth Avenue for $835 million. However, they’re not the only ones. According to New York’s The Real Deal (thank you John Bell for the article), last year saw the following transactions:
Swiss fashion house Akris bought a property from SL Green for $40.6 million
Japanese coffee retailer Geshary bought a property on Fifth Avenue from the Riese Organization for $38 million
And Dyson bought a building in Soho for $60 million
Now, some, or a lot of this, is strategic. New York is New York, and global brands need to be there. Another part of this is that there was less competition last year. Fewer real estate companies wanted to buy retail and office buildings, and so end users seem to have stepped in at what they presumably saw as favourable prices.
But it’s also not totally foreign for retailers to want to own their own real estate. Perhaps the most famous example is McDonald’s, which owns its own real estate and then leases it out to franchisees. Though as I alluded to last week, it’s important to know what business you’re ultimately in. And McDonald’s knows it’s in the real estate business.
We have spoken before about how hotel brands don’t typically own their real estate. But the same is also true of many other businesses. And one common reason for this is that it ties up a lot capital that could be otherwise deployed in the core business. If, for example, you’re in the business of producing exclusive handbags, it usually makes sense to spend your excess cash on making better handbags. And if you find that you’re actually making more money on real estate, then it could be a sign that you’re in the wrong business.
There are, however, instances where owning your own real estate may make the most sense. Maybe you have an irreplaceable location that you want to secure for the long term. And so there’s real strategic value. Or maybe you keep having annoying legal fights with your landlord and you just want to get back to focusing on luxury handbags. There are other motivating factors to consider here, but these two seem to be behind Prada’s recent acquisition of 724 Fifth Avenue in New York.
Prada has had a flagship 5-storey retail store at this location since 1997 (and most recently was paying US$22 million in rent). In December, they announced that they had acquired the entire 12-storey building for US$425 million. (That works out to be about $5,395 psf on the gross building area!) And then shortly after, they announced that they had acquired next door — a hard corner — for another US$410 million (total US$835 million).
All of this makes the deal one of the largest in New York last year. But was it a good deal? I would need some more information to answer from a quantitative real estate perspective. But if I’m Prada, I know that I need to be on Fifth Avenue for the foreseeable future. And now I get access to a hard corner and I no longer have to deal with my landlord. These are clearly strategic things. Last year was also a pretty good time to be buying retail/office buildings with all cash, which is what Prada did.
There are three resorts in the United States that do not allow snowboarding. They are: Deer Valley and Alta in Utah, and Mad River Glen in Vermont. New York-based Extell is also developing a new resort next to Deer Valley that was previously known as the Mayflower Resort. For a while, it was up in the air whether they would allow snowboarders, but this past summer it was announced that it will become part of Deer Valley and that their snowboarding ban will remain firmly in place.
As a snowboarder, I’m not overly fussed by this. There are, of course, lots of other places that will welcome my kind. But I do think it’s both interesting and worth poking fun at. It speaks to the tribal-like nature of humans. I get down the mountain on this device and you get down the mountain on that device. So we are fundamentally different humans. And I do not want to associate with you. At the same time, I do respect the ability for private resorts to make their own decisions. And this seems to be what their paying customers want.
But what about if the resort happens to be on public land? Does that make things any different? Deer Valley sits on land that is privately owned; whereas Alta sits on land that is owned by the National Forest Service. Which is why in 2014, a bunch of cantankerous snowboarders sued the resort, claiming that its ski-only policy violated the 14th Amendment to the Constitution. I’m not a lawyer, but I am told that this is typically used in cases involving discrimination.
Alta ultimately won the case. They argued that even though the land they sit on is public, their lifts are still private. And so they get to decide who uses them. I guess that’s fair. But at the same time, this technically means that snowboarders are allowed on the mountain, they just can’t use any of the lifts. I tried to confirm this fact with Alta on X the other day, but they have yet to respond.
Snowboarding is a relatively young sport. It grew massively in popularity during the 1990s (which is when I switched over from skiing), and so its participants tend to skew younger (my assumption). This is probably why fancy resorts like Deer Valley don’t feel the need to cater to them. However, young people tend to both grow up and, you know, make more money. And so at some point — when there’s a real business imperative — we may find that people suddenly change their minds.
If you’re trying desperately to sell luxury condominiums at the base of a resort and if snowboarders keep showing up at your sales office, for how long will you continue to say no to their money?
Montréal had its first snowstorm of the season this week, and if you look on X, you’ll find images and videos like these:
Interesting how people project based on wherever they're from. No one could come to central Montreal in the winter and not see lots of cyclists. Not the same volumes as summer but it's still common and visible. pic.twitter.com/wpntL8QzHY
What’s remarkable is the number of people who, at least from these tweets, continue to cycle in the winter. In fact, in the above video, there looks to be more bikes on the road than cars. Plowed lanes certainly help!
According to the city of Montréal, about 80% of the network is maintained for year-round use (717 km of its 900 km network). But I’m sure that there are a lot of people who still can’t imagine anyone wanting to cycle in these conditions. So what is the actual winter usage?
Thankfully, Montréal has bike counters. 55 of them to be exact. And all of the data can be viewed, here. The busiest location is Saint Denis and Rue des Carrières. This falls within their Réseau Express Vélo (REV) network, which is a series of protected lanes intended to do what the name suggests.
The daily average for this counter is currently 4,403 riders, but the summer peak looks to be closer to 10,000. And this year, it has seen close to 1.5 million rides in total. This is a significant number. I mean, imagine 1.5 million more car trips on the road.
Looking at yesterday’s data, the daily count was 1,292. If you very crudely divide this by my 10,000 summer peak estimate, you get to around 13%. And this happens to line up with what seems to be the city’s generally accepted winter cycling retention ratio.
Not surprisingly, fewer people want to cycle in the winter. But the number is not nothing. If you multiple 1,292 cycling trips by 120 days (roughly December to March), that’s still over 150,000 trips (I know, I didn’t account for weekends). On top of this, the city’s winter cycling retention rate appears to be increasing.
So just because you may not want to cycle to work in the winter, it doesn’t necessarily mean that others feel the same way.