
August 21, 2025 · View original
RBC published a special housing report this week where they argued that, “Canada isn’t in a housing starts slump — Ontario is.” The report is based on new figures from the Canada Mortgage and Housing Corporation that show Ontario lagging behind the rest of the country when it comes to new homes.
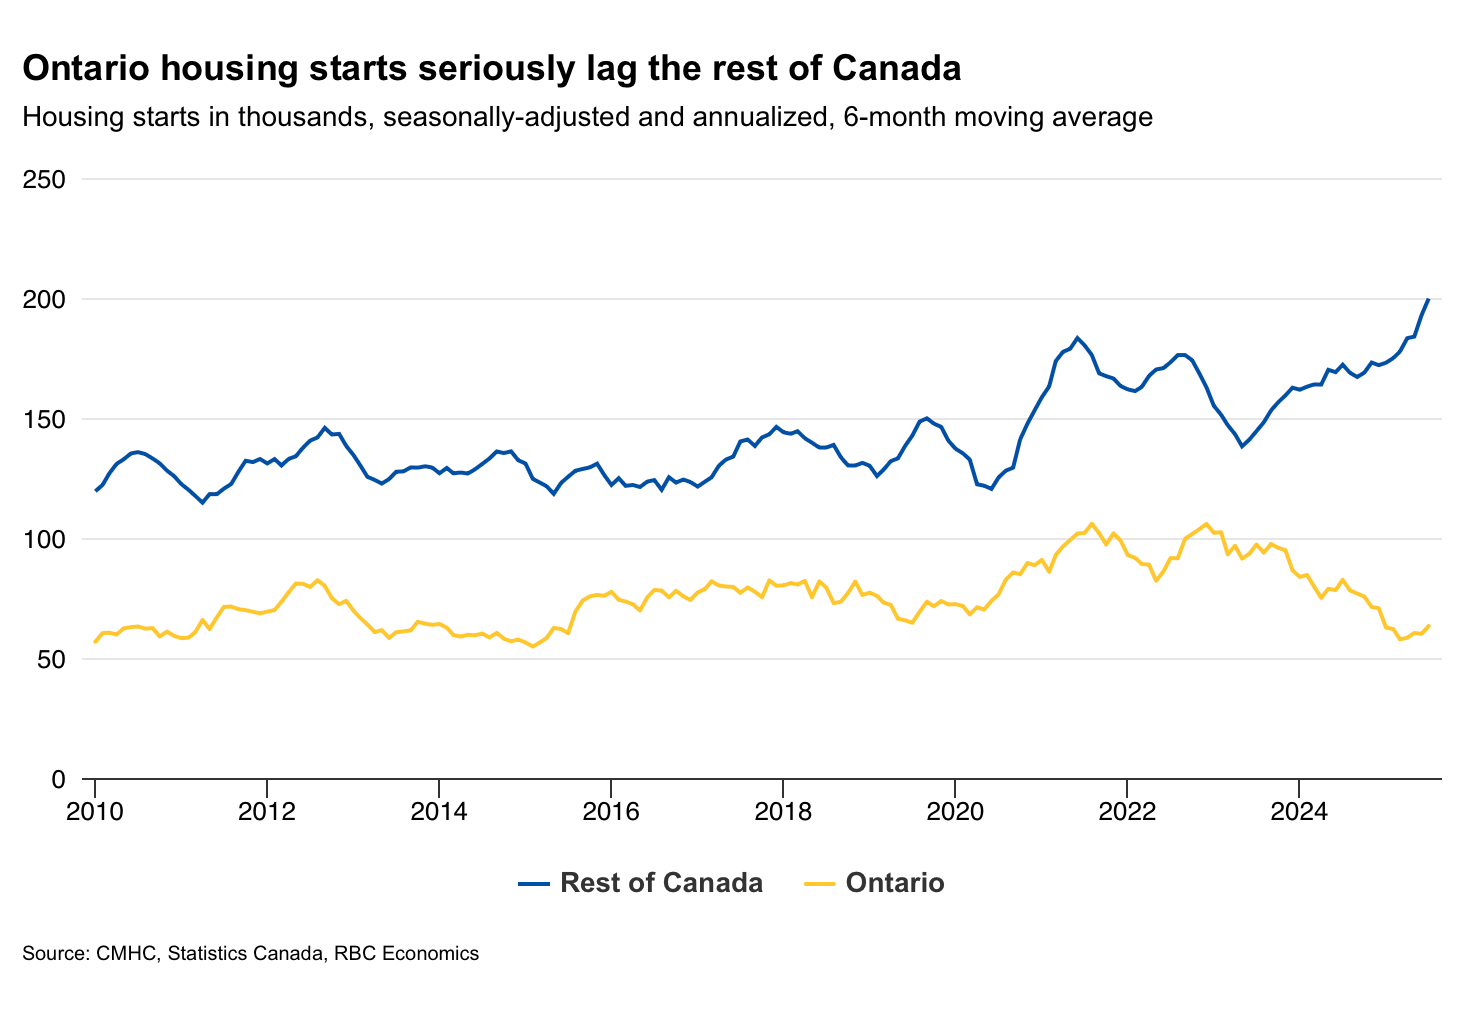
The reason for this is the paralysis of the pre-construction condo market in the Greater Toronto Area, which, up until recently, has been the biggest contributor to new supply — both when it comes to for-sale homes and for-rent homes. (This July rental housing report by BILD estimates that about 39% of all condominiums in the GTA were rented out as of 2022.)
My favorite chart from RBC is the one below, which overlays Toronto condominium starts with pre-construction sales from 18 months earlier. Naturally, the two are pretty closely correlated. Sales beget starts. What this tells us is that, at this point, condo starts are going to remain depressed until at least 2027.
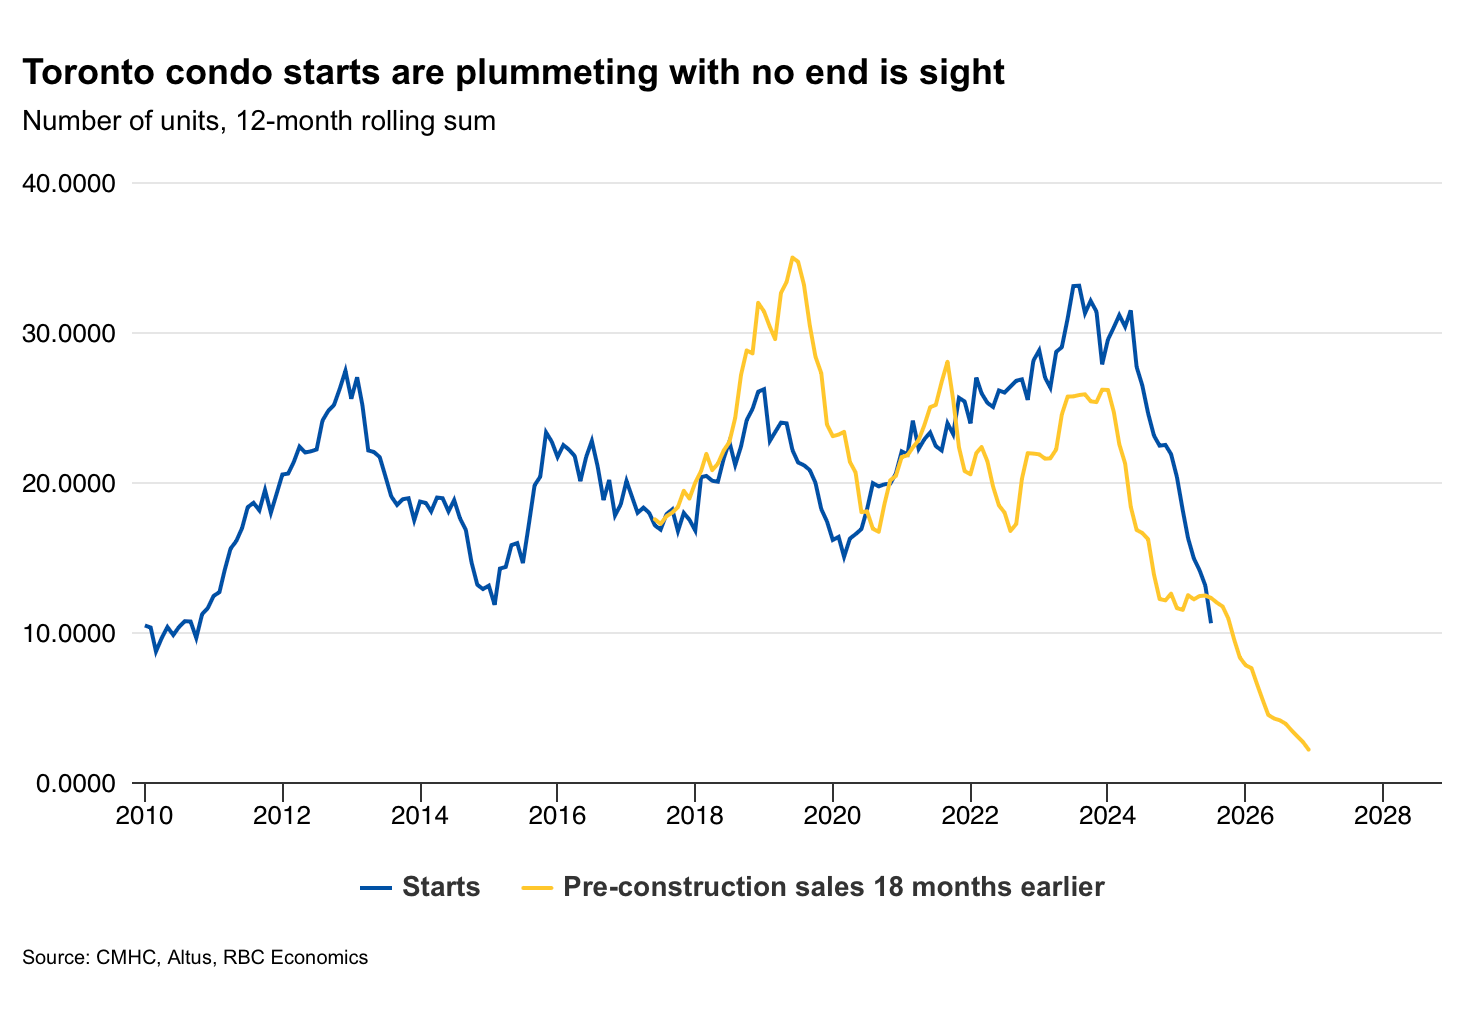
But in reality, starts are likely to remain depressed for even longer. The market still needs to absorb the current pipeline of projects under construction. I have said before that this could take another two years. And if that’s right, we could be into 2029-2030 before condo starts turn around, given the lag between sales and starts.
Some of this supply will, of course, convert to purpose-built rental. But I suspect the conversion rate will end up much lower than most people are currently hoping. Only a minority of projects underwritten as condominiums will be able to make the switch. By default, this means we will eventually enter a period of severe undersupply.
But as Robert Hogue says in his RBC report, “the full impact of the current slowdown in housing starts won’t be felt for years in Ontario.” And this is absolutely true. It’s an insidious problem right now. We currently have more supply delivering than we have buyers and renters. But just wait. It’s coming.
Leave a Reply