Daily insights for city builders, delivered every morning at 6 AM ET. I’m Brandon Donnelly — a Toronto-based real estate developer and founder of Globizen. I’ve been writing here since 2013.

Tag: rental apartments

  • Rental apartment expansion in Detroit

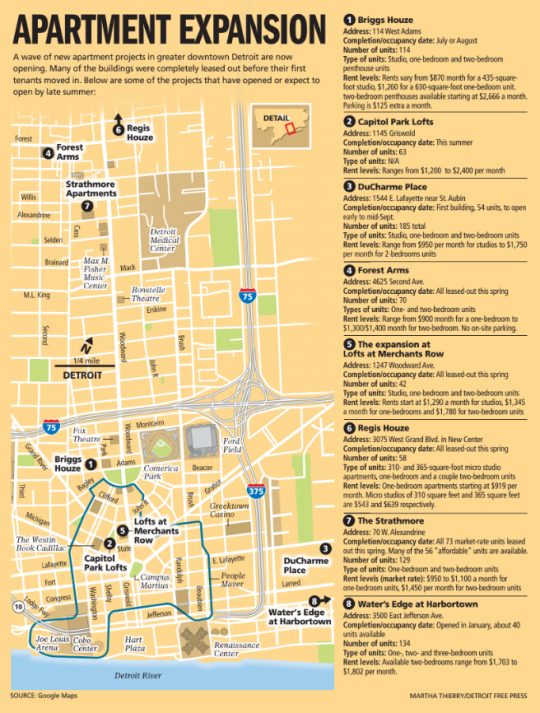
    The Detroit Free Press recently published a summary of some of the new rental apartments coming online in and around downtown Detroit. Here’s the map that they published along with their piece:

    image

    Based on this article, demand is outstripping new supply and rents are starting to push above $2 per square foot. This strikes me as a solid number given that there are also for sale lots/houses in the city going for $10,000.

    Going back to some of the posts I have written about rental apartment development in Toronto, you might remember that $3 psf is roughly our magic number given current cost structures.

    In some special circumstances you might be able to get a project off the ground with rents closer to $2 psf, but that’s an exception to the rule. There are many areas in the Toronto region with $2 psf rents and few, if any, new rental apartments.

    But Detroit is obviously a different city, as is every real estate market.

    Land would be cheaper. Many of these new rental apartments are conversions of existing buildings (which were probably bought for cents on the dollar). And I wouldn’t be surprised if there are tax abatements and other incentives to encourage more development. 

    I also wonder if people in the city aren’t being at least partially drawn to multi-family buildings because of the safety and security benefits. That’s something that certainly came up when I was in Detroit last weekend.

    Regardless, this is a good news story for Detroit, which is not always the story you hear people telling of the city.

  • Affordable housing and the economics behind developing new rental apartments

    light trail in concrete jungle by Tassapon Vongkittipong on 500px.com

    https://500px.com/embed.js

    In most big cities around the world, there is a pressing need for more affordable housing. We know that inclusive cities make for better cities. But from San Francisco to Hong Kong, you always hear people talking about how expensive housing is.

    So why is this such a difficult problem to solve?

    Part of the problem, I think, is that many people don’t understand the economics behind building a new building. Oftentimes I hear people say that because developers make so much money, they should just build more affordable housing. Done. Simple.

    But things are not that simple.

    To illustrate my point, let’s walk through the thought process for developing a new rental apartment building.

    In its simplest form, developers are concerned with: revenue – costs = profit. And since many of the costs associated with building a new building just are what they are, it all starts with revenue, which in our case would be rents.

    To build a new rental tower in Toronto, your rents typically need to be at least in the high $2′s per square foot per month. Otherwise the economics don’t work. But to make the math simple, let’s say you need $3 per square foot in rent. That means a 1,000 sf apartment would rent for $3,000 per month.

    That’s not cheap. There are only so many people who can afford these kinds of rents and only so many areas where you can command these kinds of rents, which means there are only so many areas in Toronto where new rental apartments will be built by the private sector.

    If the rents instead happen to be $2 psf – meaning that same 1,000 sf apartment now rents for $2,000 per month – then for-profit developers will not build (barring any unique deal circumstances). Even at $2.50 psf / $2,500 per month, it would be difficult to make the numbers work here.

    And by the numbers, I am talking about tight returns that really only start to make sense in our environment of record low interest rates. Which means that when interest rates start to rise (pushing cap rates up), it may not even make sense to build rental apartments when the rents are in the high $2′s per square foot. This is particularly true if you’re competing against condo developers to buy the land. They can afford to pay more. 

    In this scenario (of rising interest rates), many real estate firms might simply opt to buy existing assets instead of taking on the risk of building anything new. Now all of a sudden your supply of new market rate apartments (not to mention affordable apartments) has dried up. Remember, it’s been decades since Toronto built rental apartments at any sort of meaningful scale.

    It’s for reasons like this that Vancouver launched a program called Rental 100. In a nutshell, it helps to reduce the “costs” variable in the equation mentioned above so that developers are able to meet minimum project returns and build more rental buildings. They do that through things such as reduced parking requirements, additional density, development charge waivers, and so on.

    In some ways, these items are subsidies. The city is giving up revenue that it could have otherwise collected from a developer building, say, a condo. But in other ways, they are freebies. The city could be unlocking development sites that may have otherwise not been developed. In which case it’s not really forgone revenue.

    Vancouver’s Rental 100 program is a market rental housing policy. But there’s no reason that similar thinking couldn’t be applied to create an affordable rental housing policy. It has been done and is being done in many cities.

  • America really is building very few condominiums

    On my way back from Philadelphia
    this past weekend I wrote a post called, The
    Philadelphia (real estate) story
    . It was about how opposite the market is
    in Philly compared to Toronto.

    After writing that post and
    because of a discussion in the comment section, I started thinking about condo
    vs. rental apartment development across the US. Because unlike cities such as
    Toronto and Vancouver, it struck me that – outside of maybe New York and Miami
    – most U.S. cities are really not building a lot of for sale condos. And if
    you’re from Toronto or Vancouver, I bet that feels odd to you.

    But what exactly is that number?

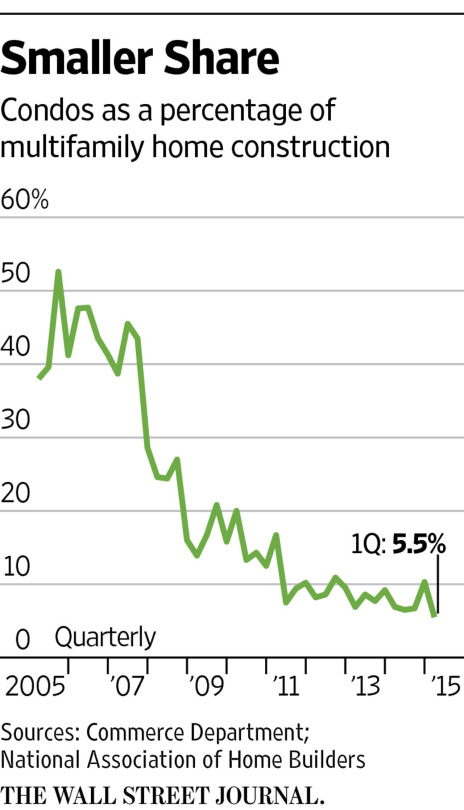
    As of the first quarter of 2015, condos as a percentage of all new
    multifamily (apartment) construction in the US was only 5.5%. That’s a tiny number and is down from
    over 50% before the Great Recession, which means most
    cities in the US really are building mostly rental. Last year the US built 264,000
    multifamily units across 11,000 buildings
    .

    So why is that happening?

    There appears to be a number of
    factors, according to a
    recent article in the Wall Street Journal
    .

    There’s a supply side
    constraint:

    Another obstacle cited by developers: construction loans. Matt
    Allen, chief
    operating officer of the Related Group, a developer based in Miami, said he can
    get a construction loan for roughly 75% of the cost of building an apartment
    complex. But lenders will cover only 50%, on average, of a condo complex’s cost
    because of the greater risk, he said.

    There’s a demand side
    constraint:

    As a result, the Federal Housing Administration, which
    backs mortgages made to low-wealth buyers, tightened its lending standards in a
    series of moves from 2008 to 2012. Under the new rules, in order for the FHA to
    insure mortgages in a given condo complex, at least half of the units must be
    owner-occupied and no more than half can be FHA-insured, among other
    requirements. For condo projects under development, at least 30% of units must
    be under contract for sale before the FHA will start backing mortgages there.
    Mortgage giants Fannie Mae and Freddie Mac tightened
    their standards as well.

    And there are macroeconomic
    factors:

    On the entry-level end, tepid job growth early in the
    recovery and the younger generation’s affinity for flexibility have fueled
    demand for rentals. Apartment rents are up nearly 16% since 2010, according to Reis Inc.

    Notwithstanding
    the above, could this be a post-recession policy pendulum that has swung
    too far in one direction?

  • The Philadelphia (real estate) story

    Real estate is a local business. And this weekend in Philadelphia really reminded me of that.

    Here’s what I mean.

    The real estate story in Toronto is condos. We’re buildings lots and lots of condos. When my friend from Chicago recently visited Toronto for the first time, he told me that it feels very similar to Chicago, except that we have modern glass condo towers going up everywhere and they don’t. That’s our story right now.

    Low-rise housing in Toronto is becoming increasingly unaffordable (the average price of a detached home is well north of $1M) and so high-rise condos are now what many people can afford. When young people in Toronto talk about buying their first place, that now usually means a condo.

    But that’s not the story in Philadelphia.

    In Philadelphia, you can buy a 1,600 square foot, 2 storey, 2 bedroom rowhouse in a respectable neighborhood for sub US$400,000. And in speaking with my friends in Philly this weekend, that’s what young people are buying.

    This doesn’t mean that Philadelphia isn’t building new high-rise condos and apartments. It is. Obviously nowhere near as many as Toronto. But it is building. Far more than when I lived there before the Great Recession.

    However, the condo market is typically more upmarket. The target market isn’t so much first time buyers and the mass market; it’s more people who want full floor apartments in Rittenhouse Square. (I’m exaggerating only slightly.)

    Philadelphia is also building more rental towers than condo towers. (Rental has only recently become fashionable again in Toronto.)

    I’m guessing that a lot of this has to do with the fact that Philadelphia draws in a lot of transient students and academics each year. In fact, the most noticeably changed area from when I lived in Philly was University City. That’s the area that houses the University of Pennsylvania and Drexel University.

    So there seems to be strong demand for new rental housing in the city. I’m told vacancies are very low. But when it comes time to buy, young people don’t look to condos like they do in Toronto. They are looking mostly to rowhouses.

    This is interesting to me because it’s the exact opposite of Toronto. In Toronto, low-rise is expensive and so lots more people are buying high-rise. In Philadelphia, high-rise is expensive and so people are buying low-rise.

    I guess that’s why they say real estate is a local business. What works in one city may not work in another.

  • 11th Annual Land & Development Conference

    Today I spent the day at the 11th Annual Land & Development Conference here in Toronto. I found it particularly good this year, but it’s now late, I’m tired, and I want to go watch game 6 of the NBA finals. So I think this is going to be a fairly short post.

    Here’s a summary of some of my key takeaways from the day (a lot of it is Toronto-centric):

    • Increasingly, the commercial and residential sides of the real estate development business are converging. And it’s being largely driven by the focus on urban intensification and mixed-use.
    • This is leading to an “institutionalization” of the residential side, which has historically been the domain of smaller private/local companies and rich families.
    • Merger is creating complexity around asset valuations: Is it about the income (cap rates) and/or the future development potential?
    • Low rise house prices in Toronto continue to skyrocket. Supply is highly constrained. This has been the story for a number of years now.
    • High rise condo prices in Toronto continue to be more or less flat (modest increase). The industry is going to need to figure out how to work with and compliment the current surge in rental apartment development. There is an element of competition between the two asset classes.
    • According the RealNet’s new home price index, the spread between low-rise and high-rise housing in the Greater Toronto Area widened to $326,659 as of this past April (2015).
    • Rental Apartment Case Studies: Motion on Bay by Concert Properties (Bay and Dundas) was underwrote at $2.60-2.80 psf rents back in 2009. Rents are now in the $3 range. The Heathview by Morguard (Bathurst & St Clair) had $2.80-2.90 psf rents in its pro forma. It achieved and beat these numbers.
    • There’s a flood of Asian money coming into (1) Vancouver and then into (2) Toronto looking for development projects. There appears to be a lot of impatient and/or dumb capital out there. Challenge remains finding good development sites.

    I will end by saying that I found there to be greater transparency at today’s conference. There was a lot of talk about deal specifics and I don’t remember seeing this much detail at past conferences. 

    Maybe I just wasn’t paying attention closely enough before or maybe the industry is slowly becoming more transparent. I hope it’s the latter.

    If you were there today and I missed something groundbreaking, please share it in the comments below!

  • Condo or rental apartment — does it matter?

    Photograph Community by Evgeny Tchebotarev on 500px

    Community by Evgeny Tchebotarev on 500px

    Toronto is the condo capital of North America. For a number of years now, there have been more condos under construction in this city compared to any other in North America, including New York.

    But recently the real estate community has become incredibly interested in building multi-family apartments (also known as purpose-built rental buildings). Which is why about 7 months ago I wrote a post called, Rise of rental.

    It has been decades since Toronto built rental apartment buildings at any sort of scale. That means that our existing stock is generally pretty old and that condominiums – rented out by individual investors – have been almost exclusively fulfilling the need for rental apartments in this city.

    But given that purpose-built rental apartments are on the rise, I’ve been thinking a lot lately about them and about the consumer perspective. 

    And so here’s my question to you:

    If you were looking for a place to rent, would it make a difference whether it was a condominium (rented out by an individual investor) or whether it was a professionally managed apartment building? You can assume that the suite itself is identical.

    There are obviously many differences between both forms of tenure, but I’m curious to what extent that factors into the decision making process for consumers. It hasn’t really been an option in recent years, but that seems destined to change.

    I hope we can have a discussion in the comment section below.

  • Rise of rental

    image

    Last month Oxford Properties submitted a site plan application for the redevelopment of the rundown Cumberland Terrace in Toronto’s Yorkville neighborhood. If you’d like to browse the full application (including all the drawings), you can do that here.

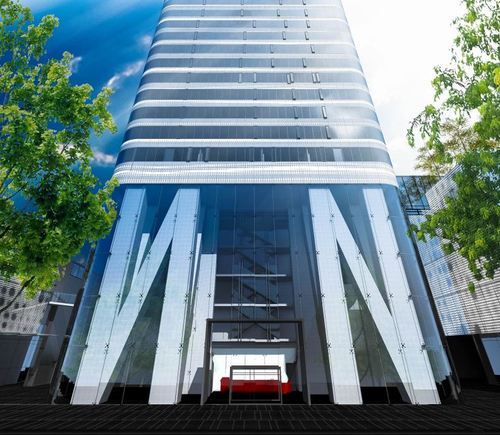
    The proposal is a departure from previous plans and now includes 3 buildings: a 4.5 storey building, a 2.5 storey building, and a midblock 54 storey residential tower (the lobby is shown above). There will be both retail and residential uses.

    For those of you familiar with the mall, it should go without saying that Cumberland Terrace is in desperate need of redevelopment. So I’m not going to talk about that today. Instead, I’d like to mention 2 other points that stood out to me about the application.

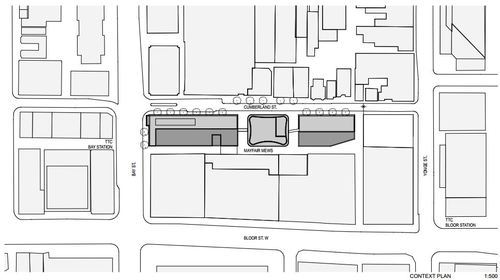
    The first is the 2 midblock connections on either side of the tower, running from Cumberland Street to Mayfair Mews in the rear (see below). Yorkville has a history of intimate laneways, and so it’s nice to see some of this being carried through in a new development. It also opens up the opportunity for an improved Mayfair Mews.

    image

    Secondly, it’s somewhat surprising to see that the 54 storey residential tower is being proposed as rental. Toronto doesn’t build a lot of purpose-built rental apartment buildings. There are some (from the likes of Morguard and Concert Properties), but we haven’t done it at scale for decades. And that’s largely because the demand for condos has been so great.

    But recently I’ve been noticing a renewed interest from the real estate community in multi-family rental assets. Cadillac Fairview also proposed a 65 storey rental building at the north west corner of Yonge Street & Queen Street last year – though they later withdrew their application.

    image

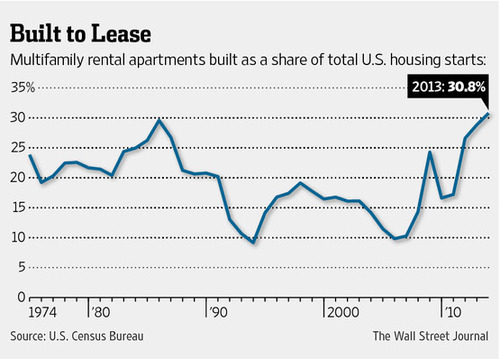
    In the US, rental apartments as a share of all new housing is also at record highs – over 30%. And that’s partly because credit remains tight (certainly compared to pre-2008) and economic growth has been tepid. But also because of demographic changes. People are having fewer children, later in life, and so many are putting off buying.

    So I think we’re going to see even more rental apartments being built in Toronto in the coming years.