Daily insights for city builders, delivered every morning at 6 AM ET. I’m Brandon Donnelly — a Toronto-based real estate developer and founder of Globizen. I’ve been writing here since 2013.

Tag: development

  • The good in change

    This deserves a blog post. Below is a great tweet by Jason Thorne. Jason leads the department of planning and economic development at the City of Hamilton, where, full disclosure, we have a development project.

    https://twitter.com/JasonThorne_RPP/status/1169749295299538944?s=20

    I have said this many times before on the blog, but the challenge with most “community engagement” is that cities typically hear from the people who disagree. Those voices are then taken as representative.

    My gut tells me that we need to make it easier for people to agree. We need to reduce the barriers. Some will take the time to write a thoughtful letter. But most won’t.

  • Risk, uncertainty, and opportunity

    For two reasons, I really like Fred Wilson’s recent blog post on hypothetical value to real value. Firstly, it is structured in the way that I think good blog posts are structured. He starts with a personal story (about this son) and then uses that to take a position and impart some knowledge about the venture capital industry. It makes for a more engaging read. Secondly, I like how he describes the journey and spread between hypothetical value and real value:

    Venture capitalists and seed funds and angel investors make or lose money on the journey from hypothetical value to real value. And when the spread between the two narrows, the money we make is less. When the spread increases, the money we make is more. It is easier to drink your own Kool Aid in the world of hypothetical values. You handicap the odds of winning more aggressively. You trade ownership for capital at work. You accept the new normal. Real value doesn’t move so fast. Because it is right in front of you. You can see it. So it is not prone to flights of fancy. I try to keep this framework front and center in my brain as we meet with founders and work to find transactions that work for everyone. I find it to be a stabilizing force in an unstable market.

    All of this is related to the notion that you make real money when you’re right about something that most people think is wrong. Because that would be hypothetical value. If it were real value, then everyone would simply believe it. It would be “right in front of you.” And this is pretty much true of all competitive marketplaces, including the real estate industry. Risk and uncertainty create opportunity.

    Photo by James Sullivan on Unsplash

  • How homeowners cause gentrification

    Randy Shaw is the Editor of Beyond Chron, Director of San Francisco’s Tenderloin Housing Clinic, and author of, Generation Priced Out: Who Gets to Live in New Urban America.

    In his recent piece in Beyond Chron, he makes the argument that, from San Francisco to New York, homeowners who oppose new multi-unit housing are in fact the ones driving gentrification.

    He admits that there are some exceptions and cites San Francisco’s SOMA neighborhood as a place that became upscale because of new development. (I think it’s more nuanced than that.)

    But the key point is that there countless examples of neighborhoods changing their socioeconomic position without the presence of new development. (There’s investment, but at a smaller or individual scale.)

    Here’s an excerpt from Shaw’s article:

    Banning apartments from single family home neighborhoods limits new residents to those who can afford to purchase a home. Banning new multi-unit construction also artificially reduces supply, driving up home prices for existing owners.

    That’s how most San Francisco neighborhoods, and those in other high-housing cost cities, gentrified. It happened with little or no multi-unit construction. Yet homeowners have adeptly shifted blame for the gentrification of urban neighborhoods from their own land use policies to builders—even when no building has occurred.

    But in the end, do these details even matter? What we have here are competing self-interests. Developers, obviously, want to build. And many people benefit when this does happen. But others don’t see it that way.

  • Zoned for detached single-family housing

    We are in West Virginia now, where the only kind of housing that we have come across is — not surprisingly — low-density, detached, and single-family.

    Indeed, approximately 75% of the residential land across the entire US is estimated to be zoned for detached single-family homes. Using data from UrbanFootprint, the NY Times recently published a series of city maps outlining the percentage of land dedicated exclusively to this housing type.

    In some cases, such as on residential corner lots in Portland, duplexes are allowed. But generally speaking, the pink corresponds to detached single-family housing. About 15% of residential land in New York City is zoned for this, compared to about 94% of the land in San Jose.

    Interestingly enough, none of the residential land in Manhattan is zoned to accommodate detached single-family housing.

  • 17 years of inventory in Miami

    Miami has historically had a volatile housing market because of its position as a second-home destination and because of its dependency on Latin American buyers. There is perhaps no other housing market in the US with the same kind of overall reliance on capital from abroad. This recent article by Candace Taylor in the WSJ is yet another reminder that we are once again in one of those cycles. Below are two excerpts that I found interesting. Note the stats, particularly the last bit in bold. It is also a reminder that when housing supply exceeds demand, usually something happens: prices come down.

    At the same time, new condos launched just as the owners of older units looked to cash out. There were 691 condo sales in Miami Beach in the first quarter of 2019, down 24 percent from 909 in the first quarter of 2015. During the same period, single family homes sales dropped to 81 from 117. The threat of climate change has had some impact on Miami home buyers’ decisions. A 2018 study showed that the value of single-family homes near sea level in Miami-Dade County rose more slowly than that of homes at higher elevations. But agents said a greater threat to the high-end market is inventory buildup.

    Meanwhile, a strong dollar incentivizes international buyers to sell the units they already own, even at below-market prices. The result is a glut of condos for sale, both new and resale. In December 2018, there were 3,663 condo listings for sale in the greater downtown Miami area—more than double the 1,591 for sale in December of 2013, according to an Integra Realty Resources report. Sunny Isles, where new buildings include the 53-story Jade Signature, the Porsche Design Tower and the Turnberry Ocean Club, is estimated to have about 17 years of inventory of condos priced at $5 million and up.

  • Berlin approves rent freeze on existing apartment buildings

    Berlin just approved a five year “rent freeze” on apartments in the German capital. The rent caps will be implemented on January 1, 2020, but will apply retroactively to all rental agreements from June 18, 2019 onward (which is when the decision was made). It is estimated that this new law will apply to some 1.5 million apartments.

    The move is in response to rapidly rising apartment rents, which grew about 12% in 2017 alone. So I can appreciate where this is coming from.

    From what I have read, it will not apply to new construction, which is the first thing I checked when I saw the decision. That would have almost certainly choked off any new apartment construction in the city. With a capped top line, it wouldn’t take long for costs to increase and make new rental construction infeasible.

    That said, a similar squeeze is liable to happen for existing buildings. It is one thing to cap rents (revenue), but what about utility, maintenance, labor, and other operating costs (expenses)? As costs rise and operating margins tighten, it can become exceedingly difficult to reinvest in, or even maintain, an apartment building.

    For more on the announcement, here’s an article from FT.

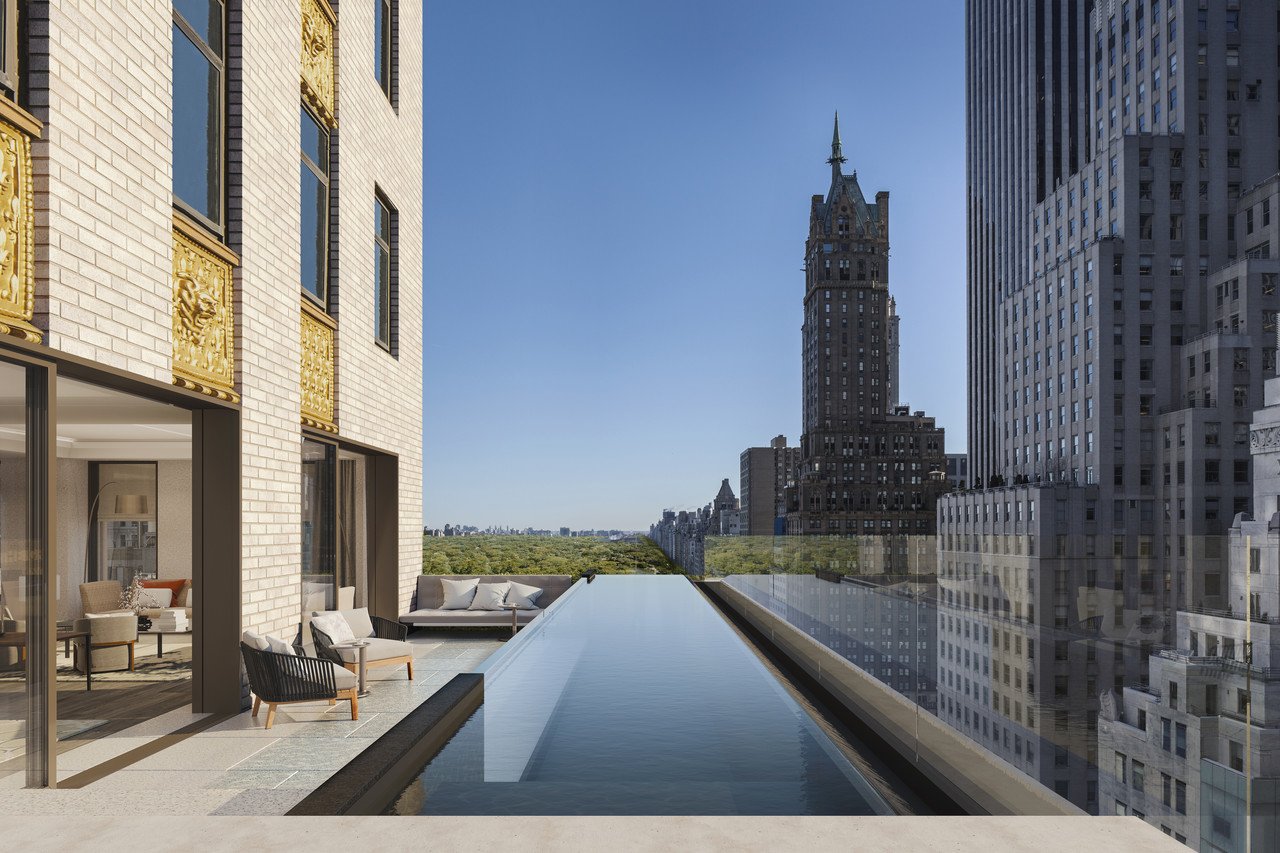
  • Aman New York’s $180 million penthouse

    This morning I was reading about Aman’s new condo and hotel project in New York, which is planned for the 100-year-old Crown Building at 730 Fifth Avenue. It will have 83 hotel rooms and just 22 homes, and be the first urban condominium for the resort company.

    Owned by OKO Group, the hospitality company is mostly known for their “sleek, minimalist hotels in secluded, far-flung destinations,” according to the WSJ. Rooms go for upwards of USD 2,500 per night and they, supposedly, have a rabid customer base known as “Amanjunkies.”

    What’s interesting about this project is that (among other things) it’s a bet the Aman brand will translate to an urban context and drive above-market pricing. And it will do it at a time when the ultra high-net-worth segment of the market in NYC has been cooling because of a new “mansion tax” and probably other factors.

    The five-storey penthouse, which will be built into the building’s “crown,” is asking USD 180 million. If/when it sells, it will break the record for the most expensive home ever sold in the city on a square foot basis at $14,358 psf.

    If you subscribe to the WSJ, you can read the full story here. I find it valuable to see how projects position themselves.

    Rendering: Aman

  • San Jose approves 800-unit co-living project

    Earlier this year, an 800 unit co-living project was approved in downtown San Jose. The developer is Starcity. And it is said to be the largest co-living project in the pipeline in the United States right now.

    A few months later (presumably because of this project), San Jose also created a new “co-living” land-use classification. It is similarly thought to be a first for US cities.

    I think it still remains to be seen how broad the market can be for co-living. Do older generations also want to go back to dorm-like living? Or is this a housing solution mainly for twenty-somethings?

    At the same time, it’s not an entirely new housing idea. I like the parallel that Sarah Holder of CityLab draws between today’s co-living and yesterday’s single room occupancy buildings (SROs).

    There are, of course, many differences, including the amount of space dedicated to common areas (the community aspect). But in both cases, part of the value proposition is about affordability.

    Where do you see co-living going?

  • What I like about Sidewalk Labs’ generative design tool

    Last week I went for a tour of Sidewalk Labs’ “307” workshop here in Toronto. In it they have a generative urban design tool that allows you to toggle things like density, building shape, building height, the amount of green space, the distribution of green space, and so on.

    Perhaps some of you have seen it or used it before. The controls look like this:

    After you’re done playing around with the dials, you are then able to provide feedback on the design that you’ve birthed through two very simple feedback buttons. One is a happy face. And the other is a sad face. (I wonder if the placement of these two buttons has any impact on responses.)

    What I like about this tool is that it immediately imposes a certain degree of reality and it forces you, the participant, to acknowledge the various trade-offs that need to be considered when you’re designing and planning a city.

    For example, if you want lots of parks and public spaces, but you want to hold population density constant — perhaps because you’re trying to make use of an investment made in transit infrastructure — well then you’ll need to accept taller buildings.

    A very similar thought process goes into each and every development pro forma as we all try and manage the myriad of competing interests. But I guess this is also true of life in general. There are gives and there are takes.

  • OMA’s first ground-up project in Manhattan finishes construction

    121 East 22nd — which is OMA’s first ground-up project in Manhattan — recently finished up construction at the corner of E 23rd St and Lexington Ave (the site continues through to E 22nd St, where there is basically a 2nd building). I wrote about the project over two years ago, here.

    Below is a photo by Laurian Ghinitoiu, via Dezeen, of it completed:

    The defining feature is its “prismatic corner”, which, I understand from this interview with David Von Spreckelsen (President of Toll Brothers City Living), was largely an outcome of the site’s restrictive zoning. There was a requirement to have constant street walls. That minimized what could be done architecturally on the project’s main elevations.

    The solution is two contextual street walls — the punched windows are designed to match the rhythm of their adjoining buildings — coming together and creating dramatic visual interest only at the point where they intersect. Below is a rolled out elevation from OMA. Note the gradient created by the windows as they converge toward the corner (center in the drawing below).

    The other interesting thing about this project is that it reminded me just how different the built form of Manhattan can be compared to Toronto. In the case of 121 East 22nd, the streetwalls rise 150 feet without any stepbacks. There is then a 10 foot stepback before the building rises another 60 feet — similarly without any additional breaks.

    I love the grandeur.