Daily insights for city builders, delivered every morning at 6 AM ET. I’m Brandon Donnelly — a Toronto-based real estate developer and founder of Globizen. I’ve been writing here since 2013.

  • Why the office market will eventually rise again

    July 13, 2026 · View original


    Real estate development is cyclical. Supply adjusts slowly to demand, and so it’s common for developers to get ahead of their skis and build too much space. This is what happened in the 1980s when American developers built more office space than in all previous years of the republic’s history (yes, it’s true), and then nationwide vacancy rates went from 4.6% to 16.9%. And it’s what happened following the dot-com crash when office vacancy in Silicon Valley went from almost 0% to over 20%.

    Today, things feel kind of similar.

    According to Cushman & Wakefield, nearly 37% of the office space in downtown Seattle is now vacant. Since 2020, it is estimated that these office properties have in aggregate lost about $15 billion, or almost half, of their value. This has people repeating the regular refrain that “this time is different” and that “the office market may never come back.” And indeed, the commonly held belief is that this time isn’t just cyclical, it’s also structural. How and where we work has changed.

    But unless you believe that offices as a spatial construct will fully cease to exist at some indeterminate point in the future, then the reality is that the demand curve has simply shifted. We may not need office space in quite the same way, but we will still need some office space. This means that, at some point, we will find a new supply-and-demand equilibrium and, at some point, developers will get back to building, and overbuilding, office buildings. It’s just impossible to determine when that might be.


    Cover photo by Zhifei Zhou

  • Toronto is now an apartment city

    July 12, 2026 · View original


    The way CMHC typically tracks and categorizes housing types is as follows: single, semi-detached, traditional row, and then everything else. This “everything else” bucket is called “apartment,” and it includes high-rise apartments, mid-rise apartments, low-rise apartments, duplexes, triplexes, multiplexes, and anything else that doesn’t fit into one of the other categories.

    This taxonomy reflects our bias toward single-family, grade-related housing because if you look at the distribution for a city like Toronto, it doesn’t really make sense to do it in this way. For example, if we were to look at housing starts in Toronto proper for 2025, the distribution looks like this:

    – Single: 5.2% – Semi-Detached: 0.4% – Row: 2.5% – Apartment: 92%

    If we were to look at the entire Toronto CMA, the distribution updates to the following:

    – Single: 12% – Semi-Detached: 0.5% – Row: 14.2% – Apartment: 72.8%

    Do we really need a separate category for semi-detached houses? And would it not make sense to get a bit more granular with the apartment category given that it’s basically what we’re building these days? Obviously, markets vary, but in the case of Toronto, we have flipped to an apartment city.

    Now, if you were to look at an aerial view of the Toronto CMA, you would see the opposite. You would see concentrations of towers surrounded by seas of low-rise housing, and you would be forgiven for thinking differently about the city. But this is a lagging indicator. The leading indicator is housing starts, and it’s pretty clear what that is saying.

    These are important stats to think about because they help illustrate the housing problem that needs to be solved. Last year, Toronto saw a net domestic out-migration of 77,500 people. One possible explanation is that some of these people left for more affordable, single-family housing. For the sake of argument, let’s assume that’s the case.

    A portion of this segment may only be interested in single-family housing, and if that is the case, Toronto will never again create the housing they want at scale. But I would wager that there’s another meaningful segment that would have stayed in Toronto if only they could have found housing that met their needs. And that is the opportunity that exists today for city builders.

    We know that apartments are the future of Toronto, but we also know that they can take many forms, from 100-storey towers to small “missing middle” projects that are still grade-related. The housing solutions we seek are necessarily going to lie within the black box we today call “apartments.”


    Cover photo by Venrick Azcueta

  • Architecture for today

    July 11, 2026 · View original


    Periodically, Twitter will surface posts for me that bemoan modern architecture and advocate for good old-fashioned traditional architecture. Sometimes these posts will share a modern building with a disparaging comment like, “Imagine wanting this over traditional architecture,” and sometimes I will engage because, yeah, I would prefer the modernist building to traditional architecture.

    But let’s be clear: I don’t have an issue with traditional architecture done well, and there are also countless examples of “modern” architecture that I think are truly abysmal. This is not about architectural tribalism. I love Paris and think it is beautiful, but I also think Brazil’s equatorial brutalism is equally beautiful. Both feel authentic.

    Here’s how I would describe my position.

    First, focusing on one style or another is not the goal. Many contemporary architects think of “style” as a bad word. It implies a superficial veneer. Great architecture aims to be something deeper and more intentional. It solves problems, responds to specific conditions, and also presents new ideas.

    Second, the beauty of art, architecture, and design is that they are never created in a vacuum. They always reflect the current cultural environment. The challenge I have with traditional architecture is that I find it curious to try to speak to a moment in time that no longer exists. I am much more interested in authenticity and what the future might bring.

    And third, movements take time. It’s easy to romanticize the past as being better than our current environment. Whether we’re talking about Impressionist painters or architecture free of ornament (in the case of modernism), it is intellectually easier to think the old ways were better. But history has shown us that posterity will almost certainly come to see things differently.


    Cover photo by laura adai

  • The real story behind Toronto’s stalled population growth

    July 10, 2026 · View original


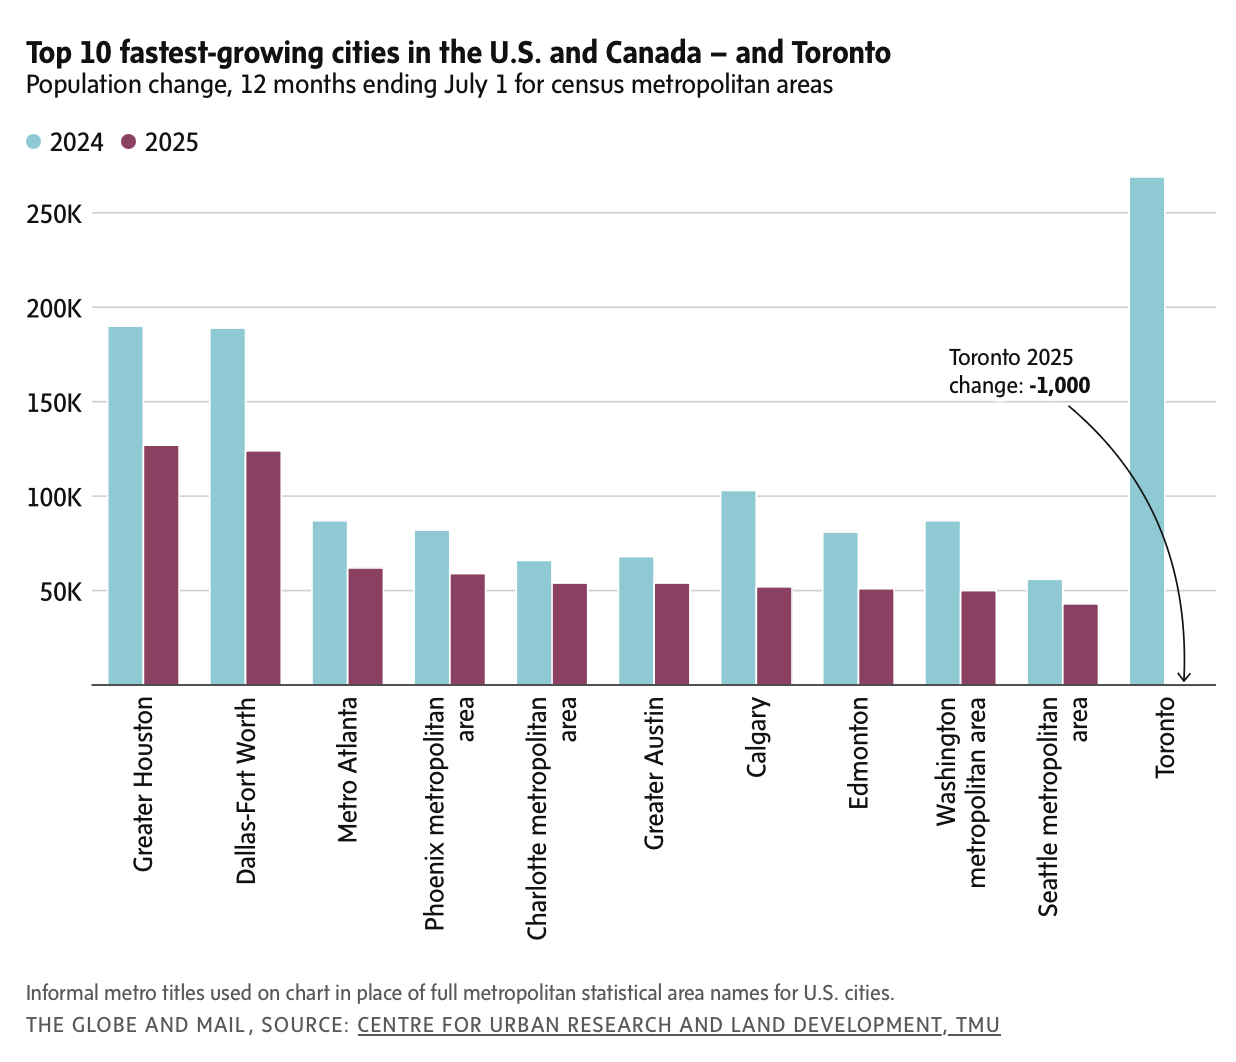
    How quickly things can change. In 2024, the Toronto Census Metropolitan Area was the fastest-growing region in Canada and the US. Then, last year, it lost around 1,000 people and dropped to 443rd place. See above chart. The obvious explanation is Canada’s concerted effort to reduce temporary workers and international students. But actually, Toronto is still one of the top regions when it comes to net international migration, adding 53,000 people in 2025. The real story, according to recent analysis from the Centre for Urban Research and Land Development at TMU, is that Toronto has simply gotten too expensive, driving massive domestic out-migration. Last year, Toronto lost 77,500 people this way, wiping out its natural growth and its net international migration gains. This is our regular reminder that we need to be far better at delivering attainable housing at scale.


    Cover photo by Frank Huang

    Chart from The Globe and Mail

  • How public transit connects the World Cup host cities

    July 9, 2026 · View original


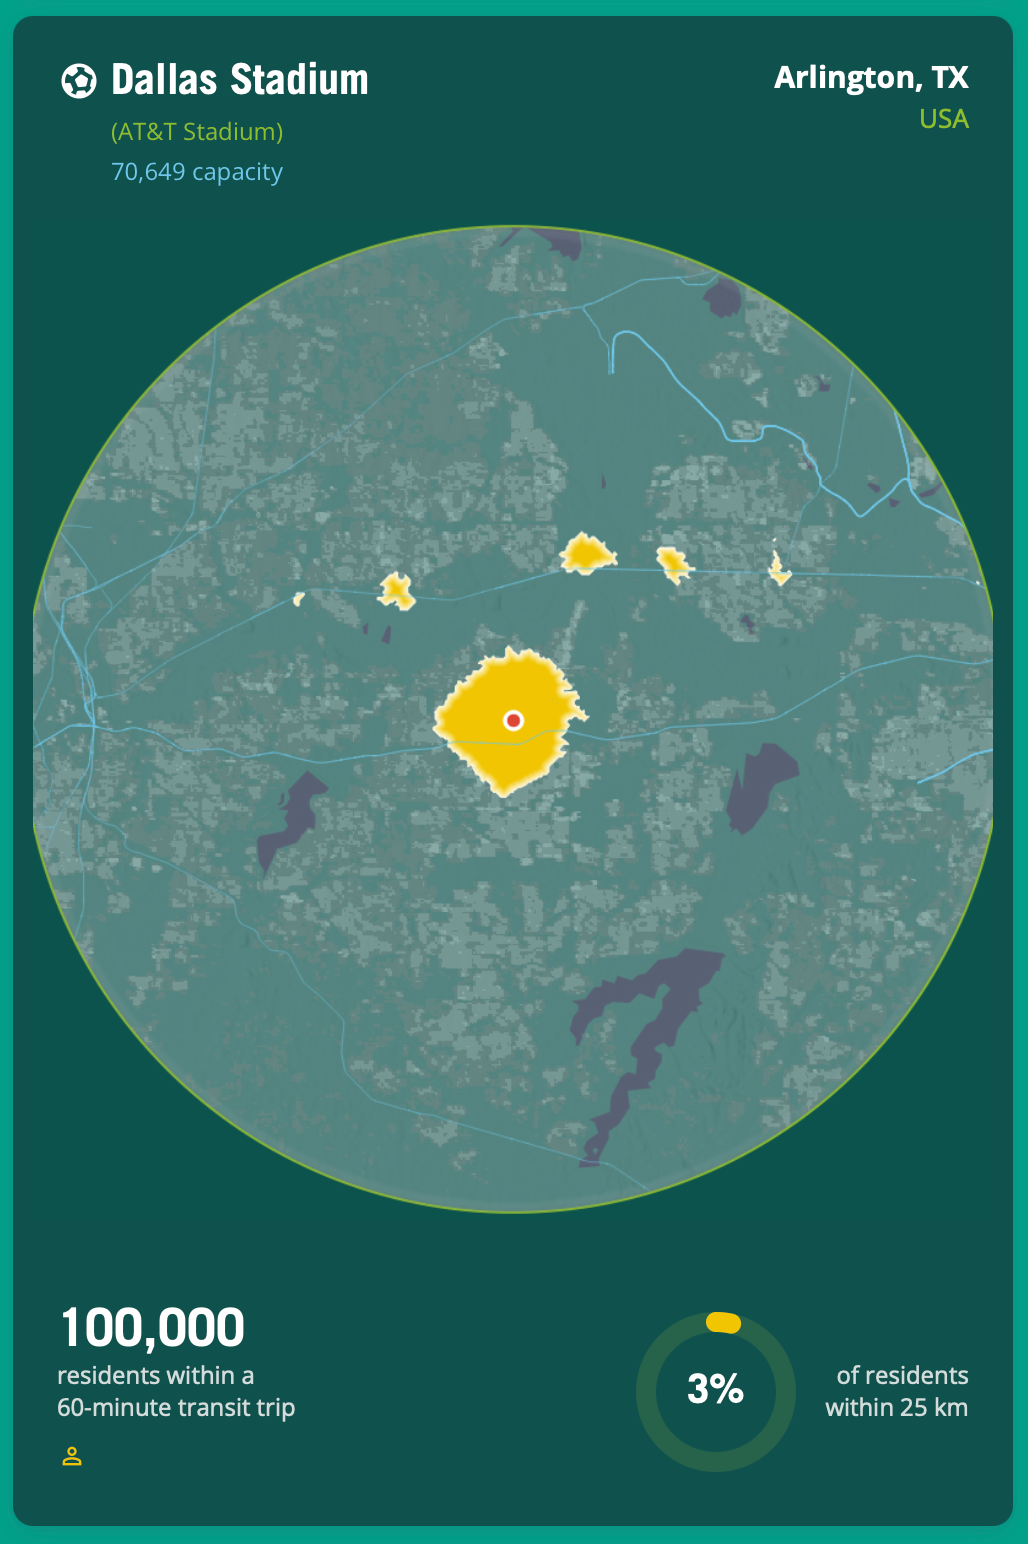
    The 2026 FIFA World Cup is being hosted across 16 different cities in Canada, the United States, and Mexico. The city hosting the most games is Dallas, with 9 matches. Supposedly, this is because the city has a nice stadium with a retractable roof and capacity for 70,649 people, and Dallas is a fairly central location for a tournament being hosted across North America.

    But here’s another way of looking at the stadiums. The School of Cities at the University of Toronto recently published a study called “Transit-Oriented Stadiums.” What they did was look at how well connected each stadium is to its host city by public transit. More specifically, they looked at how many people live within a 60-minute public transit isochrone polygon.

    Dallas Stadium (AT&T Stadium) is in Arlington, Texas, and it has about 100,000 residents within a 60-minute transit trip:

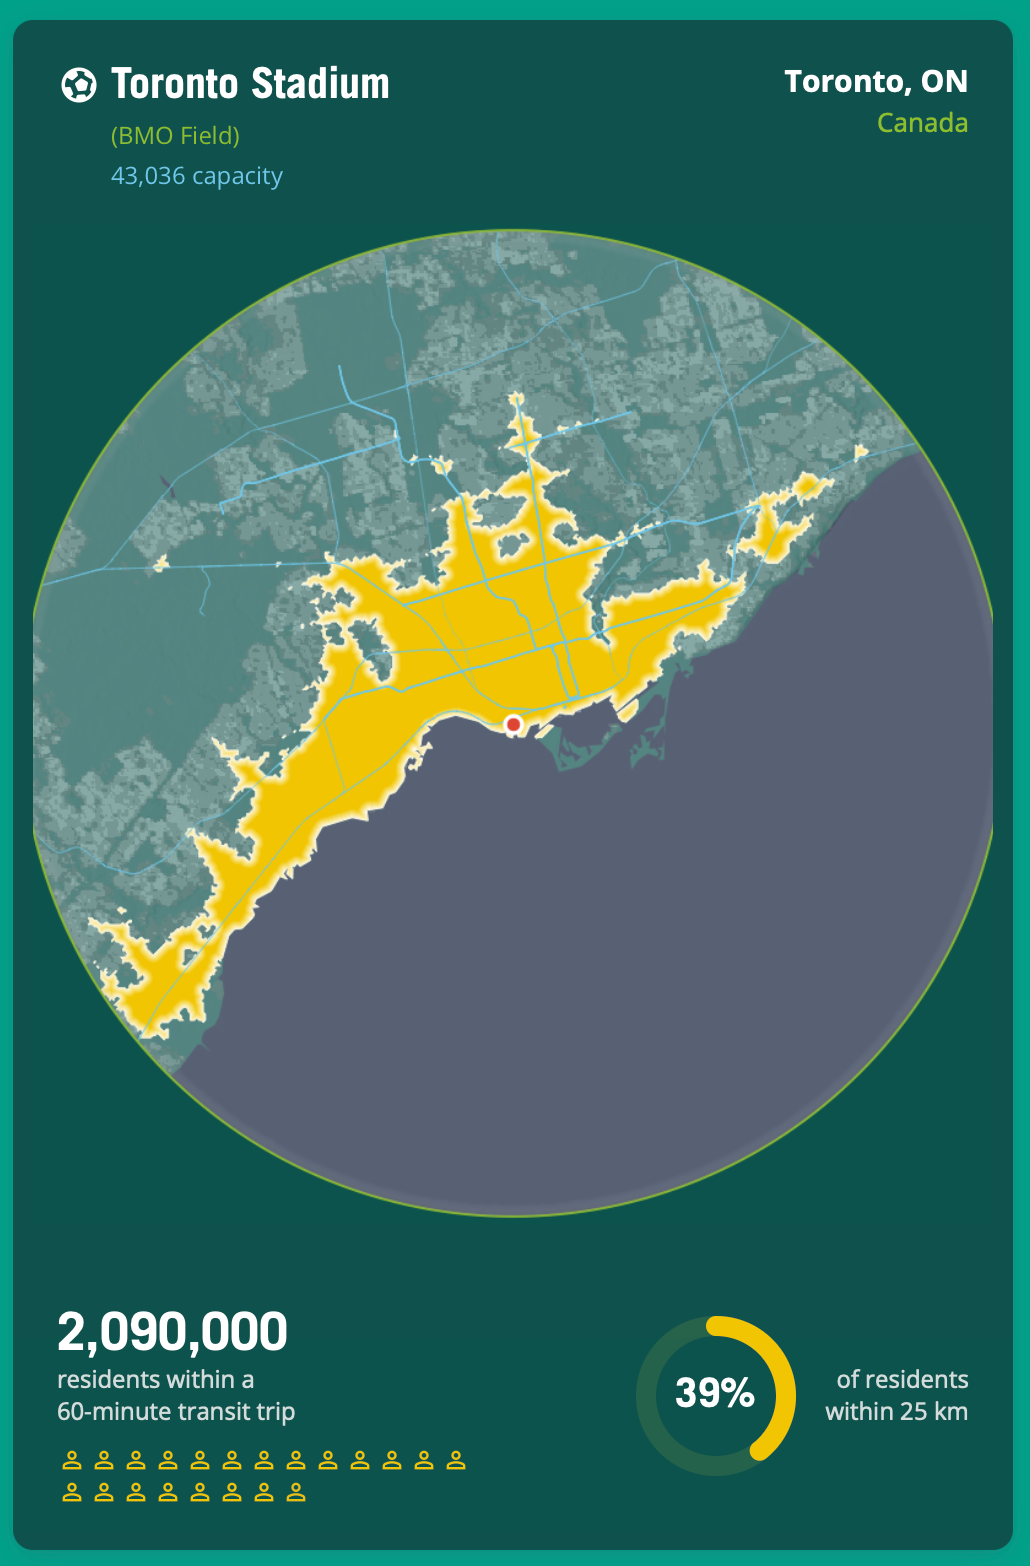
    Now, here’s Toronto. BMO Field has a much smaller capacity (43,036 people), but over 2 million residents live within a 60-minute transit trip:

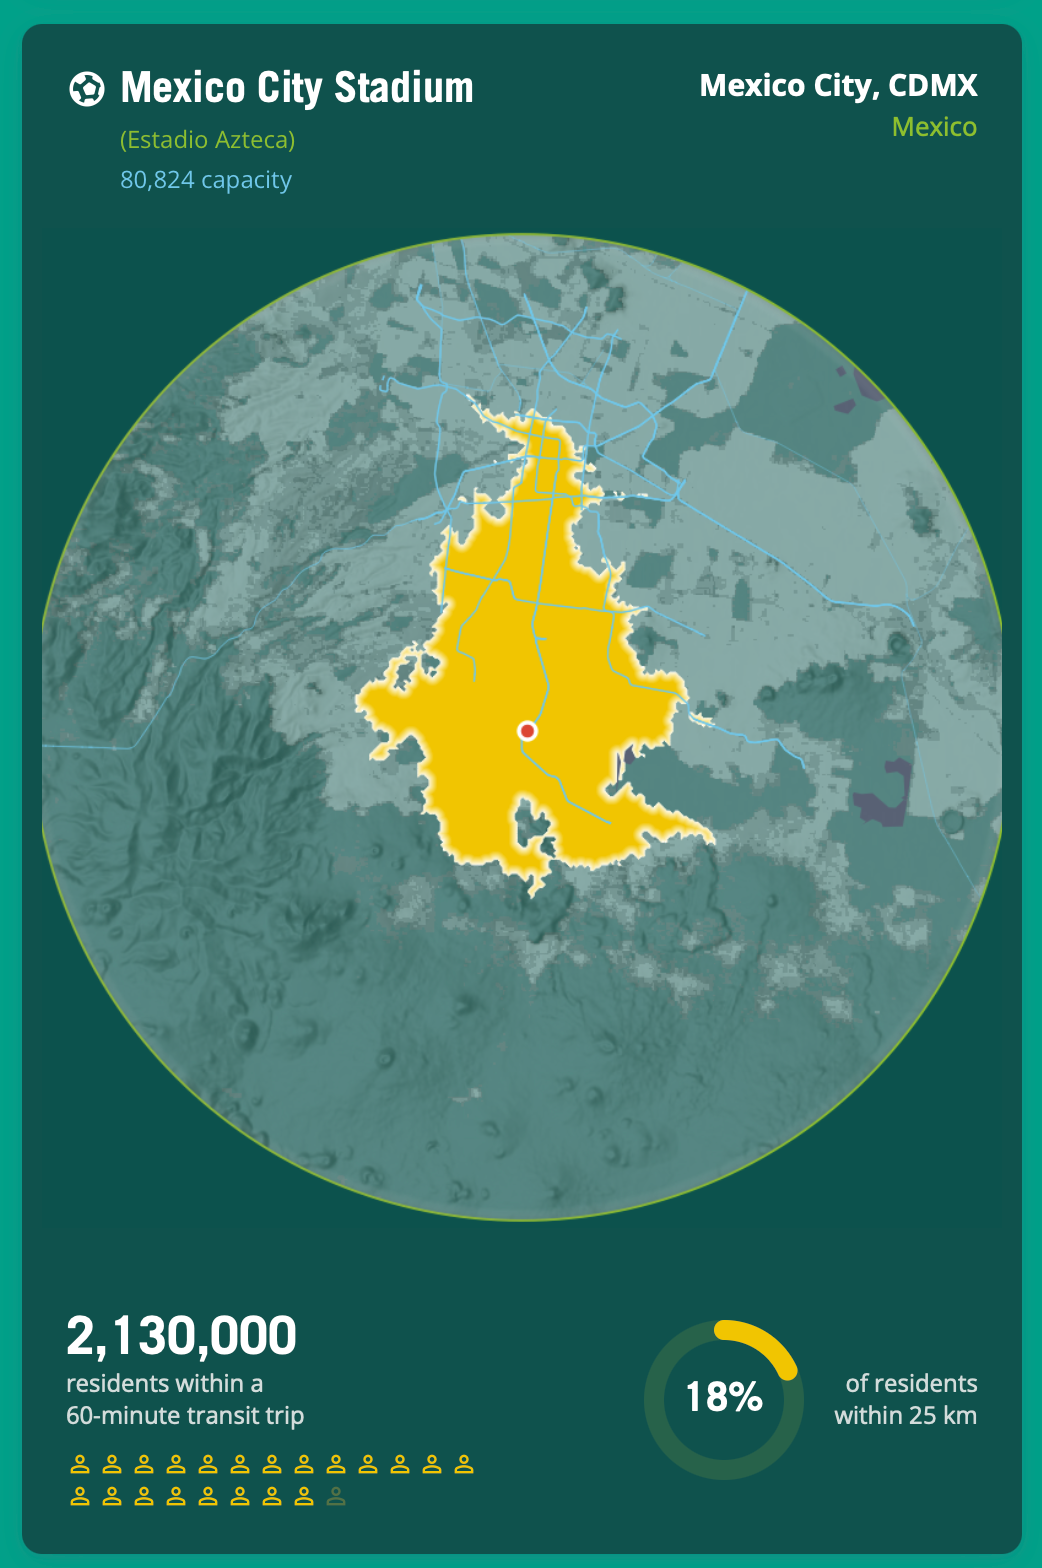
    Mexico City’s transit catchment reaches over 2.1 million people, despite its stadium being out of the core of the city:

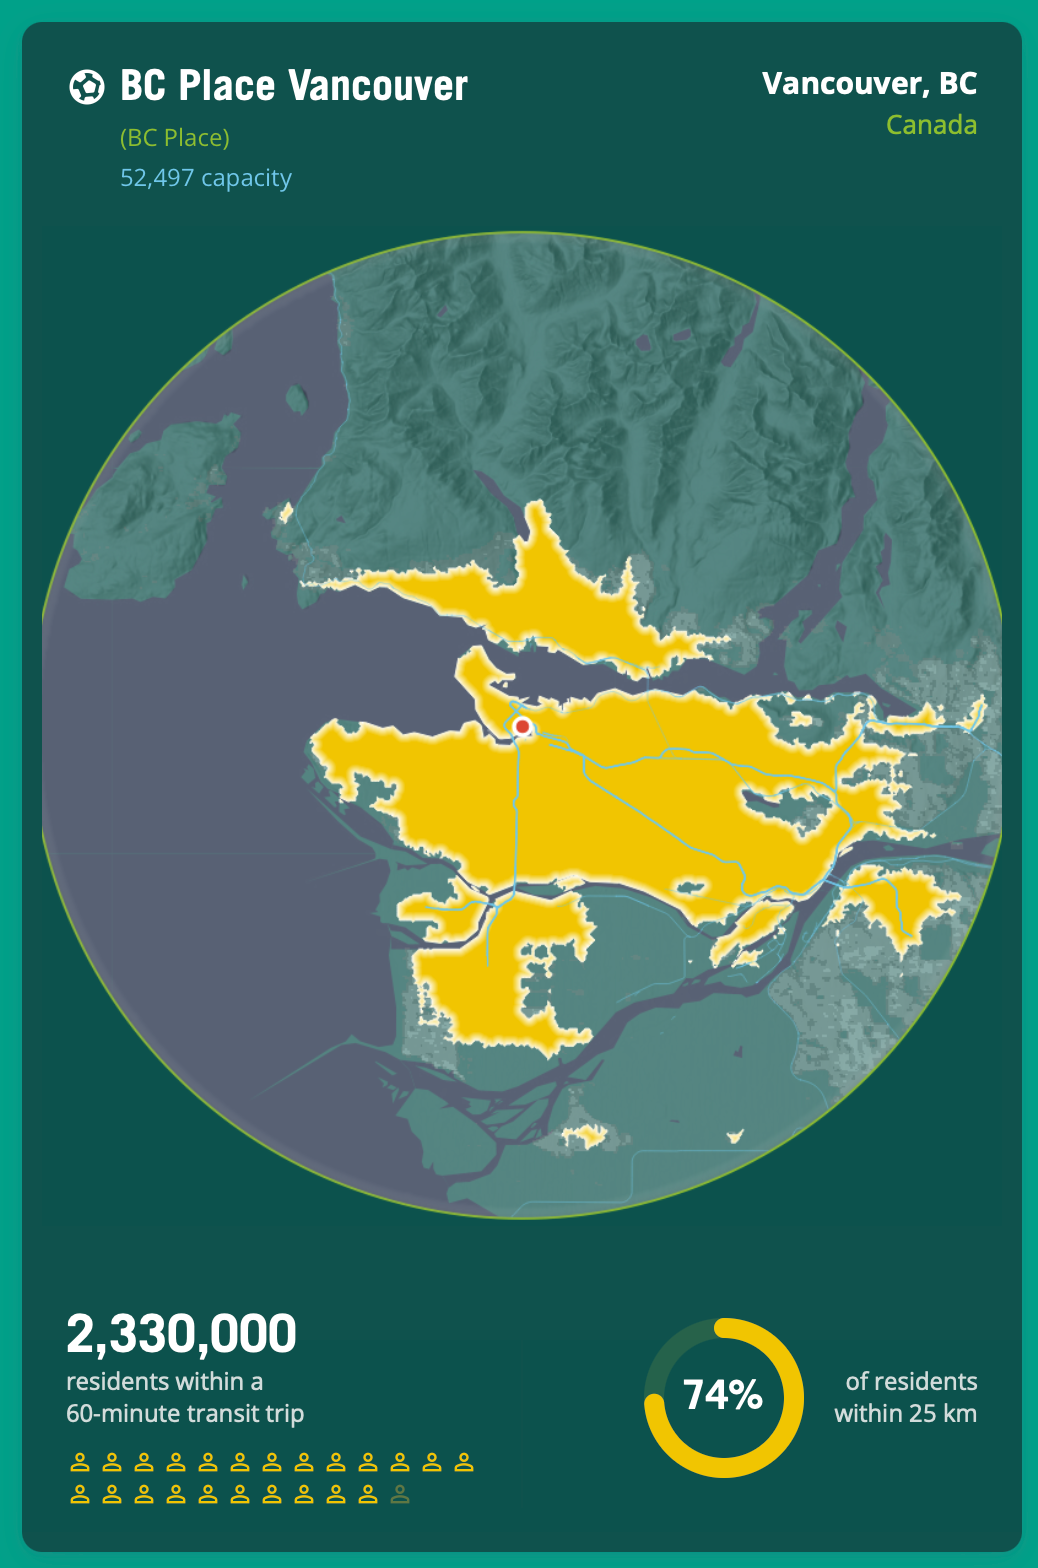
    And Vancouver takes the top spot with over 2.3 million people:

    These diagrams highlight a striking divide in land-use patterns. The two key factors are stadium placement and transit investment. Obviously, if you flipped the script and mapped the number of residents within a 60-minute drive, then Dallas Stadium would perform quite differently. But bringing 70,000 people to one location via cars will never match the spatial efficiency of public transit.


    Cover photo by Ronin

    Diagrams from the School of Cities at the University of Toronto

  • The liveability rankings are shifting toward Asia

    July 8, 2026 · View original


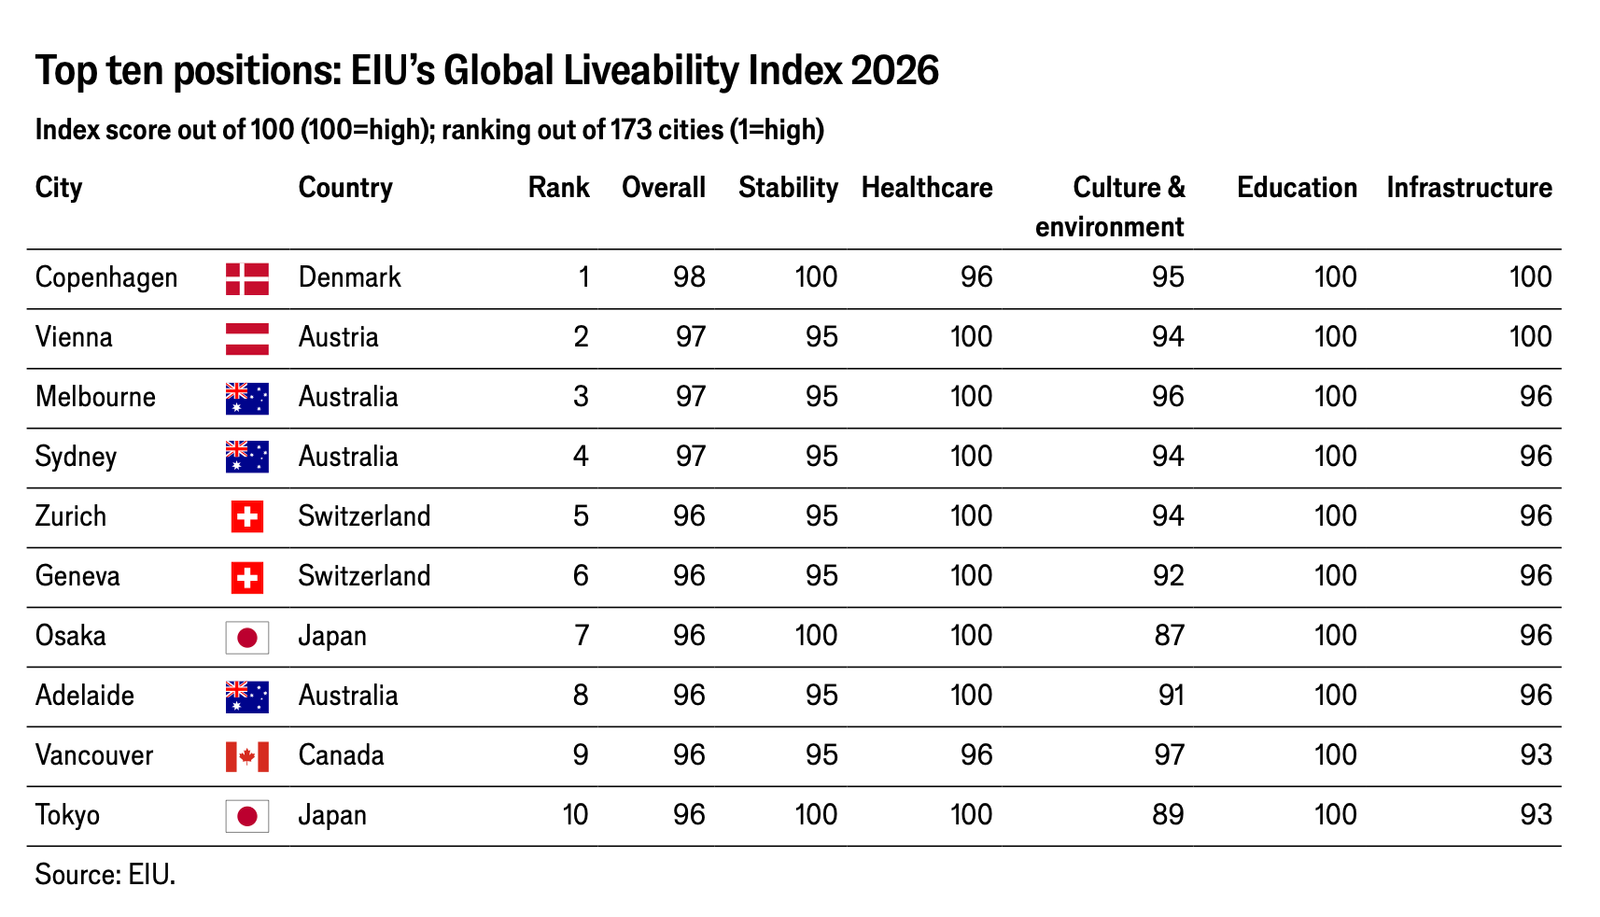
    The Economist just released its list of the world’s most — and least — liveable cities in 2026. It has a somewhat similar complexion to Monocle’s quality of life survey in that you’ll find cities like Copenhagen, Vienna, Sydney, Zurich, and Vancouver on both. But at the same time, there is a core difference.

    Basically the way it works is that The Economist’s ranking is designed to help HR departments calculate “hardship allowances” when staff are relocating overseas, whereas the Monocle survey places a much greater emphasis on questions like: Can I grab a drink at a cool bar at 2 AM on a Tuesday? It’s for this reason that you won’t find cities like Lisbon, Paris, and Madrid on The Economist’s top 10 list.

    The other not-very-surprising fact of this year’s ranking is that cities in the Middle East and North Africa (MENA) broadly saw the largest declines in liveability. This is due to the Iran war and deteriorating “stability” points.

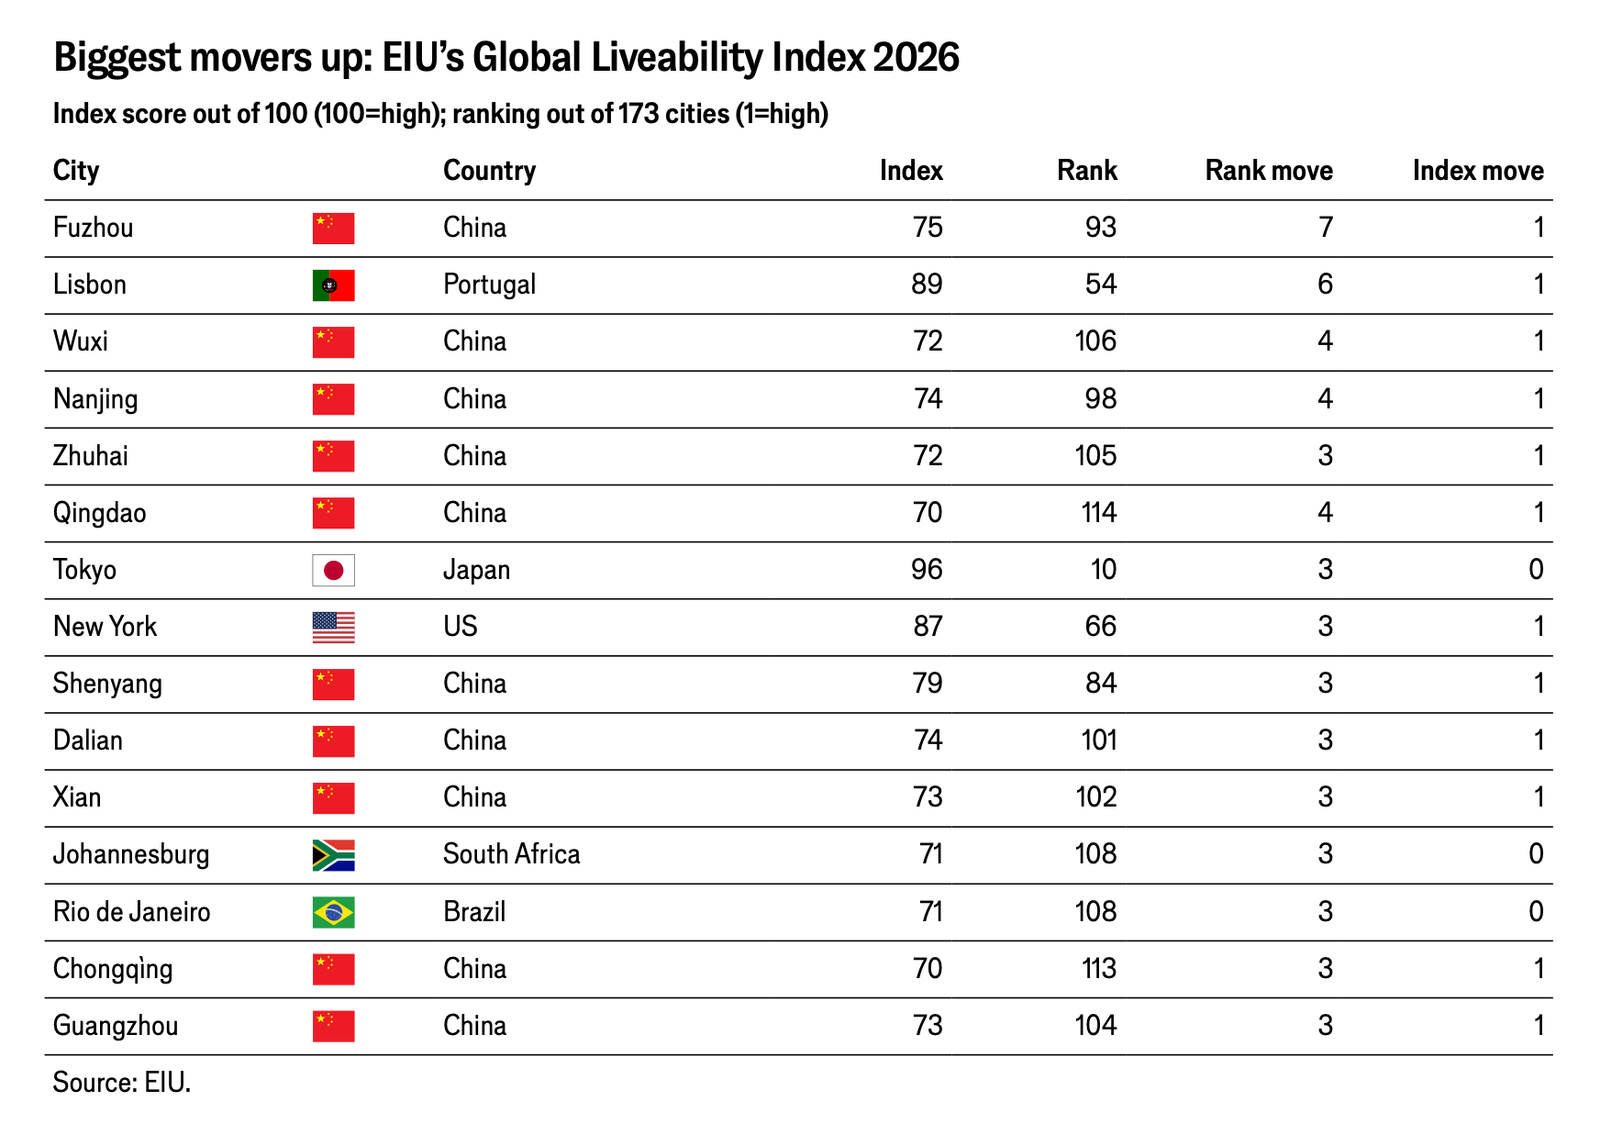
    Perhaps the most interesting takeaway is the rise of Asia, and in particular China. There are now 9 Asian cities in the top 20, compared to 7 cities in Europe. According to The Economist, improvements in healthcare are why Chinese cities are posting the biggest gains. Also on the movers-up list is New York, due to falling crime rates and a reduced perceived terrorism risk.

    While this is certainly positive, if you’d like to dive deeper, you can download a full copy of the EIU Global Liveability Index 2026.


    Cover photo by Julius Carmine

  • The return of price discovery in Toronto’s condominium market

    July 7, 2026 · View original


    I was speaking to a developer friend the other week about the current state of the Toronto market, and I told him that I think we’re at the bottom. He responded with, “Oh yeah, I think so too, but how long are we going to be here for?” Good question.

    The answer is, of course, unknowable. We can all speculate based on the lack of housing starts we have seen over the past few years, when positive immigration is expected to return, and other factors, but nobody can say for sure.

    As Howard Marks said on a recent Prof G Markets podcast, this is what makes investing so interesting and rewarding. There’s no way to ever know all the answers!

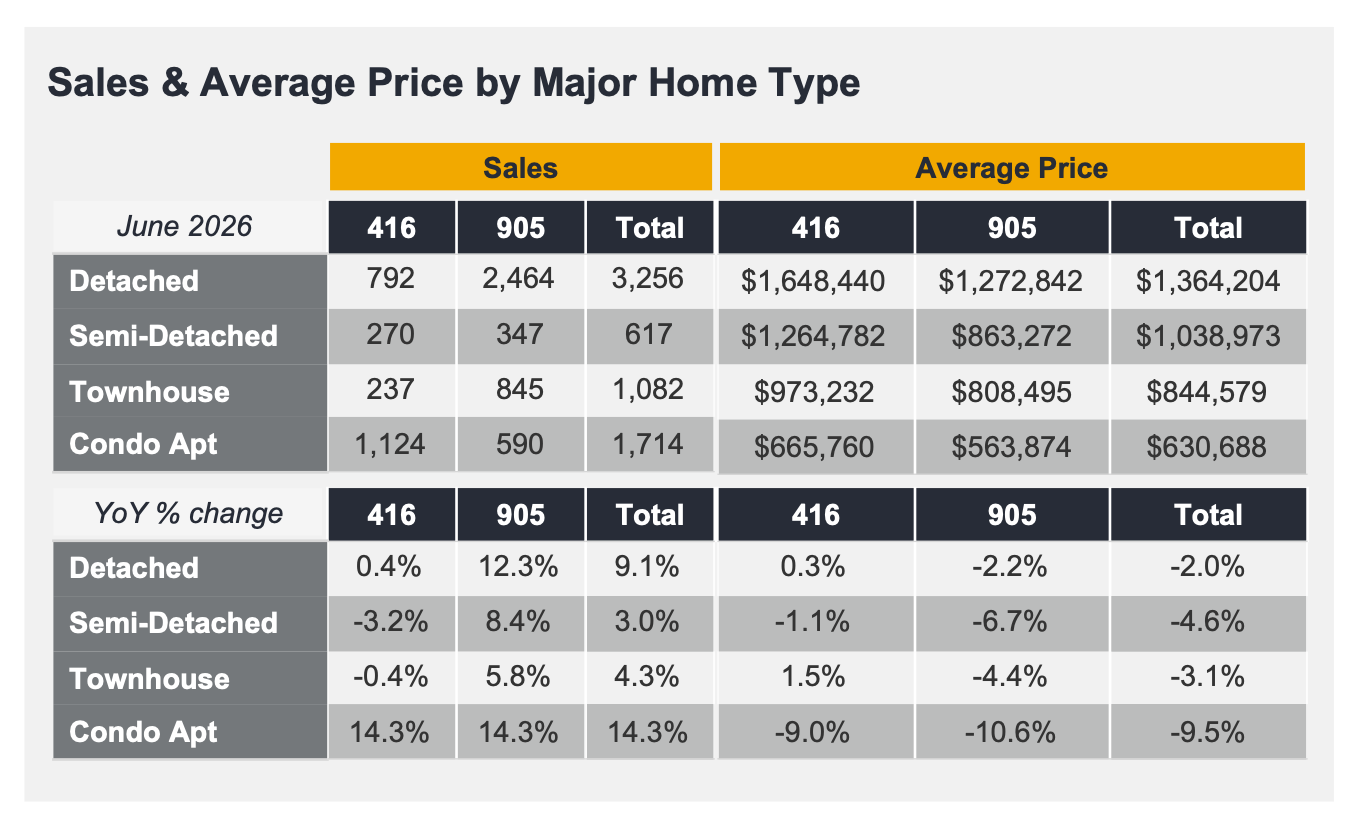
    What I think we can say about this year, though, is that the condominium market has successfully returned to price discovery. Since roughly 2022, the market has been frozen because the bid-ask spread was simply too great.

    But deals are once again getting done. In June of this year, the Toronto Regional Real Estate Board (TRREB) reported 1,124 condominium apartment sales in Toronto and 590 sales in the suburbs. Both of these numbers represent a 14.3% year-over-year increase.

    We’re talking about a limited dataset, but I’m seeing and hearing from colleagues a similar dynamic play out on the new construction side of the business. End-user buyers have emerged from the sidelines and are now the dominant buyers (versus investors).

    This doesn’t necessarily tell us what the next few years will look like, but I suspect that when we look back on the second half of 2026, it will represent an important milestone.


    Cover photo by Narciso Arellano

    Chart from TRREB

  • The fundamental contradiction in Canadian housing

    July 6, 2026 · View original


    > “Show me the incentive and I’ll show you the outcome.” —Charlie Munger

    Canada is, broadly speaking, a nation of homeowners. In the 2021 census, 66.5% of Canadians owned their own home. So, most. And this is encouraged. Owning your own home is typically viewed as a way to generate wealth, build equity, and provide tangible evidence that you have enough creditworthiness to make a mortgage payment every month.

    Given the above, you could say that the majority of Canadians are incentivized to do things to protect the value of housing and, in turn, their personal net worth. But we also know that this creates an inexplicable housing paradox. We want housing to be more affordable for some, but ever more valuable to others. How exactly should we achieve this?

    In this recent opinion piece in the Globe & Mail, John Turley-Ewart argues that the recent announcement in Vancouver translates into housing no longer being a home. Rather, it has become a “supply-managed good in a protected industry,” similar to dairy and telecom in this country. So: “The result will be a country where homeownership is reserved for the few by design. It shouldn’t be that way.”

    Here’s a thought exercise: Why would it be a problem if Canada’s homeownership rate dropped to, say, one-third — the same rate as Switzerland? Is it because housing should appreciate faster than the rate of inflation and generate wealth for Canadians, or is it simply because pride of ownership is good for people’s moral well-being? If it’s the former, well, then the argument eats its own tail.

    We are saying we want housing to be more affordable so more people can own it, but if it were constantly depreciating (getting cheaper), or even just appreciating at the rate of inflation, should people even want to own it? Why not just rent and invest the down payment elsewhere to earn greater returns? That’s what the Swiss do by and large.
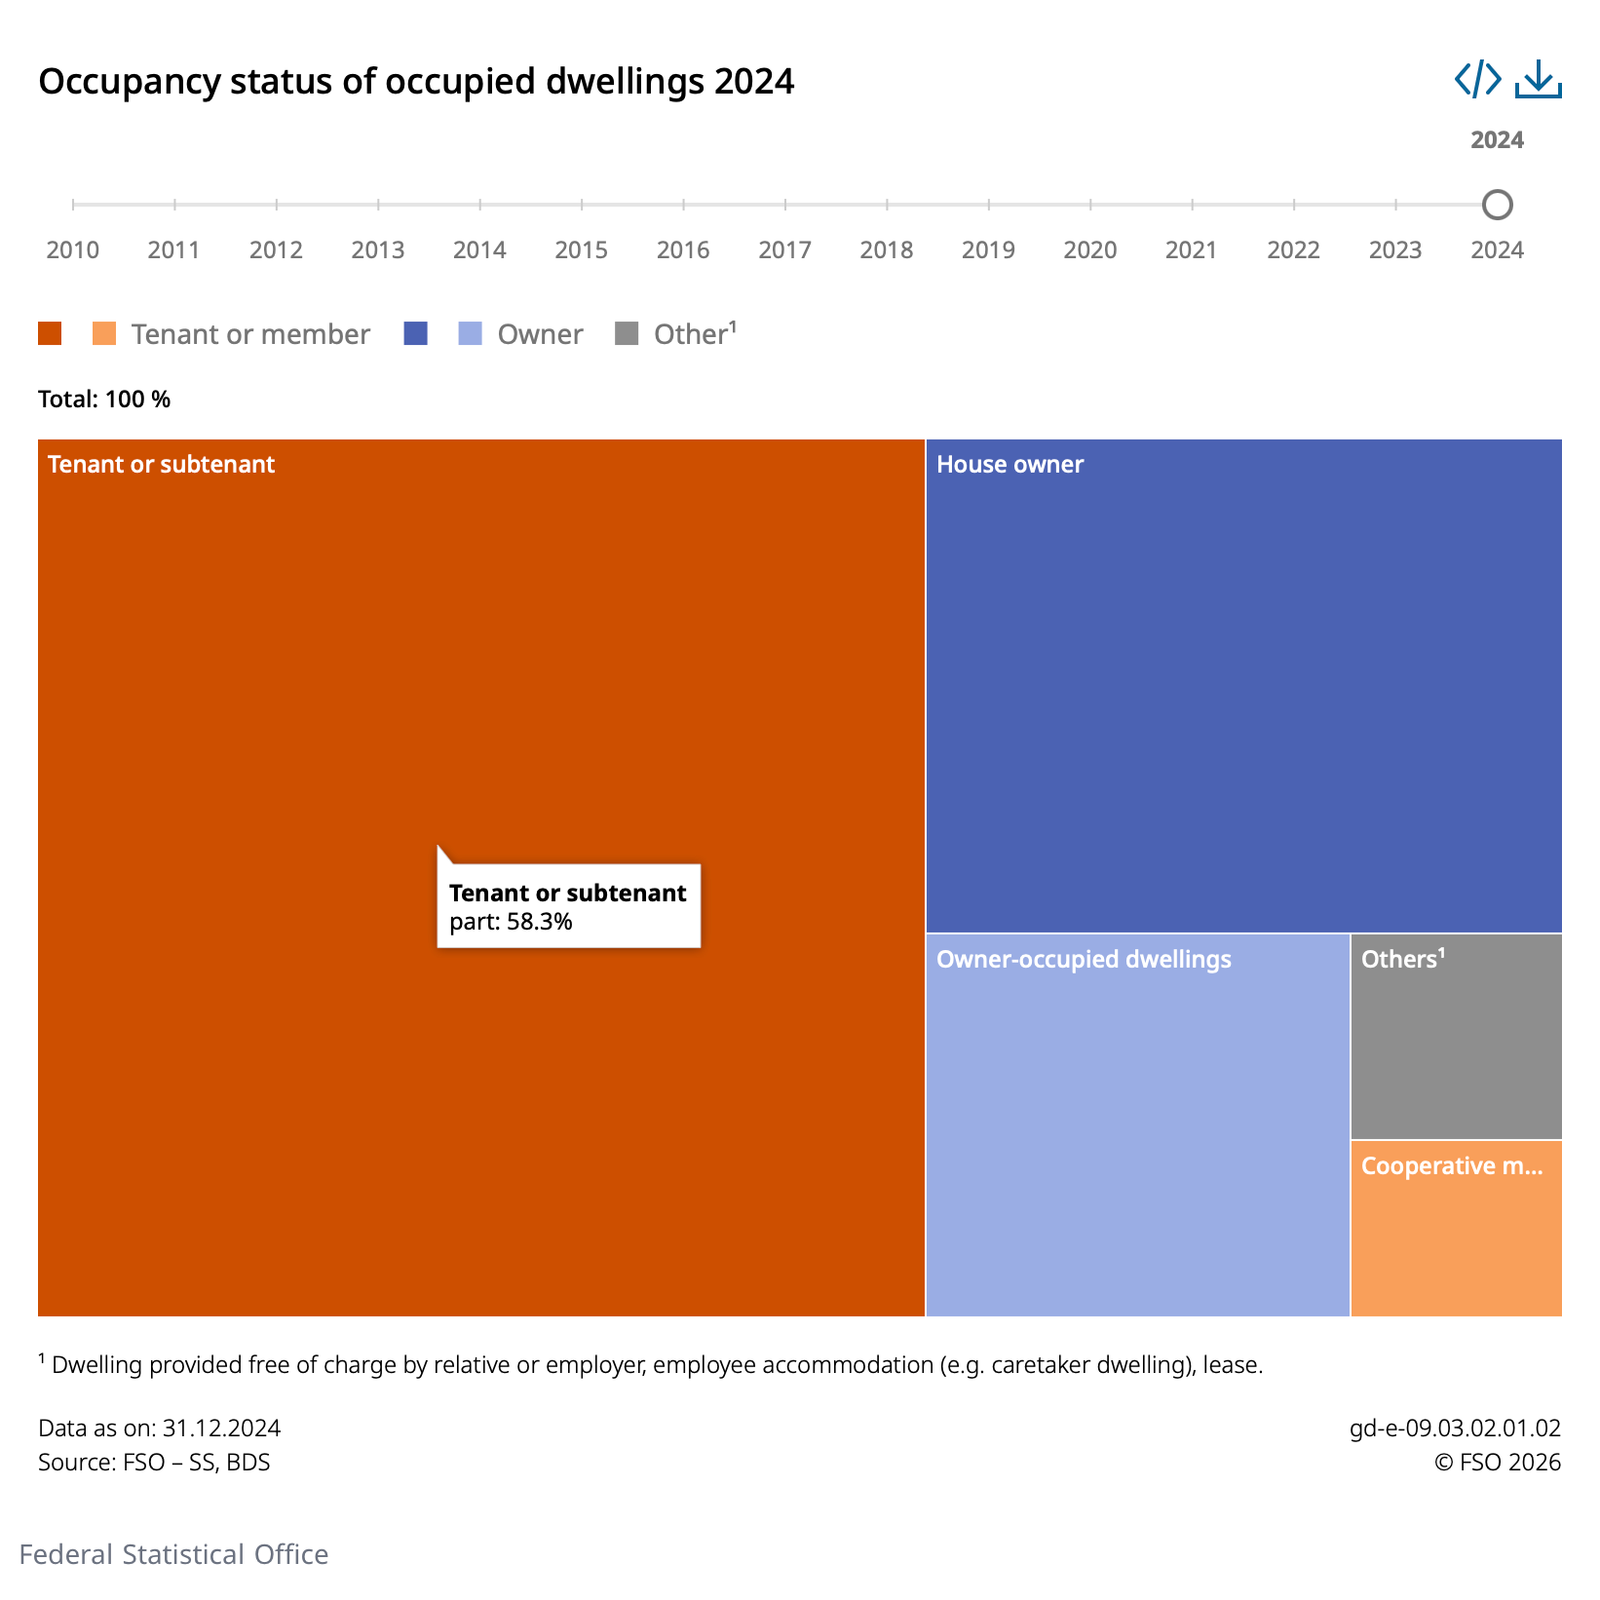
    Swiss households tend to rent rather than own.

    I believe the more precise argument being made in the Globe & Mail is that housing has simply gotten too expensive for middle-class incomes, so what we need is less government meddling and a reset before the market begins to re-appreciate in favor of the 66.5% of Canadians who are invested. While I certainly agree with the basic idea that we need to stop overtaxing new housing and reset our development cost structures, let’s not ignore our clear housing paradox.

    In Canada, we view housing as an investment, and that runs counter to the idea that housing should be as affordable as possible to the greatest number of people. As we know, this viewpoint isn’t the same everywhere. Japan, for instance, has historically viewed housing as a consumer good. You bought it new, or built it new, when you needed it, and once you were done with it, the expectation was that there wouldn’t be many buyers for it.
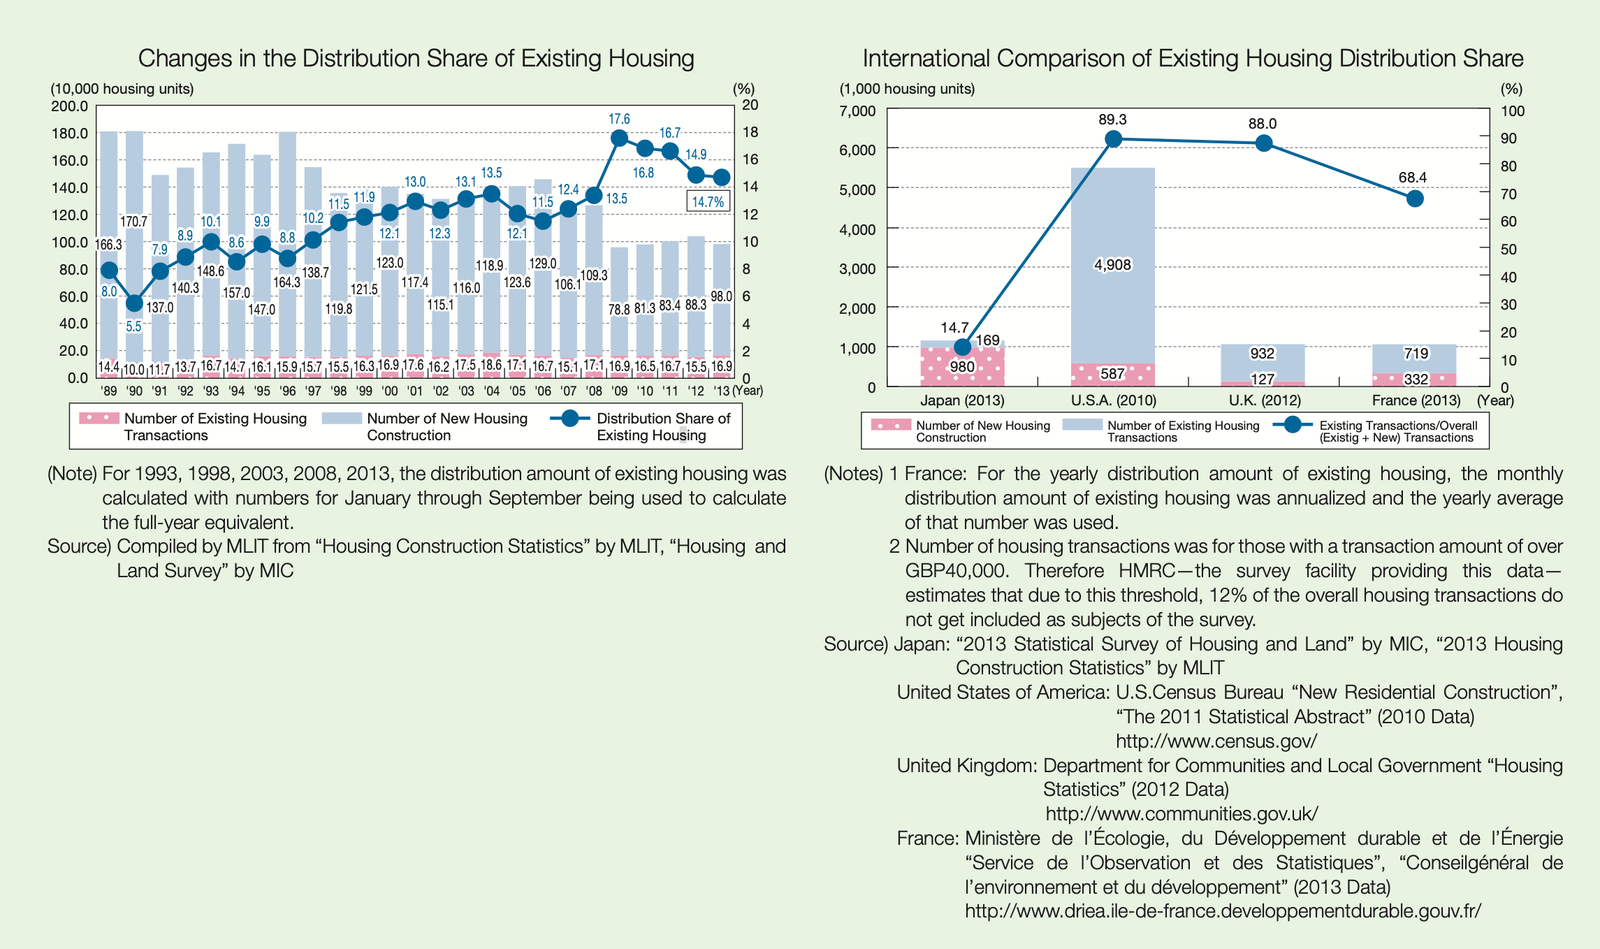
    Historically, Japanese households have greatly favoured new construction over resale housing

    As recently as 2013, the percentage of existing housing transactions as a share of the overall housing market in Japan was only 14.7%, compared to over 89% in the US (2010 figure). The government has since worked to get this number up, but it shows a distinct historical view of housing. It also led to more daring residential architecture. If you’re not concerned about what the next buyer might think, you become a little more free-willed.

    The point of this post is not to pass a value judgement on any one approach; rather, it is to point out that there are many different ways to think about housing. Deciding the precise outcome we want is always going to be helpful in determining the right solutions.


    Cover photo by Aditya Chinchure

    Swiss housing occupancy status diagram from the FSO

    Japan charts from the White Paper on Land, Infrastructure, Transport and Tourism in Japan 2015

  • Butts for nuts

    Why we couldn’t train crows to clean up our cigarette butts

    July 5, 2026 · View original


    Back in 2022, a Swedish startup called Corvid Cleaning made headlines by launching a pilot program in the city of Södertälje involving an operant conditioning device in the city’s public realm. The machine allowed crows — which, it turns out, are pretty smart and social animals — to deposit discarded cigarette butts in exchange for food.

    The machine itself would scan whatever the crows brought in, and if it was, in fact, a dirty butt, the machine automatically dispensed a small piece of food, such as a peanut. And because crows are social animals, the thinking was that they would then run and tell their friends, “Hey, I found us a great dinner spot!”

    It’s an alluring and unexpected concept. The hope was to slash the city’s annual cleaning bill by getting the crows to do our dirty work. And that’s why this “new pilot” seems to go viral periodically. But the reality is that Corvid Cleaning filed for bankruptcy in 2025 and, as far as I’m aware, this has in no way taken off as a viable solution for keeping our streets free of cigarettes.

    The obvious problem is that cigarette butts are highly toxic, and so encouraging animals to transport them around is a suboptimal solution. Supposedly, crows are also a little too smart, and they started to try to game the system. Regardless, the prototype is dead. If only more of us could be like the Japanese, and not throw our garbage on the street.


    Cover photo by Fatemeh Heidari

  • Where green towers thrive

    July 4, 2026 · View original


    Many years ago, I was in a design meeting for a tall building we were working on and I brought up the idea of planting greenery all the way up the tower. You know, something like the Bosco Verticale in Milan.

    But after I said this, our landscape architect looked at me and simply said, “No, it doesn’t work, not in our climate.” And that was it.

    Of all the people in the room, I thought I could get the landscape architect excited about this suggestion, but nope. It got immediately shot down, and for good reason.

    The greenery would be dead here in Toronto for not an insignificant part of the year, and the additional dead loads created by water-saturated soil and structural planters raise questions about whether it’s the most sustainable way to build tall buildings.

    But there are climates where green towers make a lot more sense, namely in places like Brazil. In fact, São Paulo rewards developers for integrating features such as green facades.

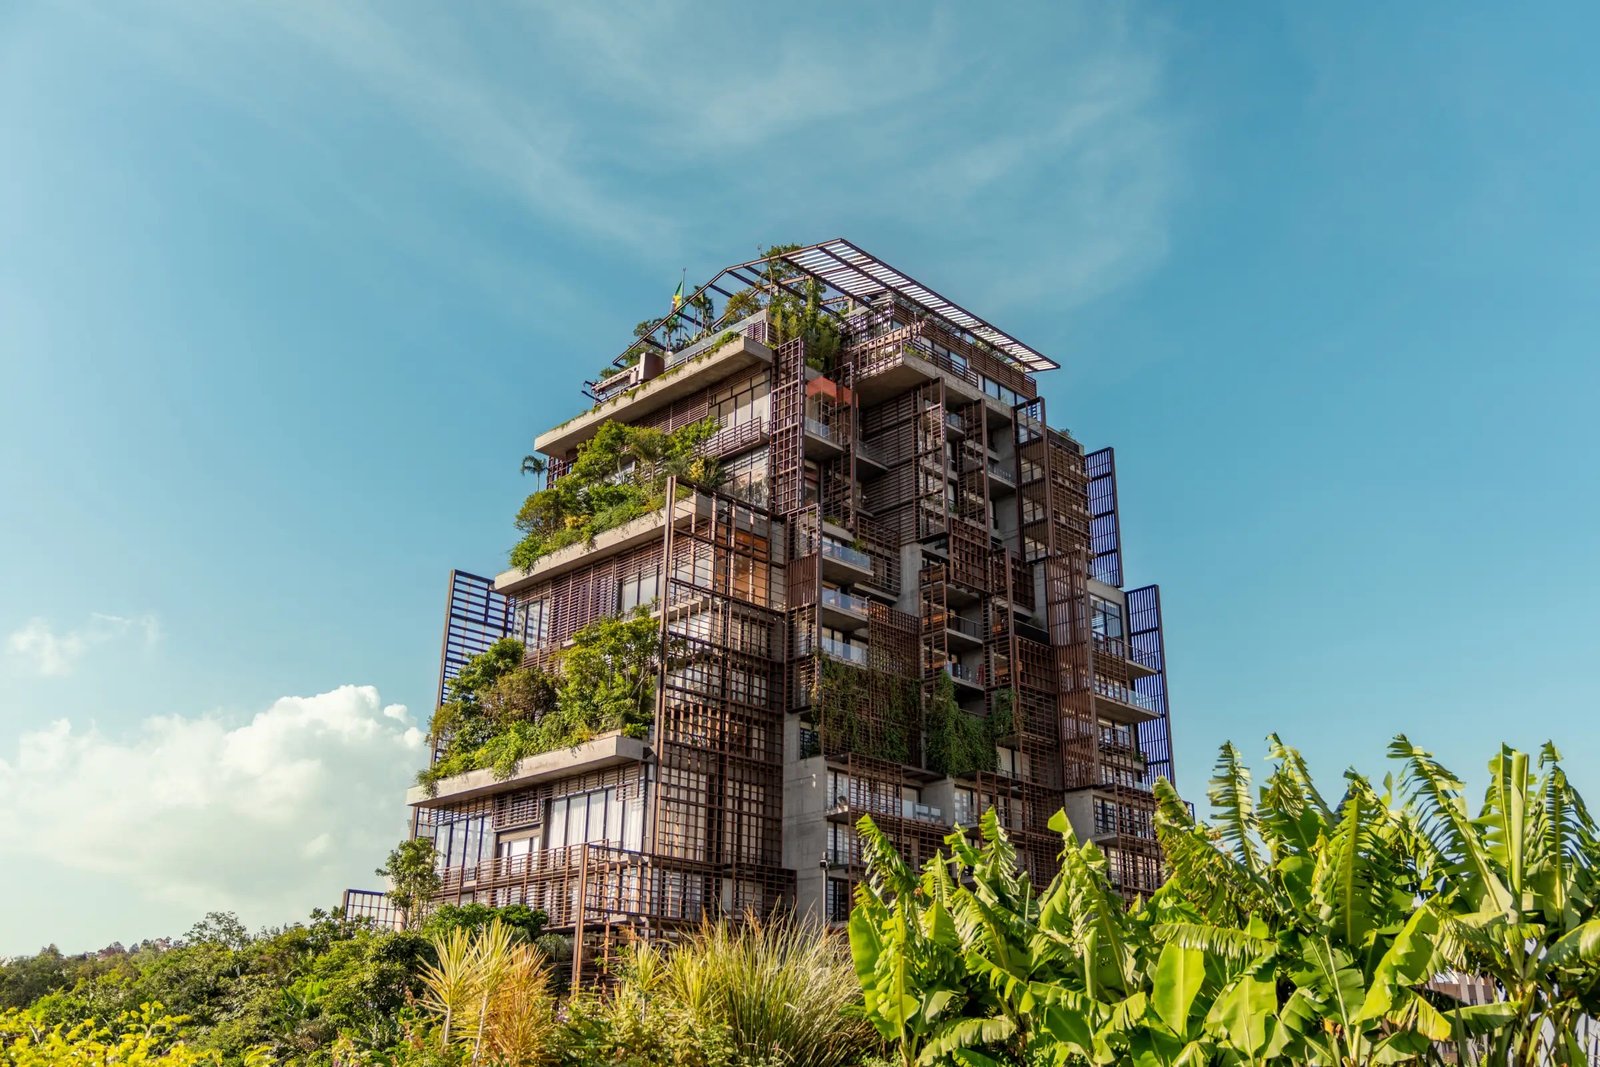
    Here’s a specific project example: The Rosewood Hotel in São Paulo, designed by Jean Nouvel. The 25-storey tower features an extensive lattice system on its exterior that, over time, is expected to fill in with greenery from adjacent roof gardens.

    The hotel opened in 2022, and street view images from 2024 reveal that it still has some growing to do, but clearly it’s a popular idea. I was just in the wrong city.


    Photos via Rosewood São Paulo